

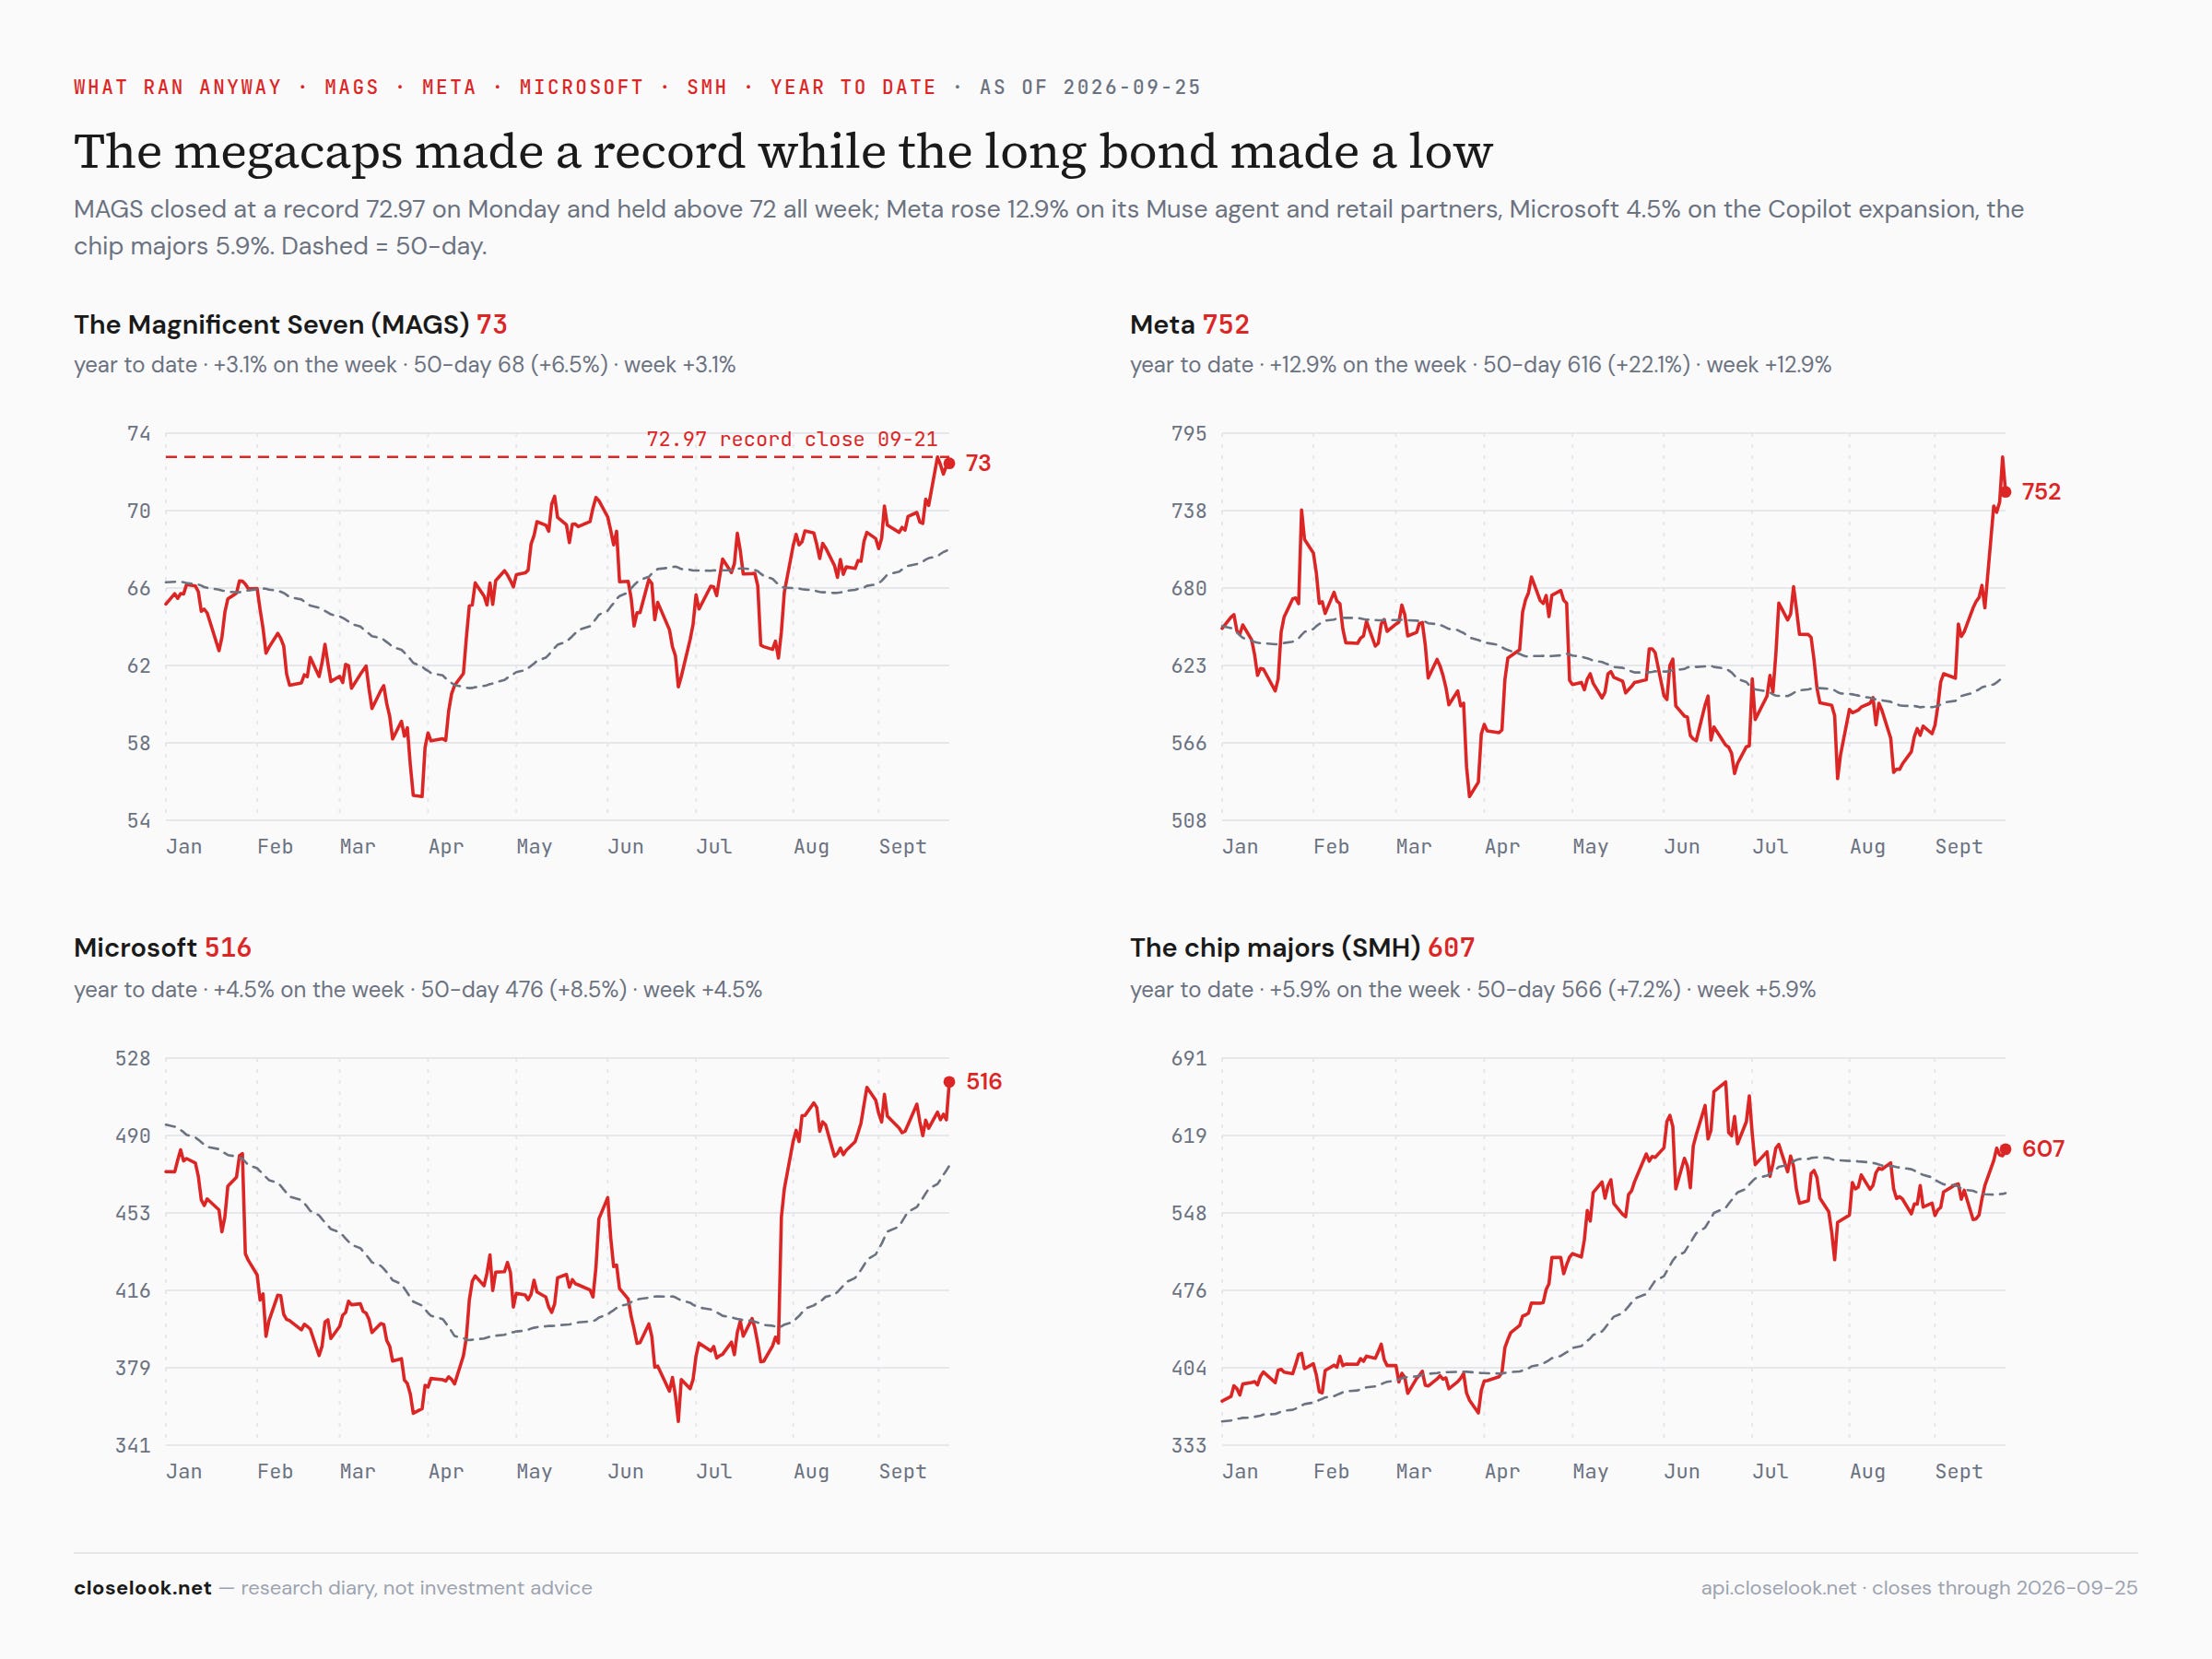
The builder rose 5% with all thirty-six of its sectors green and has doubled in 2026; the runner set a record on Wednesday; the applications index stood still while Meta and Microsoft rose and the software sellers fell. Five winners and five losers of the week, with the catalyst behind each and where it fits.
1 · This Week’s Action
Where this letter sits, in one line. Saturday’s Global letter read the money’s geography and Sunday’s US letter the tape; this one reads the names inside the three AI indices — what was bought, what was sold, and whether the flow underneath agrees.
The selection, first — five winners and five losers of the week, with the catalyst and where each fits.
Winner one — Global Unichip (Taiwan), +31.2% on the week, +39.2% on the month, +301% on the year, at a record NT$8,525. The catalyst is structural rather than a headline: the largest cloud companies want their own processors, and GUC is one of the few houses that designs them — it is the back-end design partner behind Google’s Arm-based CPU and custom accelerators for the hyperscalers. The week the chip designers were bought everywhere — Arm +12.6%, AMD +12.6%, Cadence +15.3% — the design house that turns a hyperscaler’s specification into silicon was bought hardest. Where it fits: the design layer, which the Handoff Board shows taking the lead from the physical layer this week. Directional Flow agrees: a score of 153, accelerating up, one of only six Rubin members whose force is still building.
Winner two — Ibiden (Japan), +22.1% on the week, +24.2% on the month, +247% on the year. Tokyo was shut Monday to Wednesday for Silver Week and reopened into a chip index that had risen more than 8% without it; Ibiden jumped 14.6% on Thursday. Two more reasons were in the price: a 2-for-1 stock split effective September 30, and the company’s last results — sales +26%, operating profit +52% on demand for the substrates that sit under every AI accelerator. Where it fits: substrates and interposers, Rubin’s second-best sector on the week (+12.6%) and on the month (+13.1%). The flow reads 177 but losing force (−19 on the month) — a price catching up after a holiday, not yet a new wave of flow.
Winner three — Everpure (US; formerly Pure Storage), +21.0% on the week, +88% on the year, at a record 126. Two catalysts in one week: S&P 500 inclusion at the open on Monday September 21, and an analyst day that reaffirmed this year’s outlook and set a preliminary fiscal-2028 target of $7.0–7.3 billion in revenue and $1.7–1.9 billion of operating profit, as it moves from storage boxes into AI data platforms and hyperscale. Where it fits: the opex layer’s data-and-memory sector (+5.6% on the week). The flow agrees: 48, accelerating up, +25.7 on the month.
Winner four — Astera Labs (US), +20.2% on the week, +25.6% on the month, +119% on the year. +12% on Monday in the chip rally that took AMD past a trillion dollars; underneath, a third-quarter guide of $540–560 million — about 40% above the second quarter — its Scorpio X switches in volume production and a design win as d-Matrix’s connectivity partner. Where it fits: the connectivity inside the AI server, the part of the rack that moves data between chips. Flow 129, flat on the month — strong, but not accelerating. It is still 24.5% under its June high.
Winner five — Meta (US), +12.9% on the week, +30.5% on the month, at 751.66. +11.3% on Monday when its Muse agent reached No. 1 on Apple’s US App Store; on Wednesday its Connect event named Walmart, Best Buy, Gap, Sephora and Wayfair as shopping partners for the agent and showed new glasses at $449, $349 and $249. Where it fits: the applications index’s megacap gateway, the only one of its nine sectors positive on the year (+16.3%). The flow turned: −7 but reversing up, +12.4 on the month — the flow has started to move the price’s way.
Loser one — Zhipu / Z.ai (Hong Kong), −18.8% on the week, −45.4% on the month. Two catalysts, both about money: a roughly $5 billion financing announced on September 13 — shares placed at a 10% discount plus convertible bonds, the second big raise in two months — and DeepSeek’s latest price cuts on its fast models, which pull every Chinese model maker’s pricing down with it. Where it fits: the foundation-model sector of the Agentic Ecosystem, which is Zhipu alone: −18.7% on the week, −45.4% on the month, and still +378% on the year. The flow is draining hardest of any name we track: −29.4 on five days, −112.8 on the month. The token cross-check says why: Zhipu’s fast model is the second most-used model on the tracker this week, and it is being used at DeepSeek’s prices.
Loser two — Intuit (US), −9.0% on the week, −20.3% on the month, −58% on the year. The investor day reset the growth outlook — fiscal 2027 growth of 9–10% against 14% this year — and the market reads the gap as AI agents doing the tax and bookkeeping work Intuit charges for. Where it fits: the applications index’s enterprise and software sellers, the side of the stack that lost when the platforms’ agents gained. Flow −88, the second-weakest in the applications index — reversing up by +17.6 on the month, but from very deep.
Loser three — Oracle (US), −7.1% on the week, −7.9% on the month, −30% on the year, 45% under its June high. On Thursday Oracle sent a force-majeure notice to the developer of Project Jupiter, the New Mexico Stargate campus, a unit of Blue Owl: the gas pipeline meant to power the site’s fuel cells has been delayed to February 2027, and Oracle wants the right to delay payments if the site misses its 2028 date. Oracle says the project remains on schedule. Where it fits: the financing of the buildout — the debt-funded rung of the house credit ladder, and the one the credit tape below flags. Its 2055 bond yields 7.90%, +91 basis points since June.
Loser four — UiPath (US), −6.9% on the week, −25.7% on the month, −24% on the year. The September 4 results guided third-quarter growth down to about 8%, half the pace of the second quarter; this week BMO and RBC cut their targets to $15, into a week of rising Treasury yields. Where it fits: automation software, the category the platforms’ agents are built to replace. Flow 9 and accelerating up (+22.6 on the month) — the flow is recovering faster than the price.
Loser five — Coherent (US), −6.8% on the week, 31% under its June high, still +60% on the year. No company news: profit-taking in the optical names after back-to-back strong days, with price targets from Stifel and Needham still at $420. Where it fits: the physical interconnect — lasers and optics — the layer the money left for the designers. The flow says it is not only a week: 67, −7.6 on five days and −38.4 on the month, losing force.
The five winners are designers, packagers and the platform with a product; the five losers are the seat sellers, the model maker at DeepSeek’s prices, the financing of the buildout and the optics after a run. That is the whole week in ten names.
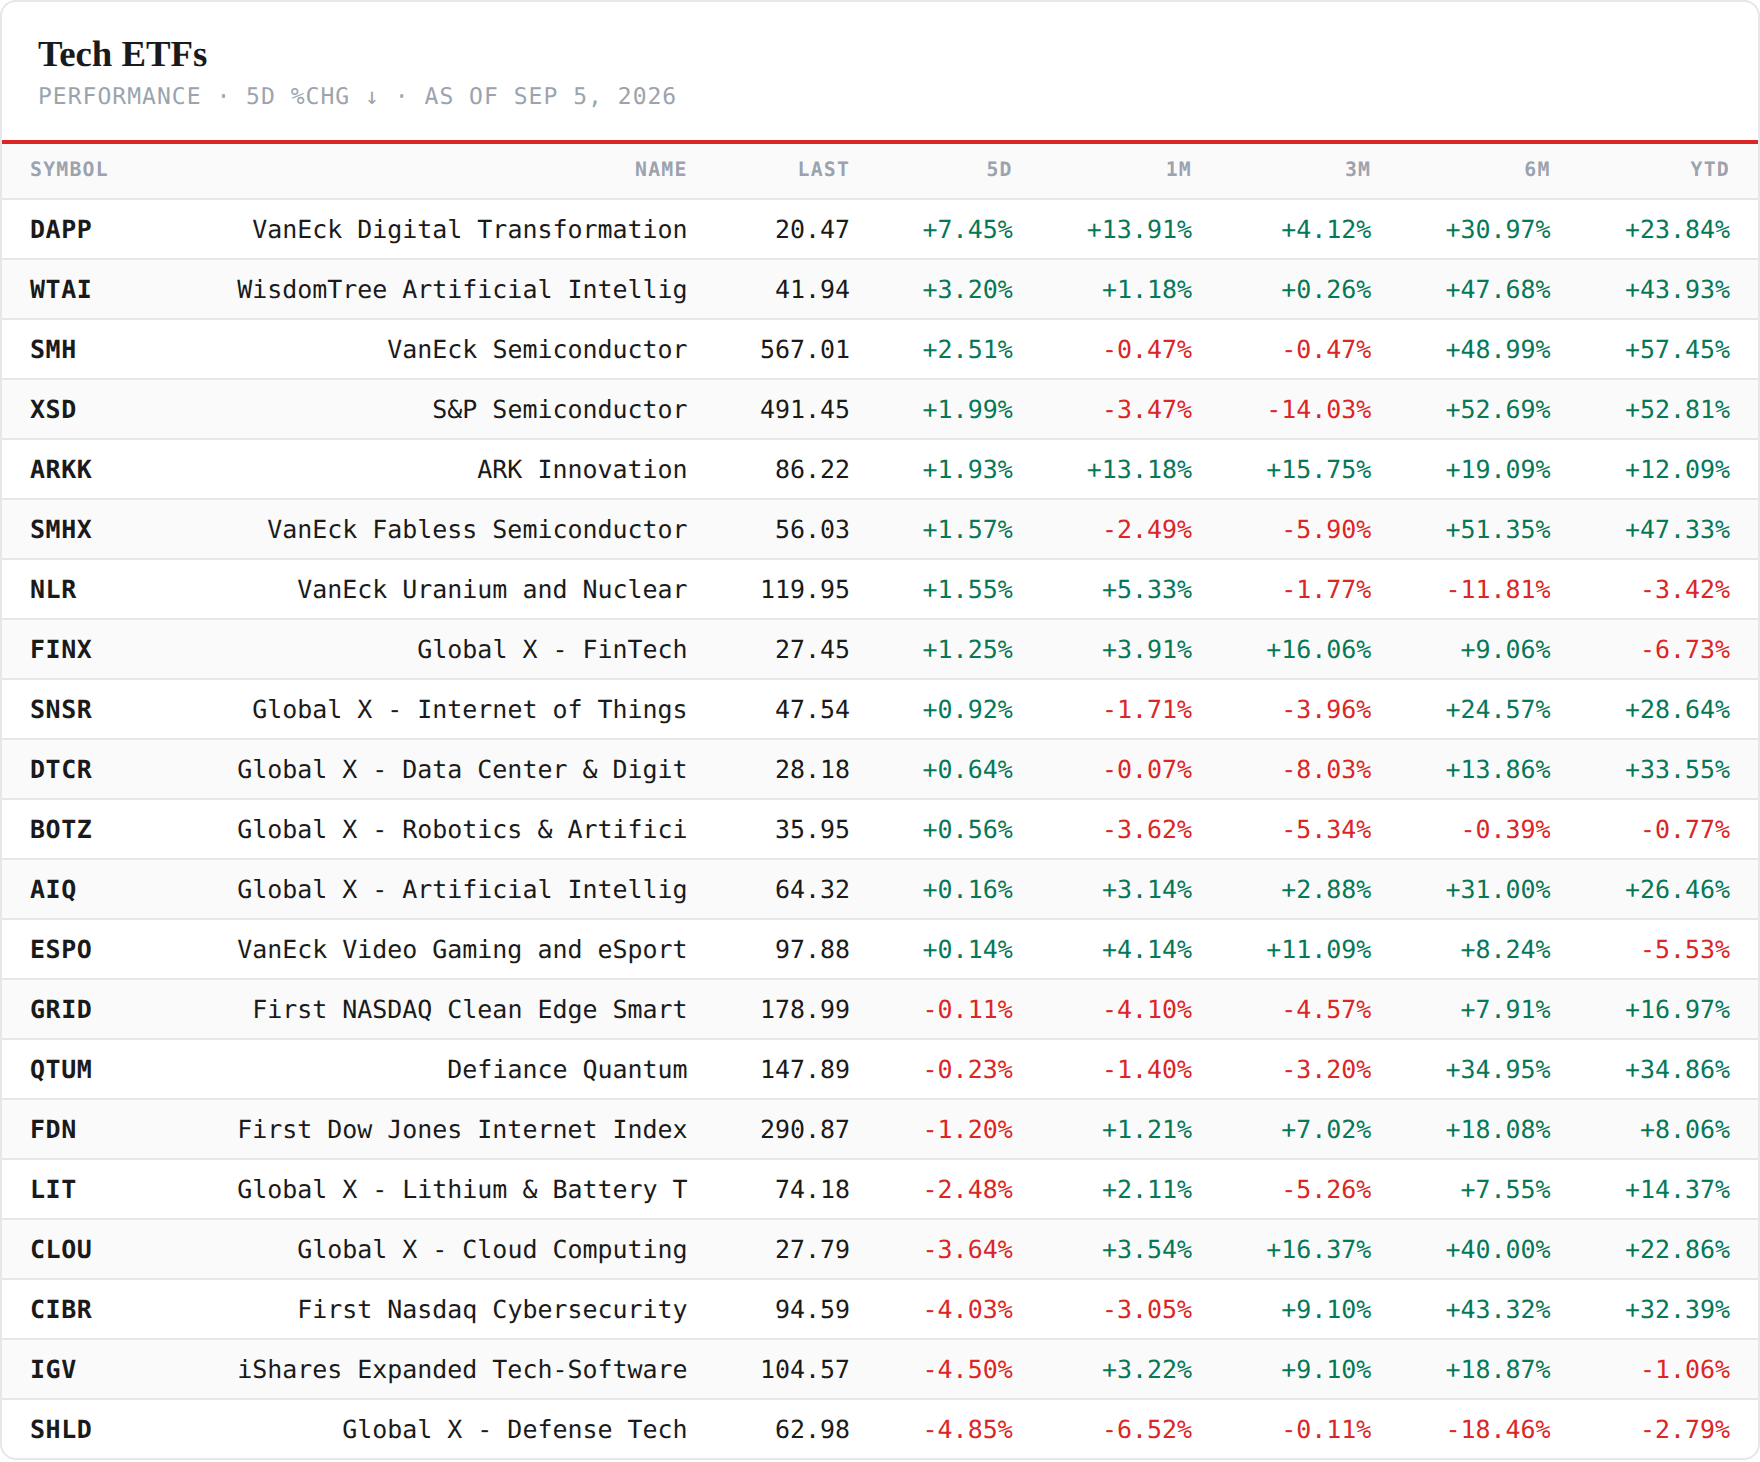
The tech shelf — the silicon led, the code followed. Fourteen green of twenty-one: the fabless chip fund +7.78%, the equal-weight semis +6.73%, the chip majors +5.86%, the AI funds +2.9% to +4.3%, cloud +2.05%, software +1.59%, cybersecurity +1.08%. The chips beat software by four points, after software beat the chips by two last week.
The factor view — momentum at the 99th percentile. The factor gauge closed at 170.3 against its 50-day at 156.7, “momentum leading — risk appetite building”; momentum +2.49% on the week, low volatility −1.76%.
2 · The Three Functional Indices — index, sectors, stocks
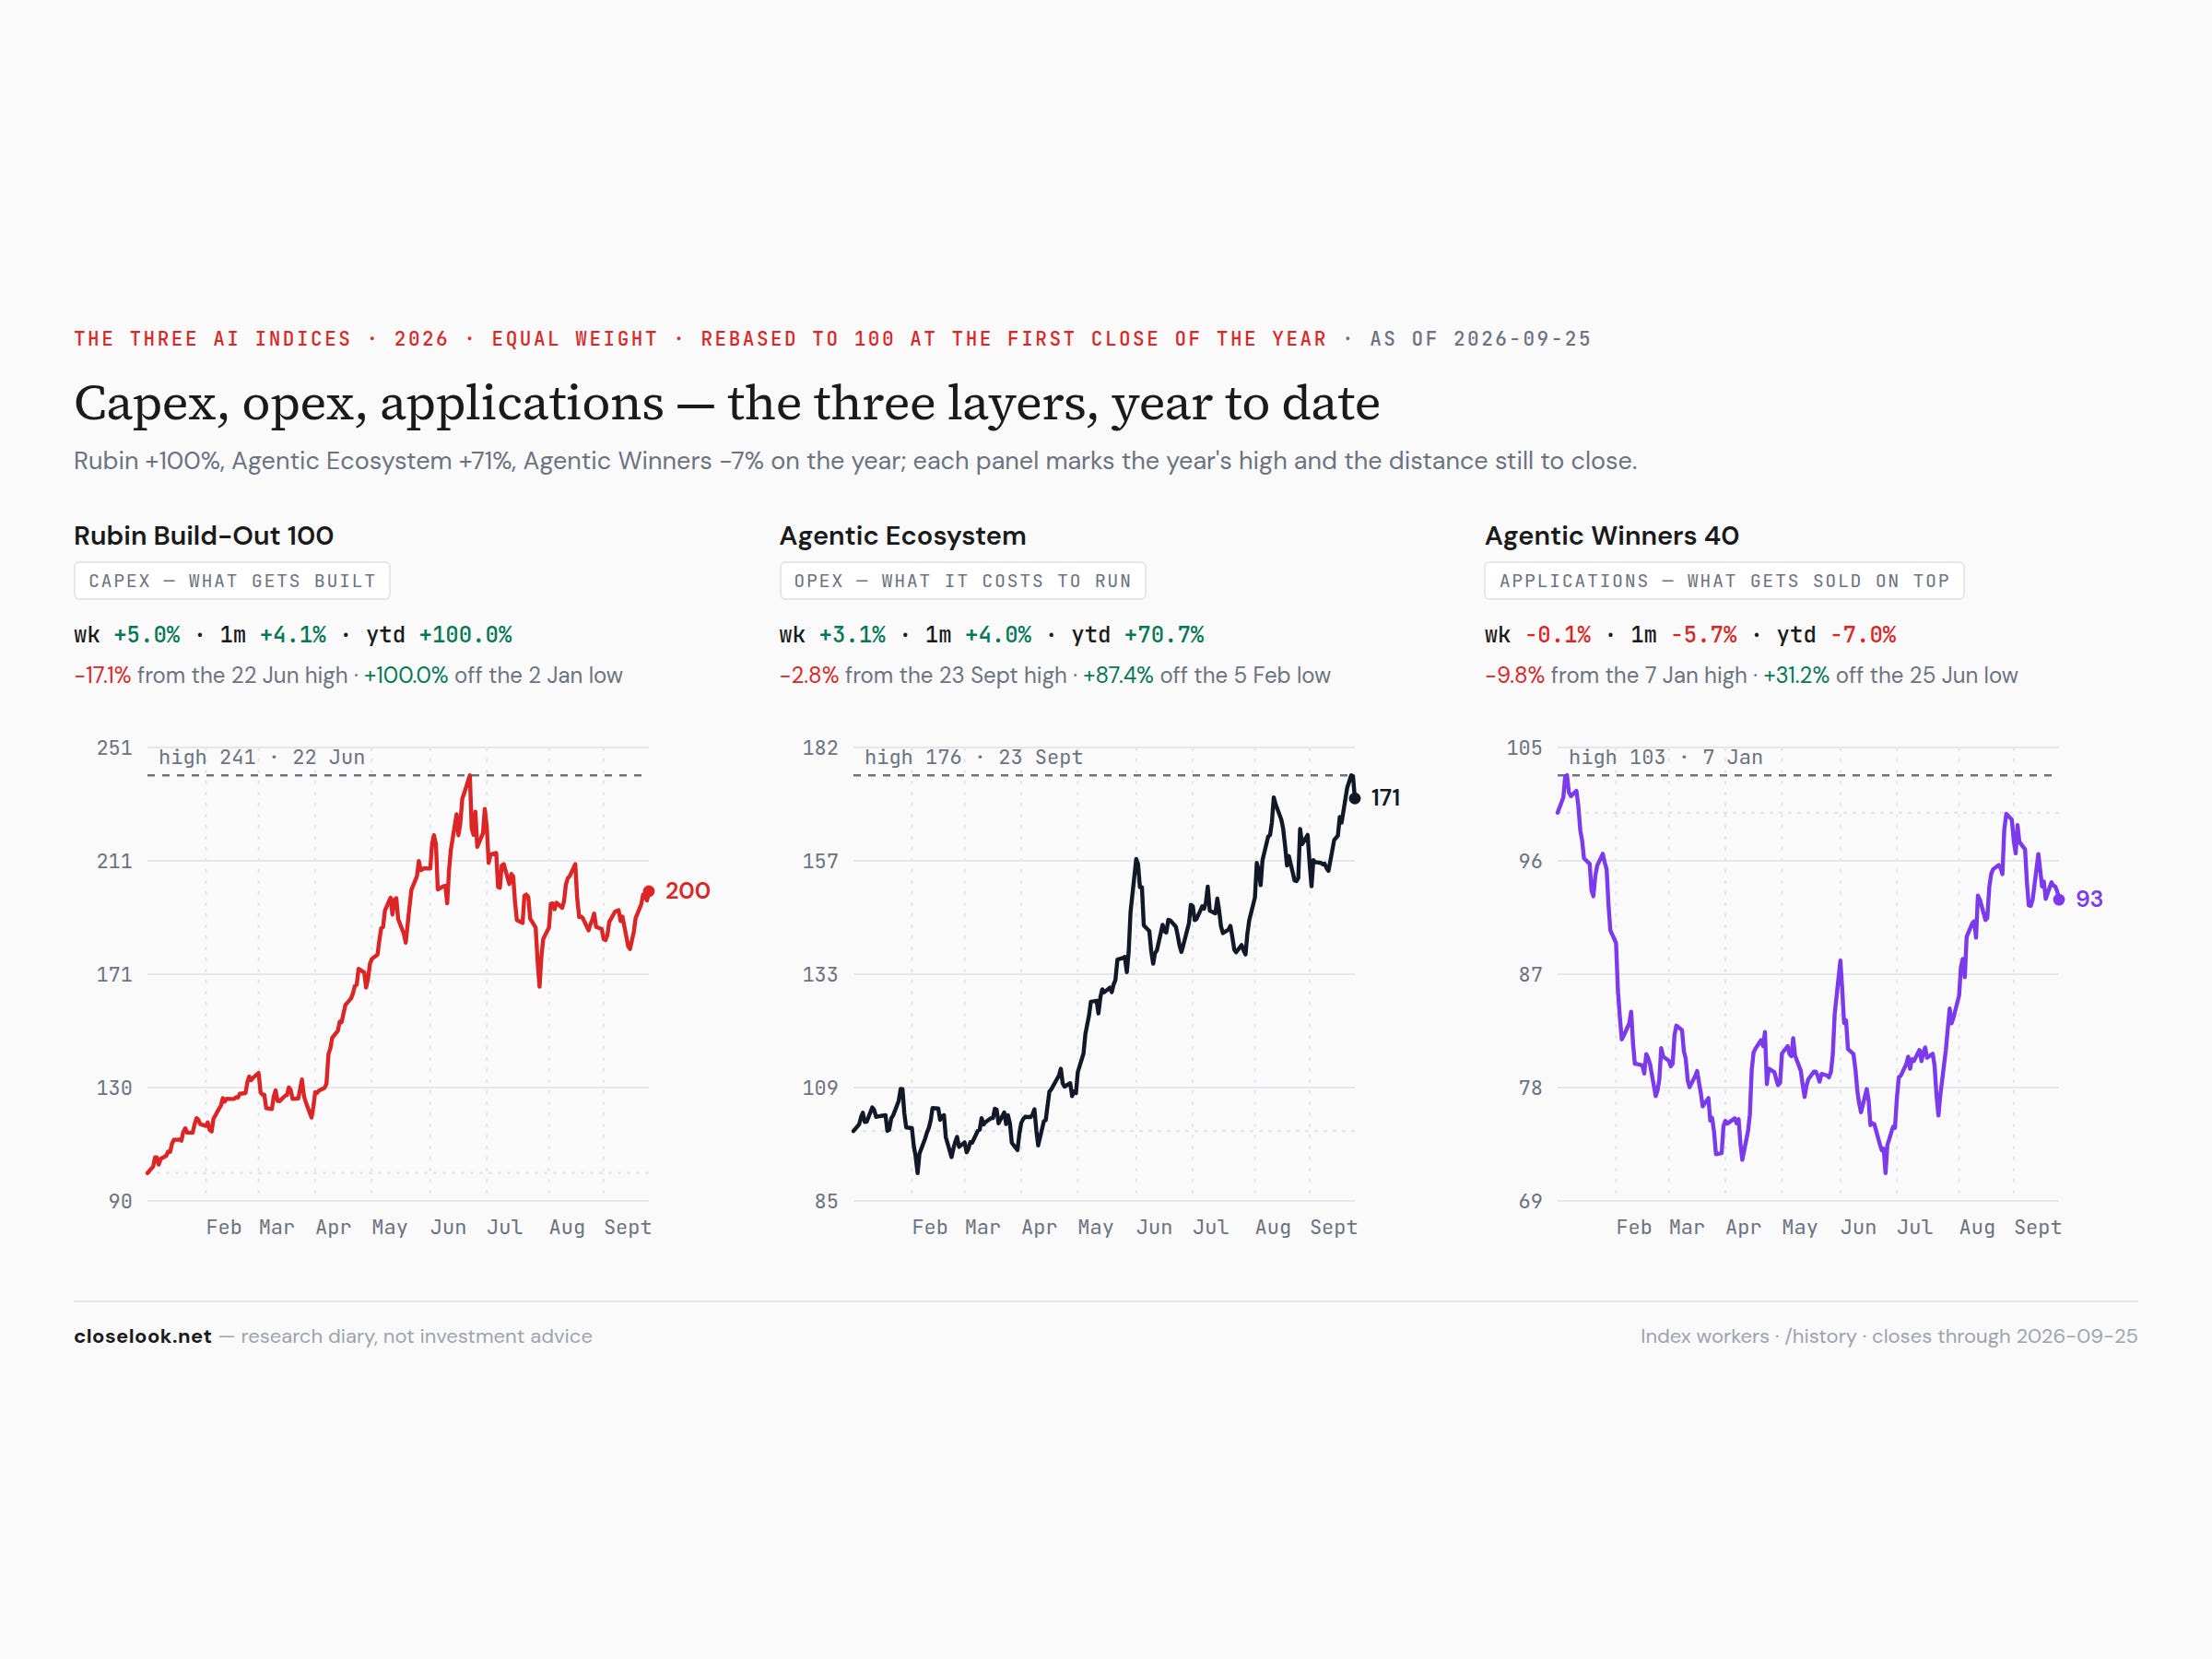
The four buckets, briefly. New readers: we cut the growth trade into functional indices rather than sectors — capex (Rubin Build-Out: what gets built), opex (Agentic Ecosystem: what it costs to run), applications (Agentic Winners 40: what gets sold on top) — and a control group with no AI thesis (HALO). Each index is equal-weighted and split into sectors; the flow tables — Directional Flow — score whether each member’s force is building or fading, on an absolute scale and by its change over five and twenty-one days.
Rubin Build-Out — capex
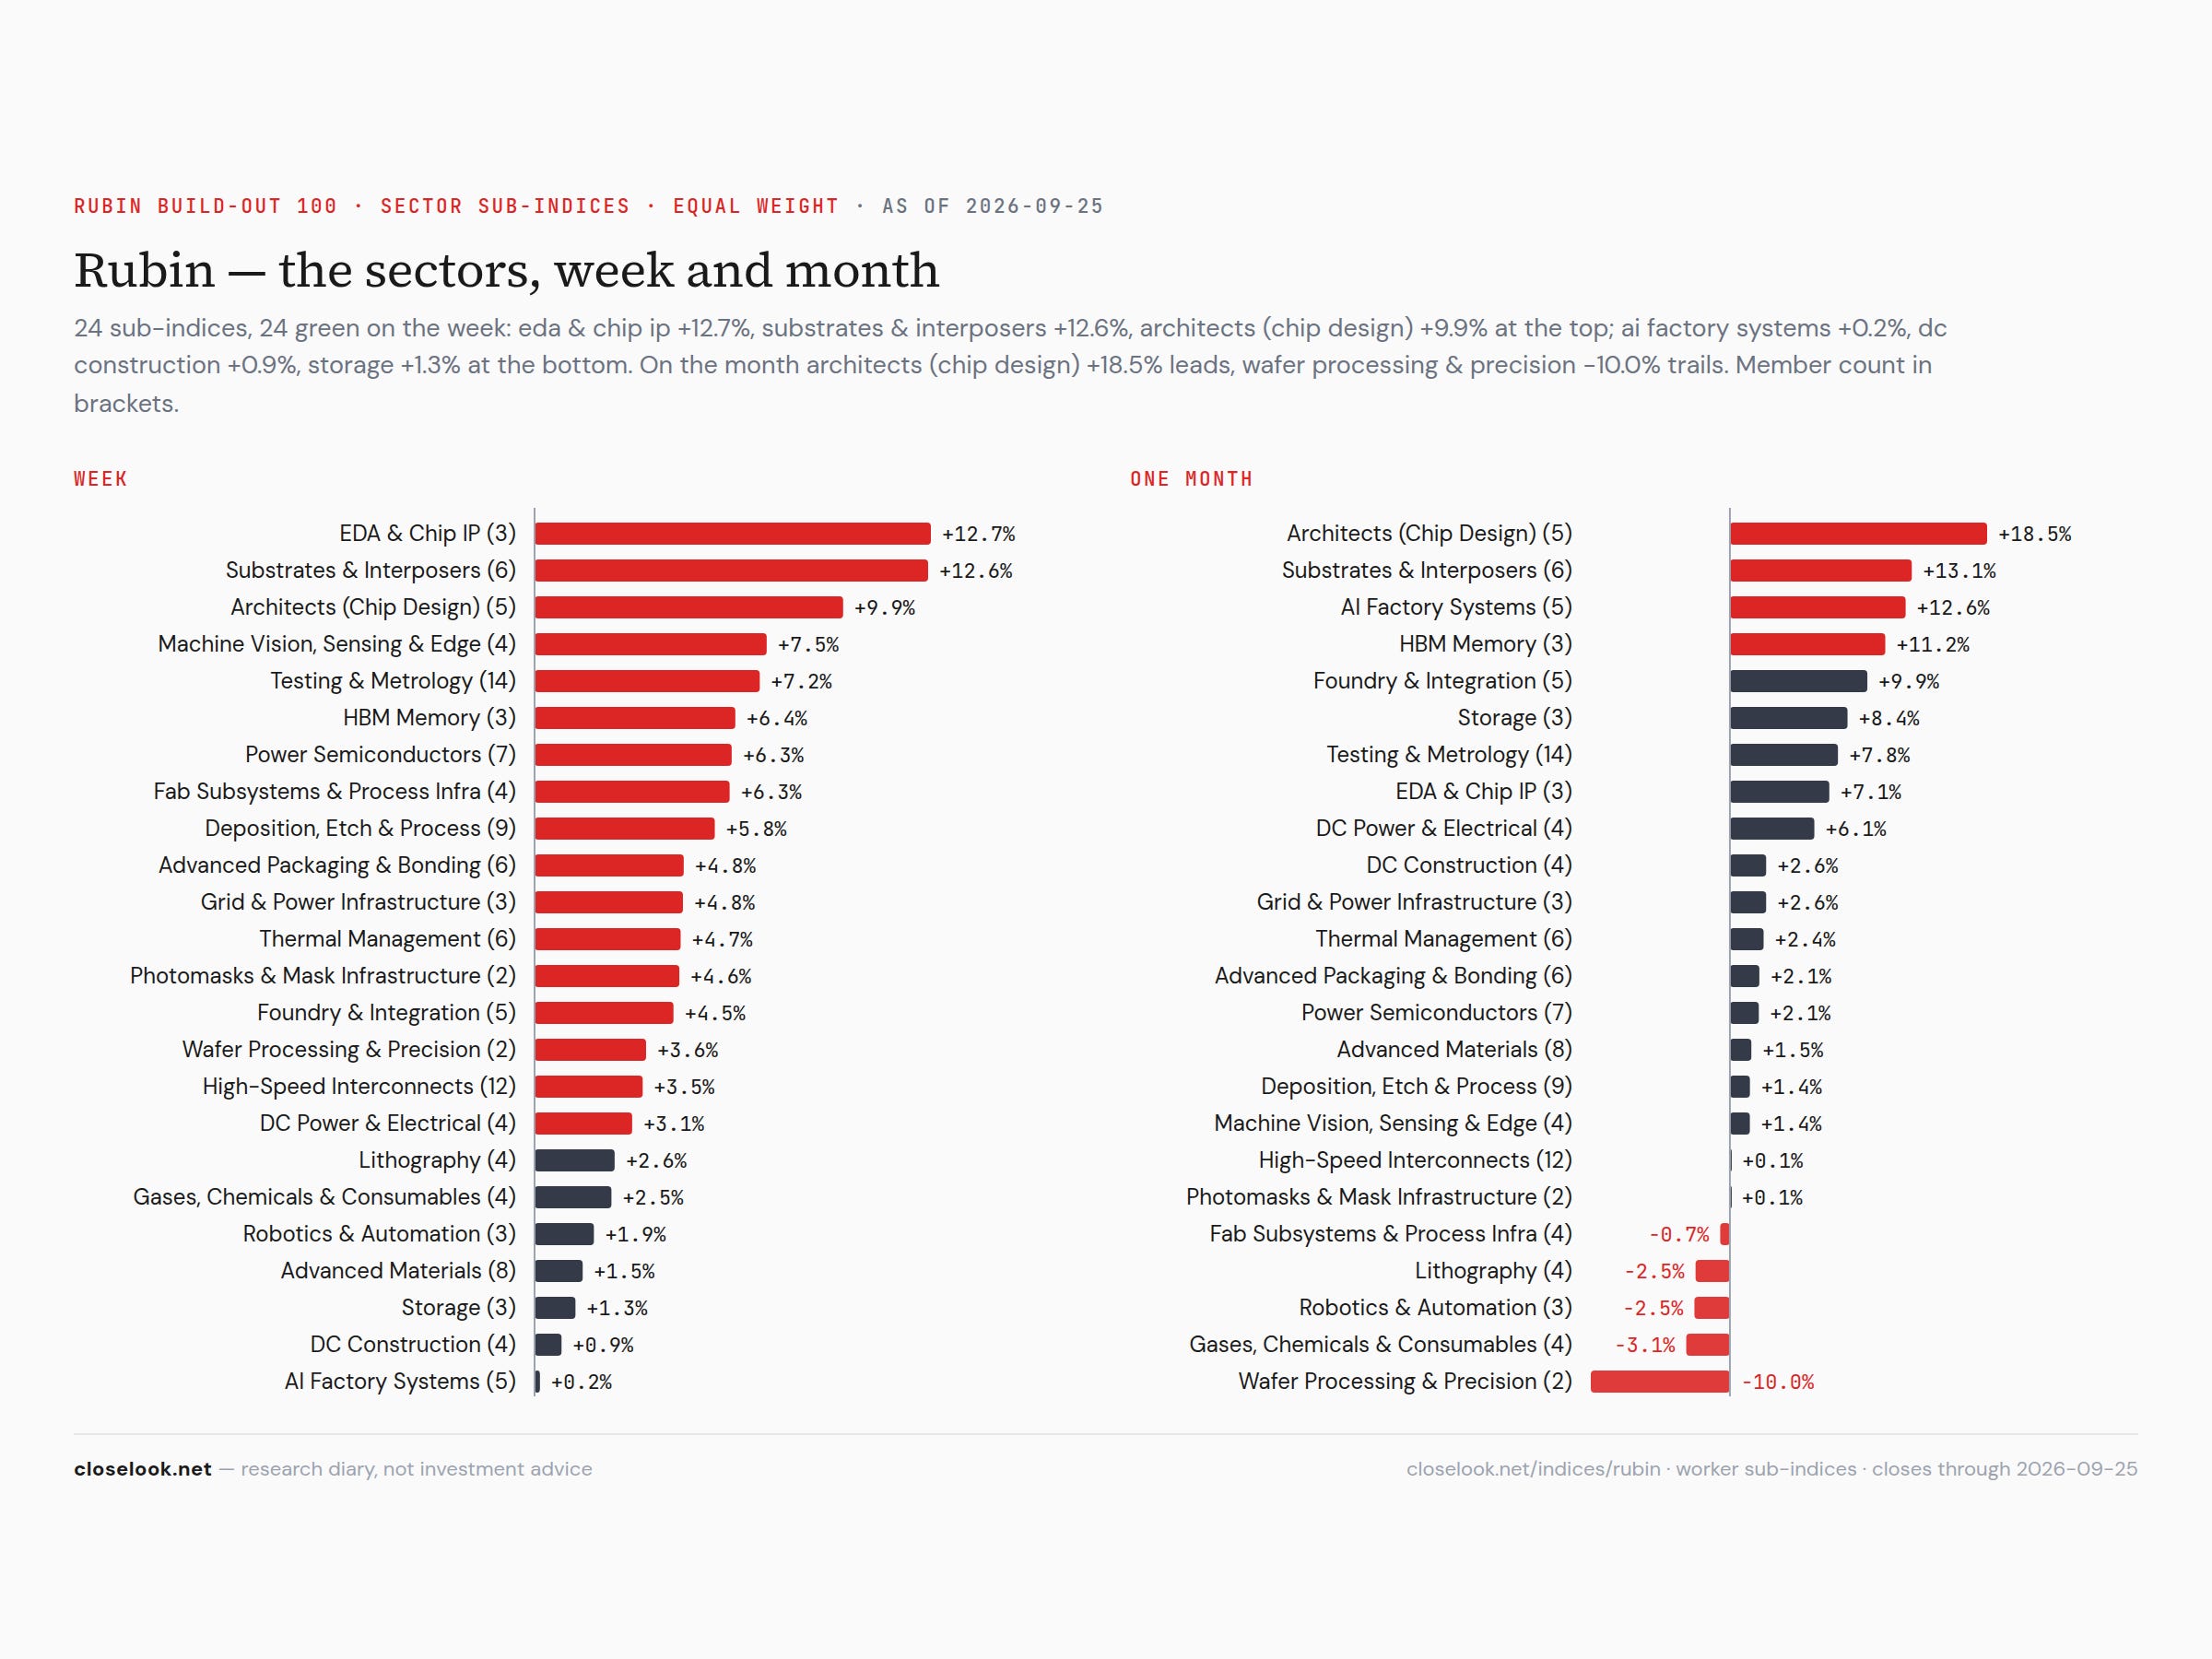
The index: +5.05% on the week to 2,055.72, +4.13% on the month, +100.0% on the year. 17.1% under its June 22 high, 20.4% above its July 29 low. All thirty-six sectors rose on the week; 109 of 126 members rose, median +4.95%.
The sectors, three windows. Week — best: EDA and chip IP +12.7%, substrates and interposers +12.6%, design +10.8%, the chip architects +9.9%, machine vision +7.5%. Worst: AI factory systems +0.2%, data-center construction +0.9%, the AI factory +1.1%, storage +1.3%, advanced materials +1.5% — every one still green. Month — best: the architects +18.5%, substrates +13.1%, AI factory systems +12.6%, design +12.2%, HBM memory +11.2%. Worst: wafer processing −10.0%, gases and chemicals −3.1%, robotics −2.5%, lithography −2.5%. Year — best: storage +359.5%, substrates +233.1%, HBM memory +200.1%, the Asia-Pacific ex-Japan constituents +153.7%, AI factory systems +142.7%. Worst: photomasks −1.0%, wafer processing +10.6%, robotics +12.2%. The year belongs to memory and substrates; the month and the week to design.
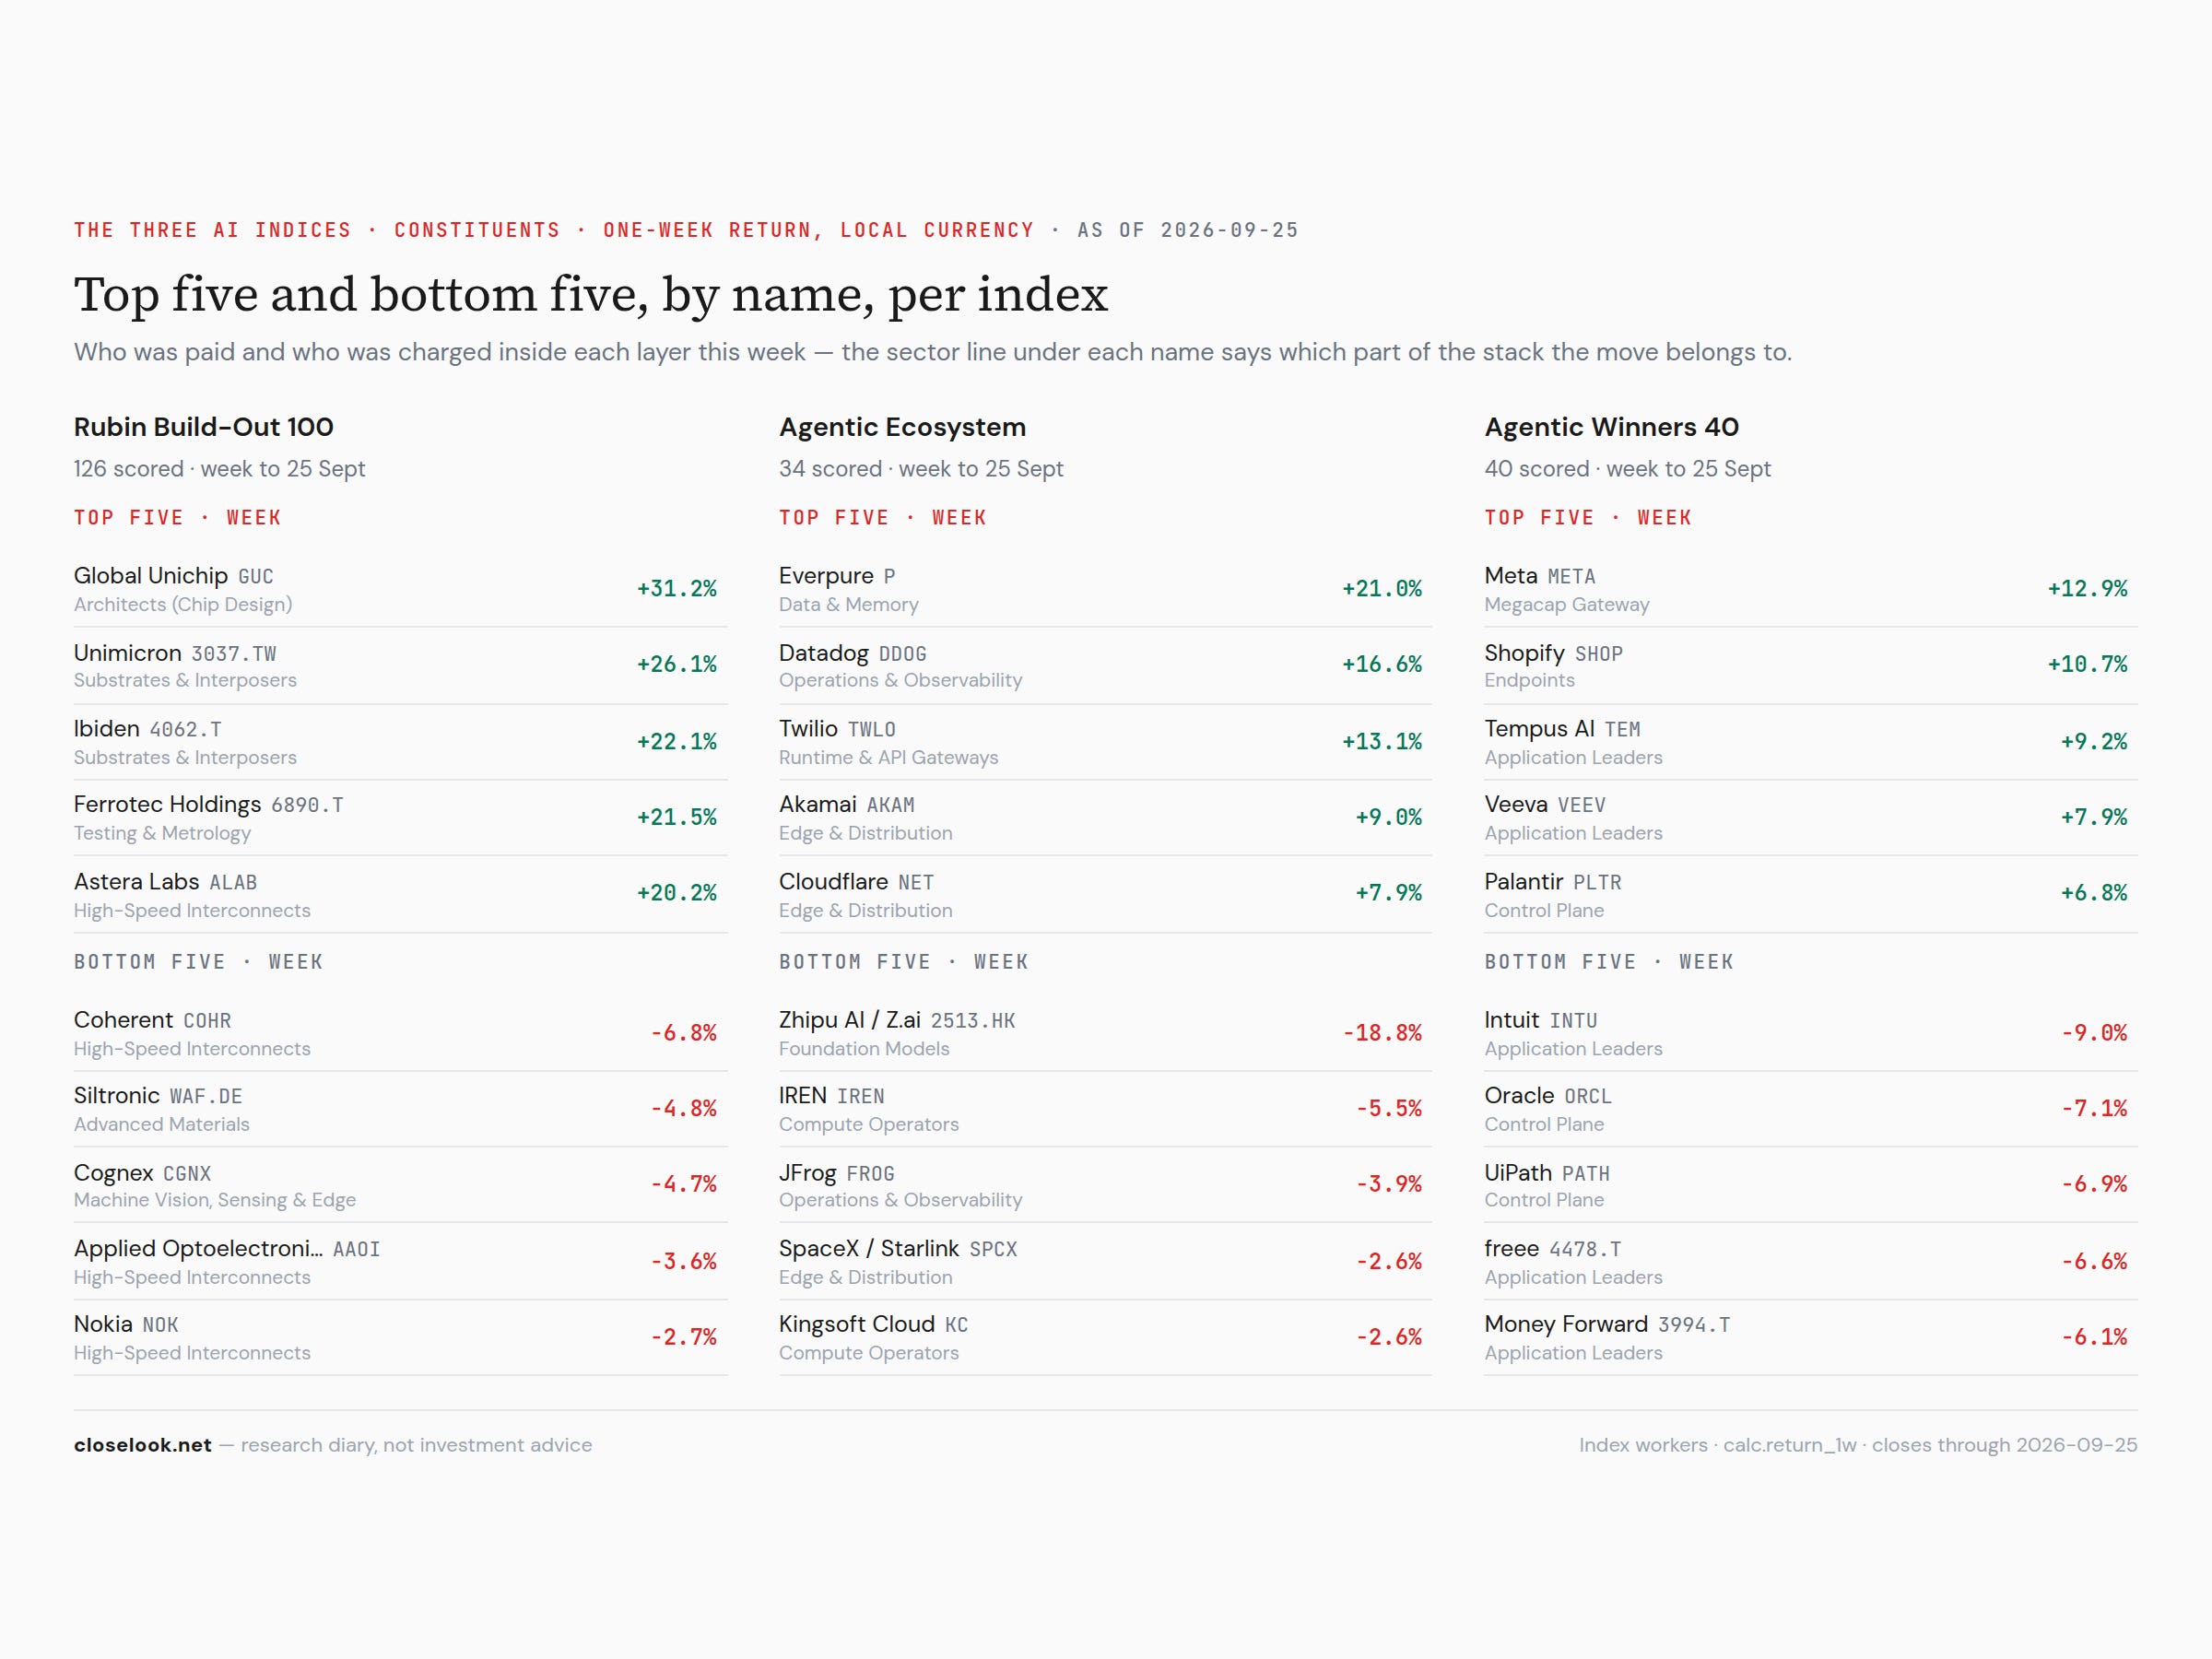
The stocks, three windows. Week — best: Global Unichip +31.2%, Unimicron +26.1%, Ibiden +22.1%, Ferrotec +21.5%, Astera Labs +20.2%, Credo +19.9%. Worst: Coherent −6.8%, Siltronic −4.8%, Cognex −4.7%, Applied Optoelectronics −3.6%, Nokia −2.7%, SpaceX −2.6%. Month — best: Intel +39.4%, Global Unichip +39.2%, AT&S +38.6%, Bloom Energy +32.3%, Cohu +31.2%, AMD +31.1%. Worst: DISCO −11.7%, Applied Optoelectronics −10.9%, Ebara −10.5%, Sumco −9.7%, Yaskawa −9.5%. Year: Unimicron +439%, Global Unichip +301%, Micron +279%, Ibiden +247%, Intel +233%, AMD +195%.
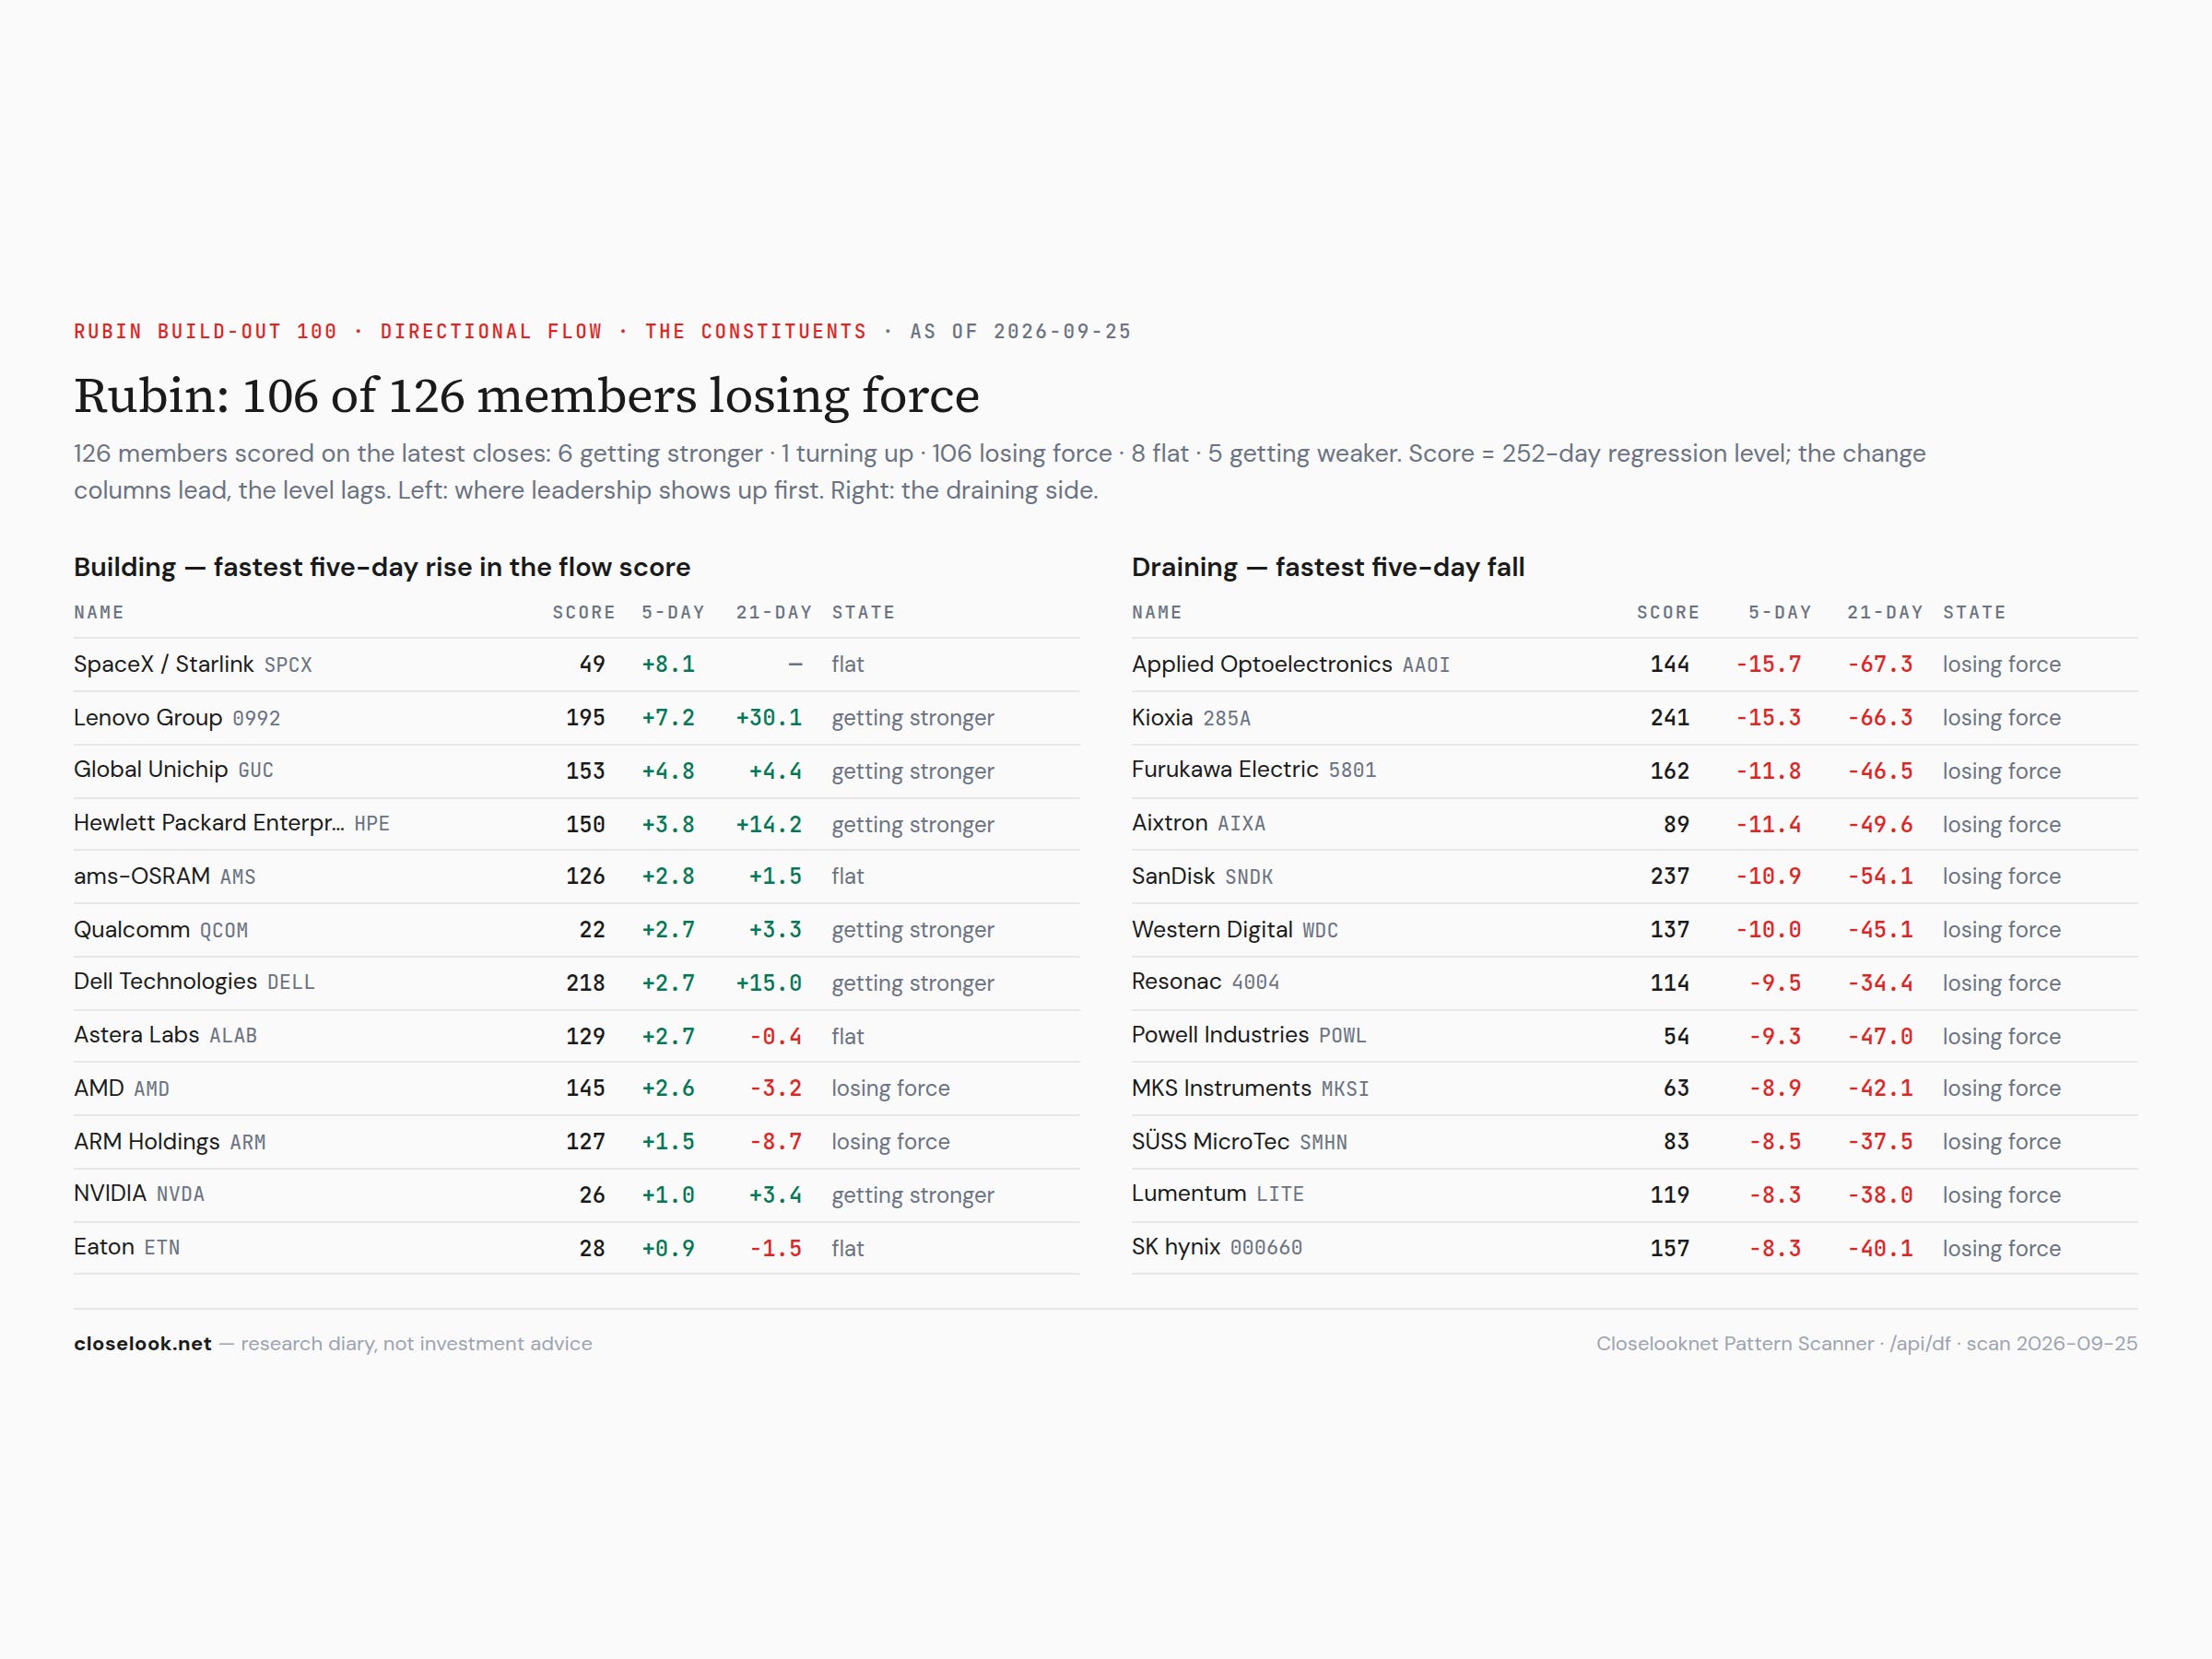
The flow laid over it. 107 of 126 members are losing force (decelerating up), 6 accelerating up, 5 accelerating down. That is the week’s most important Rubin fact: the price rose 5% while almost every member’s flow kept slowing. The strongest absolute scores: Kioxia 241, AT&S 237, SanDisk 237, Dell 218, Unimicron 208, Soitec 203. The fastest five-day risers: SpaceX +8.1, Lenovo +7.2, Global Unichip +4.8, HPE +3.8. The fastest drainers: Applied Optoelectronics −15.7, Kioxia −15.3, Furukawa −11.8, Aixtron −11.4, SanDisk −10.9, Western Digital −10.0. The memory names lead the year on price and are losing their flow fastest — a gap the letter has flagged for three weeks, and the reason Micron’s order book on Wednesday matters to this index more than to any other.
Agentic Ecosystem — opex
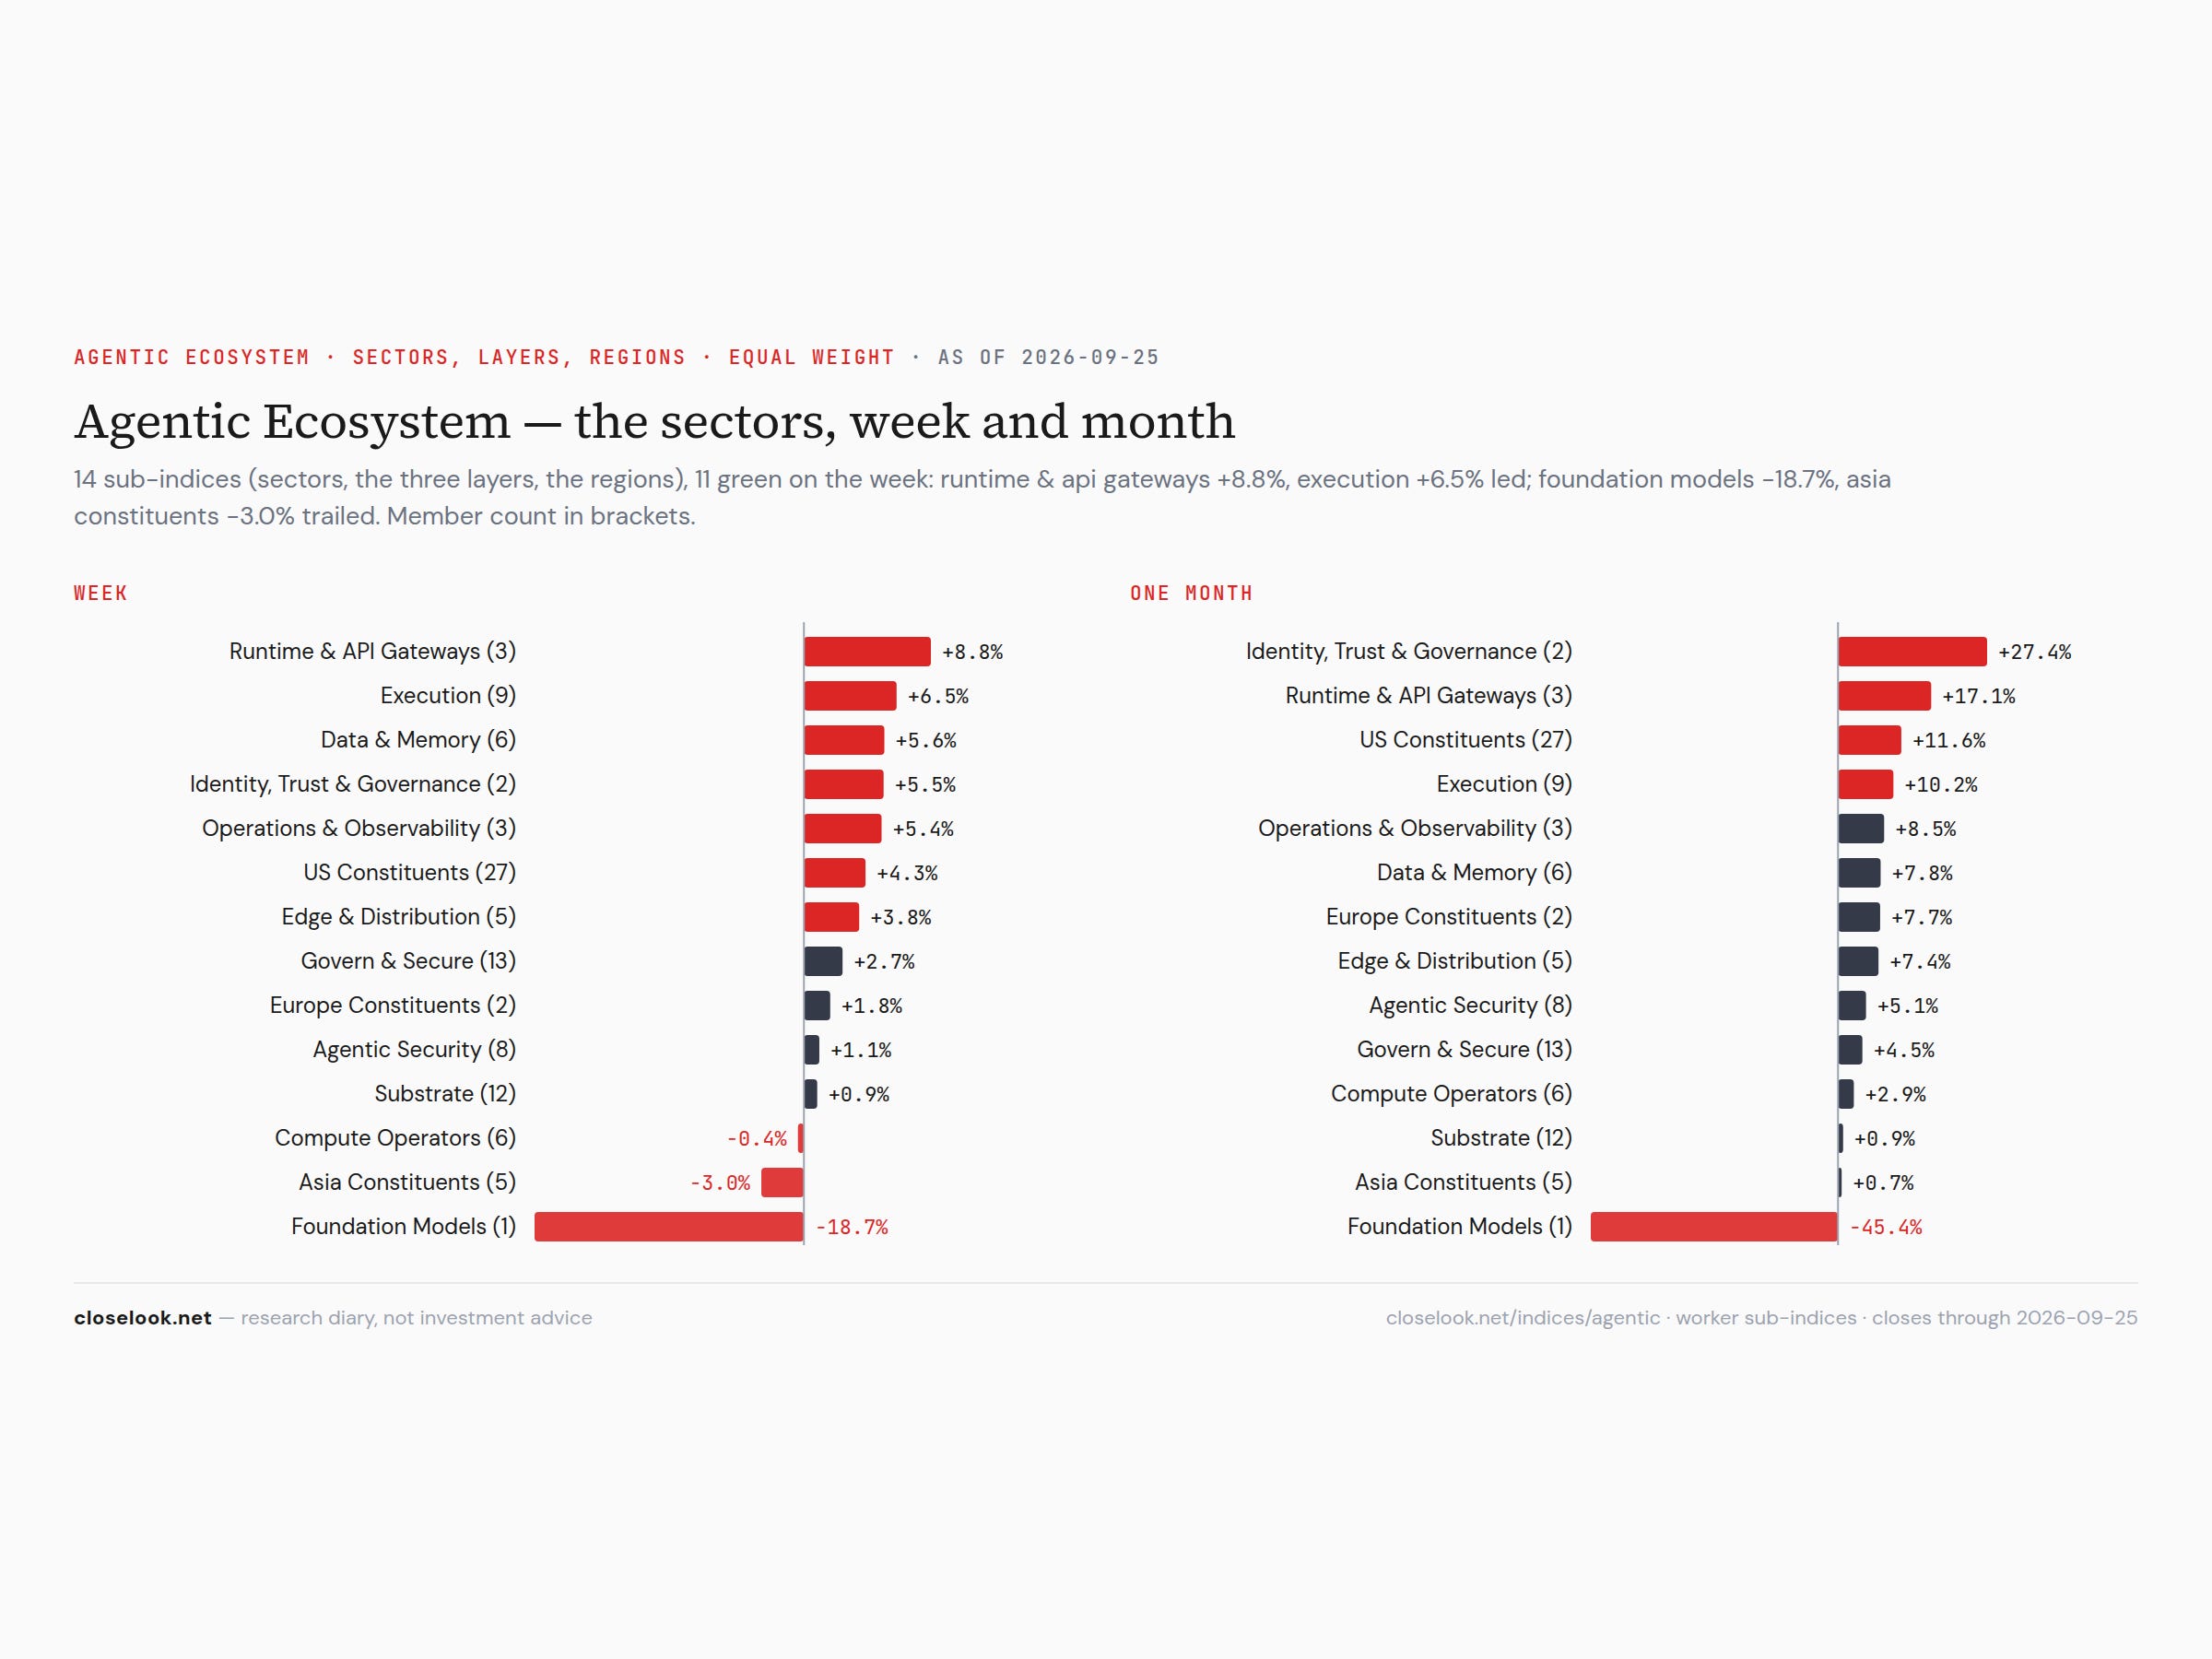
The index: +3.13% on the week to 1,684.38, +3.96% on the month, +70.7% on the year — a record on Wednesday at 1,732.81, 2.8% under it now. 24 of 34 members rose, median +3.07%.
The sectors, three windows. Week — best: runtime and API gateways +8.8%, execution +6.5%, data and memory +5.6%, identity and governance +5.5%, operations and observability +5.4%. Worst: foundation models −18.7%, Asia’s constituents −3.0%, compute operators −0.4%. Month — best: identity and governance +27.4%, runtime and gateways +17.1%, the US constituents +11.6%, execution +10.2%. Worst: foundation models −45.4%, Asia’s constituents +0.7%, the substrate +0.9%. Year — best: foundation models +378.3%, runtime and gateways +172.6%, Europe’s constituents +157.7%, execution +89.3%. Worst: Asia’s constituents +35.7%, data and memory +42.5%.
The stocks, three windows. Week — best: Everpure +21.0%, Datadog +16.6%, Twilio +13.1%, Akamai +9.0%, Cloudflare +7.9%, CoreWeave +7.7%. Worst: Zhipu −18.8%, IREN −5.5%, JFrog −3.9%, Kingsoft Cloud −2.6%, Zscaler −2.2%. Month — best: Okta +45.2%, CrowdStrike +33.3%, Sangfor +26.1%, Cloudflare +22.5%, DigitalOcean +21.5%, Twilio +20.7%. Worst: Zhipu −45.4%, Equinix −6.6%, Kingsoft Cloud −5.6%. Year: Nebius +184%, Okta +126%, CrowdStrike +115%, Datadog +97%, Cloudflare +77%.
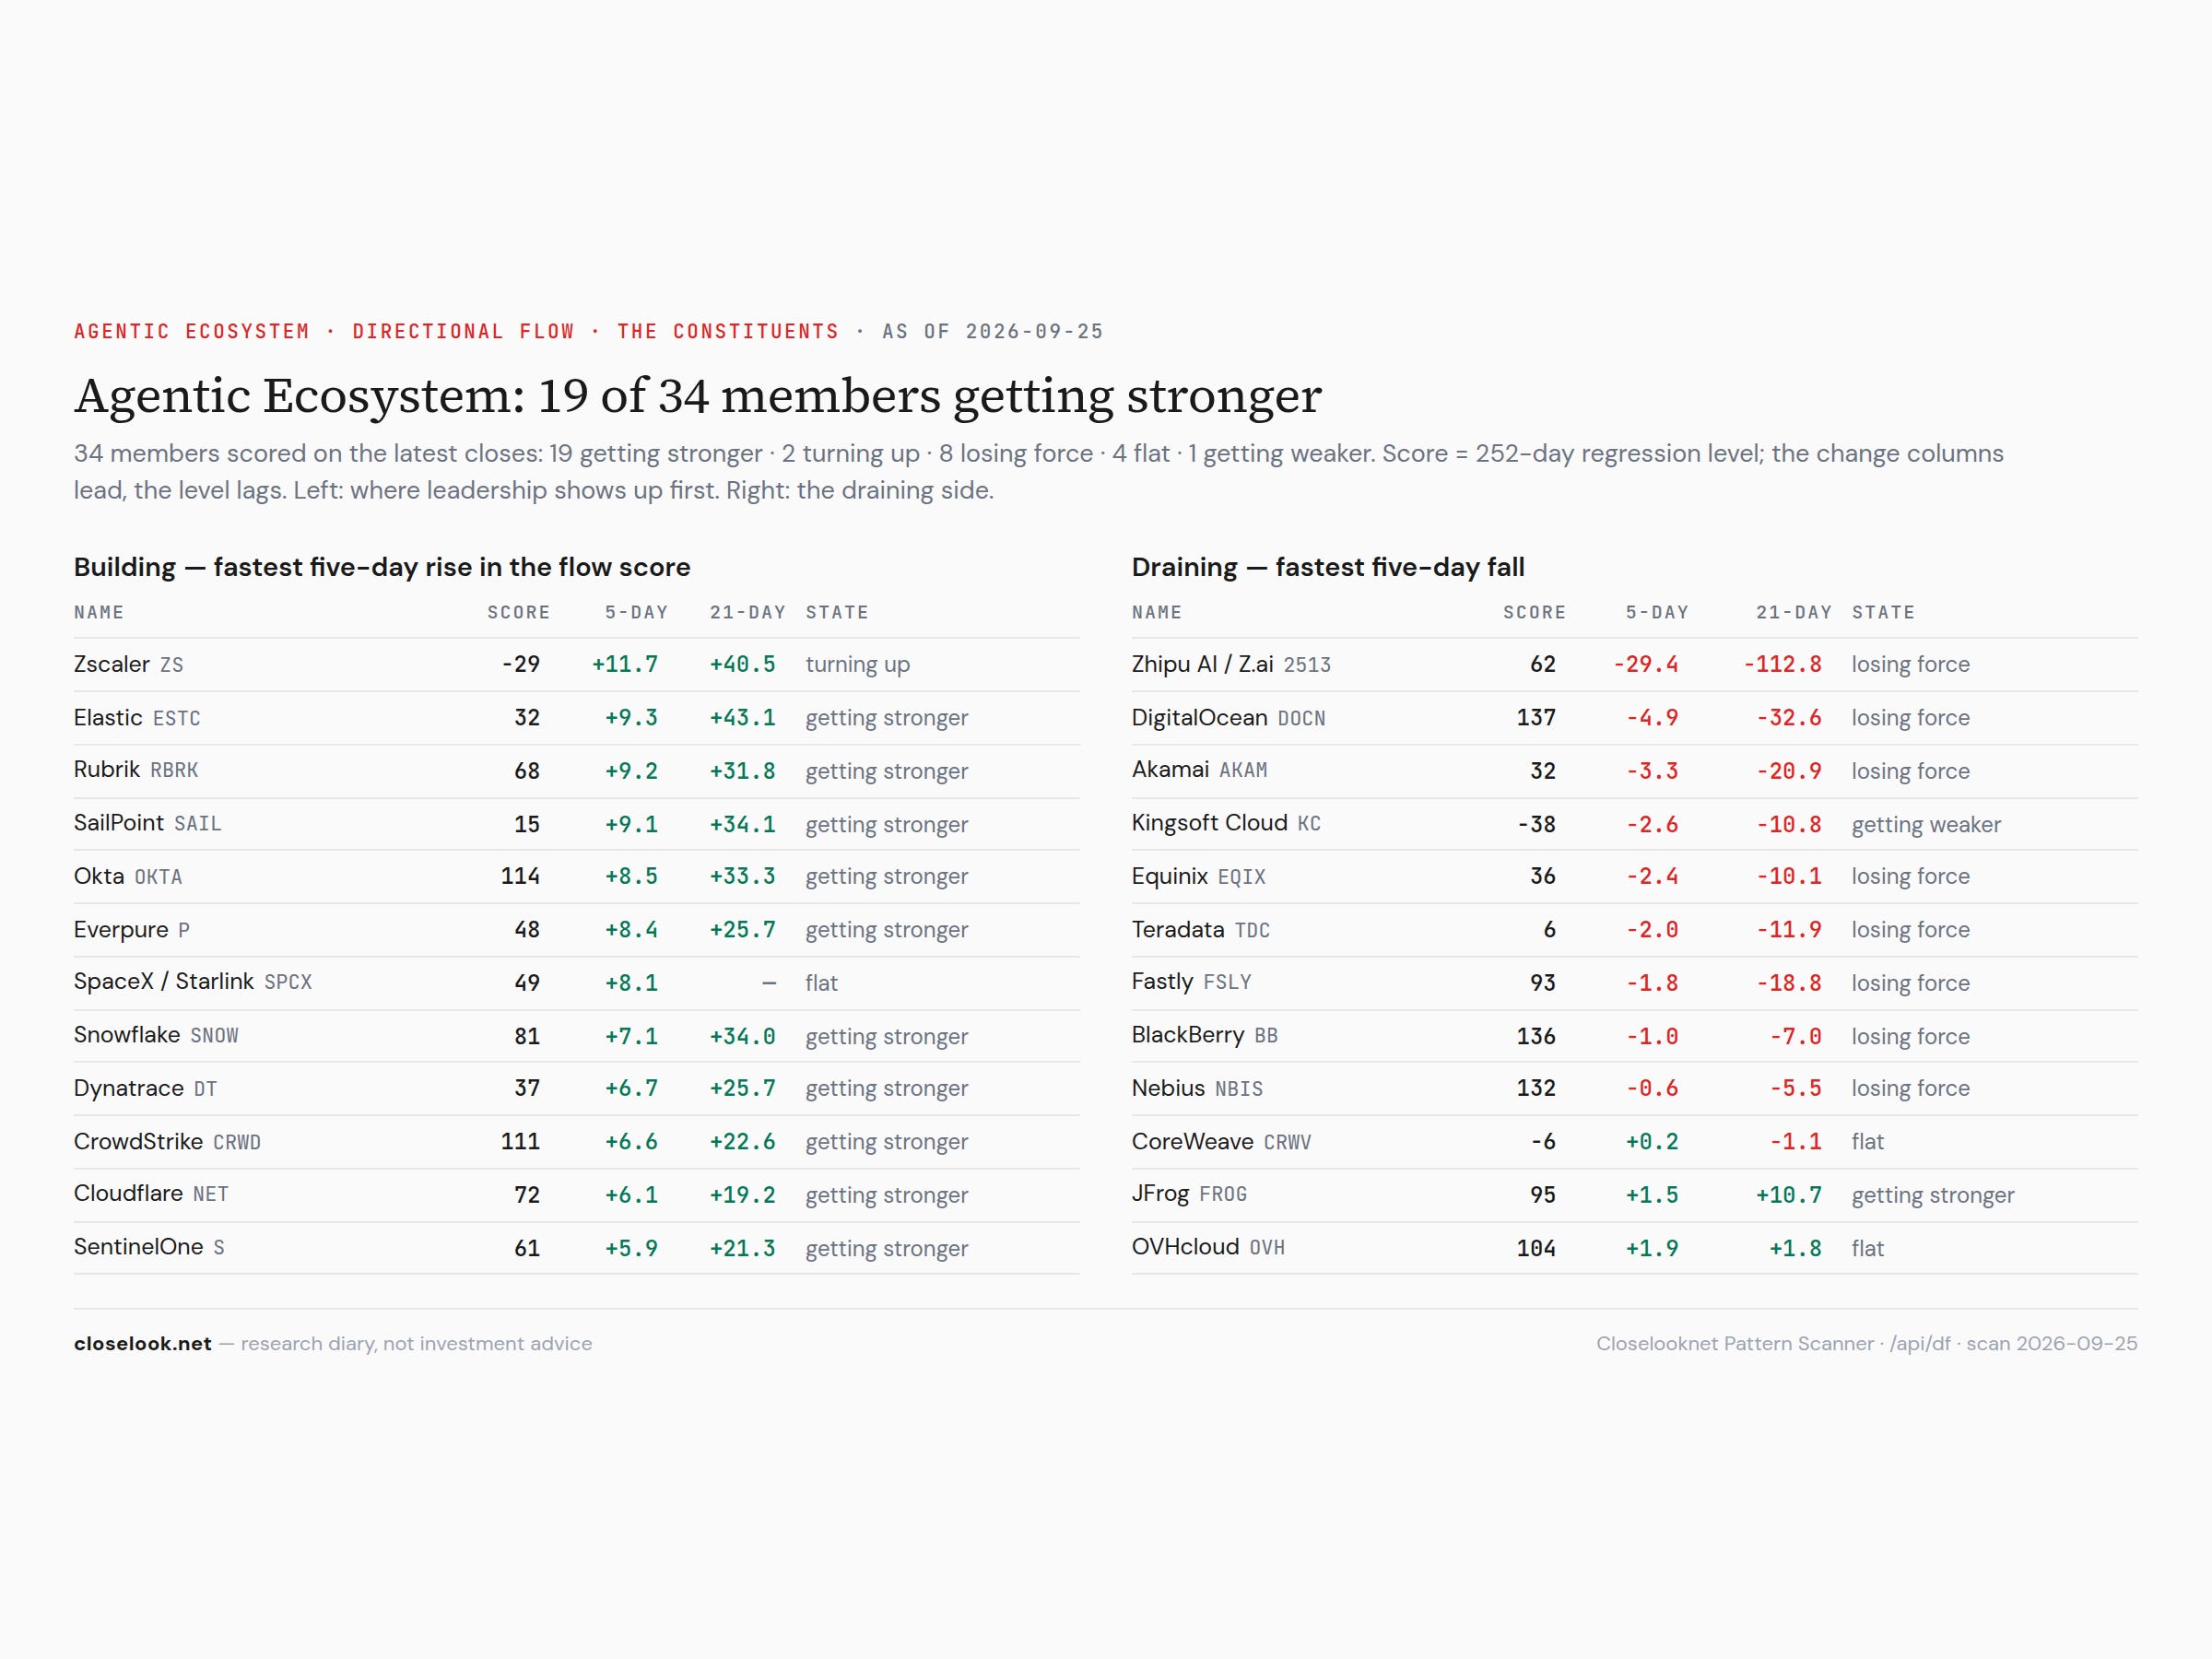
The flow laid over it — the opposite of Rubin. 19 of 34 members are accelerating up, 8 losing force, 2 reversing up, 1 accelerating down. The runner’s flow is building while the builder’s fades. Strongest absolute: DigitalOcean 137, BlackBerry 136, Nebius 132, Fortinet 120, Palo Alto 120, Okta 114. Fastest risers: Zscaler +11.7 (from −29), Elastic +9.3, Rubrik +9.2, SailPoint +9.1, Okta +8.5, Everpure +8.4. Drainers: Zhipu −29.4, DigitalOcean −4.9, Akamai −3.3. The security and governance names lead both the price month and the flow — the one sector in the family where the two agree most.
Agentic Winners 40 — applications
The index: −0.08% on the week to 909.84, −5.72% on the month, −7.0% on the year, 9.8% under its January high. 17 of 40 members rose, median −0.90%.
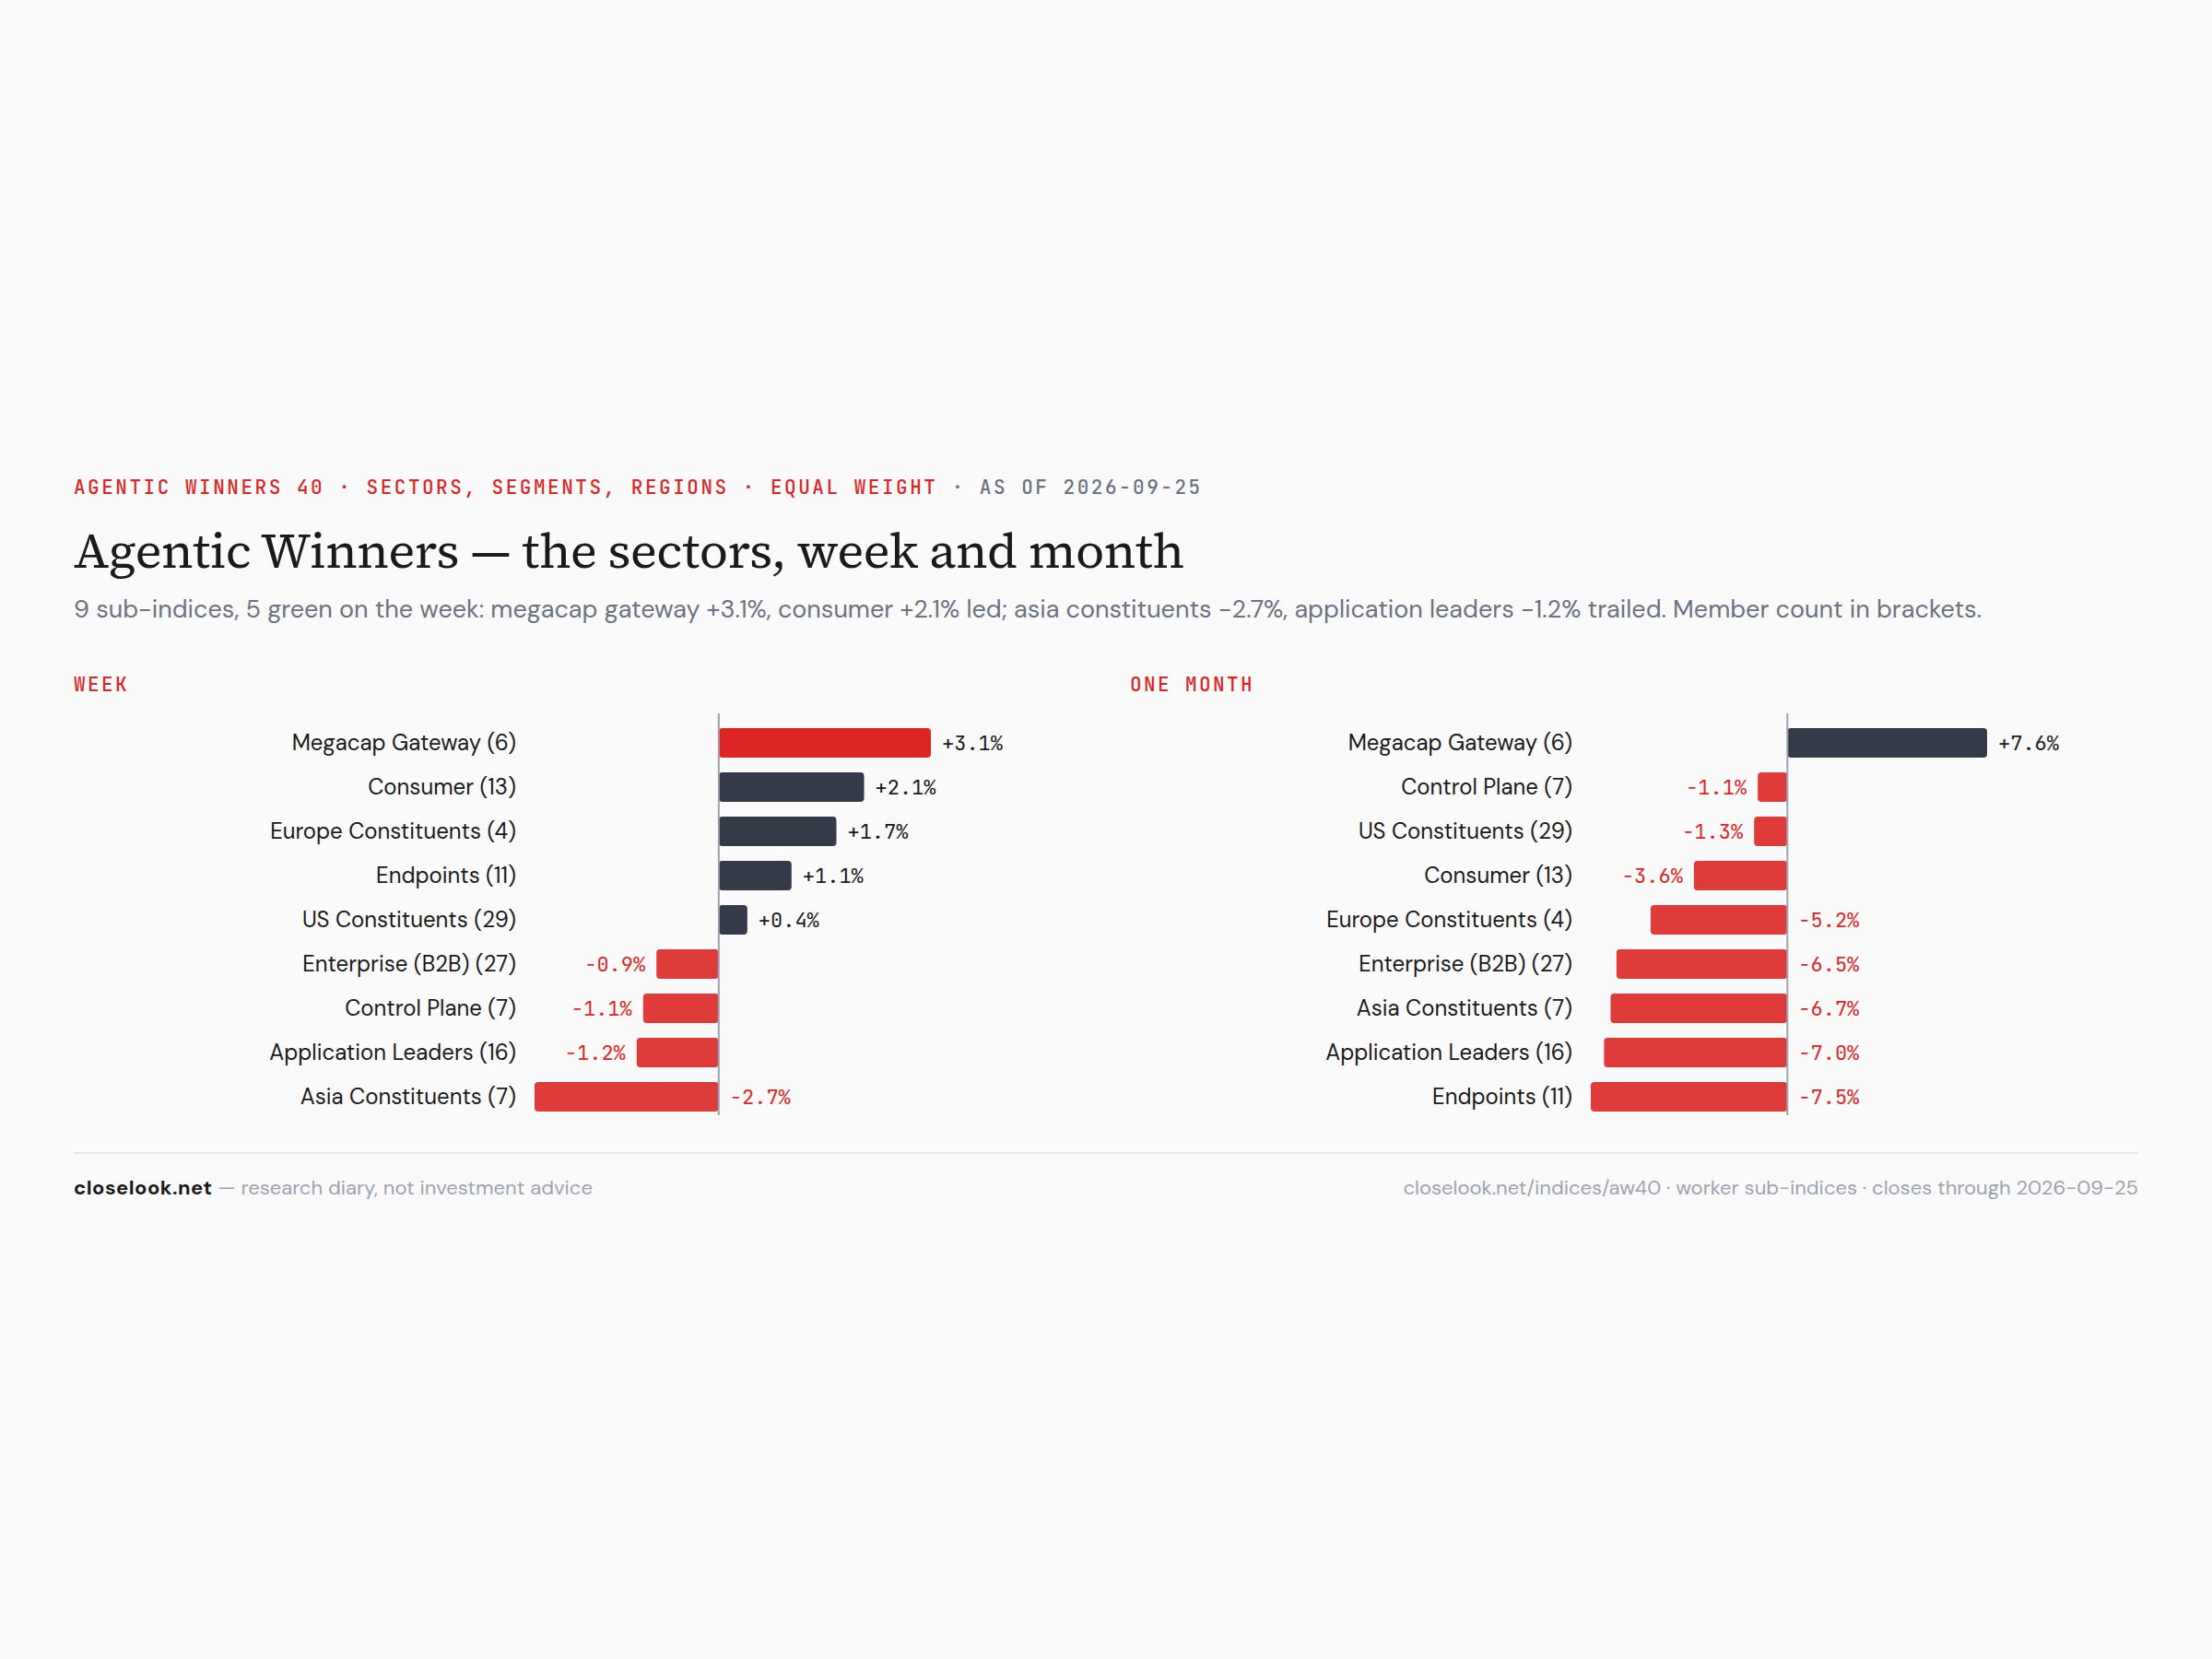
The sectors, three windows. Week — best: the megacap gateway +3.1%, consumer +2.1%, Europe’s constituents +1.7%, endpoints +1.1%. Worst: Asia’s constituents −2.7%, application leaders −1.2%, the control plane −1.1%, the enterprise layer −0.9%. Month: the megacap gateway +7.6% — every other sector red, from −1.1% (control plane) to −7.5% (endpoints). Year: the megacap gateway +16.3% — every other sector red, endpoints −20.0% and consumer −14.3% the worst.
The stocks, three windows. Week — best: Meta +12.9%, Shopify +10.7%, Tempus +9.2%, Veeva +7.9%, Palantir +6.8%, Siemens +5.1%. Worst: Intuit −9.0%, Oracle −7.1%, UiPath −6.9%, freee −6.6%, Money Forward −6.1%, Adobe −5.4%. Month — best: Meta +30.5%, Tempus +24.1%, Veeva +14.6%, Salesforce +13.8%, Atlassian +11.4%. Worst: UiPath −25.7%, Intuit −20.3%, Toast −17.2%, Sea −16.4%, Adobe −13.9%, Netflix −12.7%. Year: Intuit −58%, Adobe −33%, Oracle −30%, UiPath −24% at the bottom; Atlassian +16%, Meta +14% near the top.
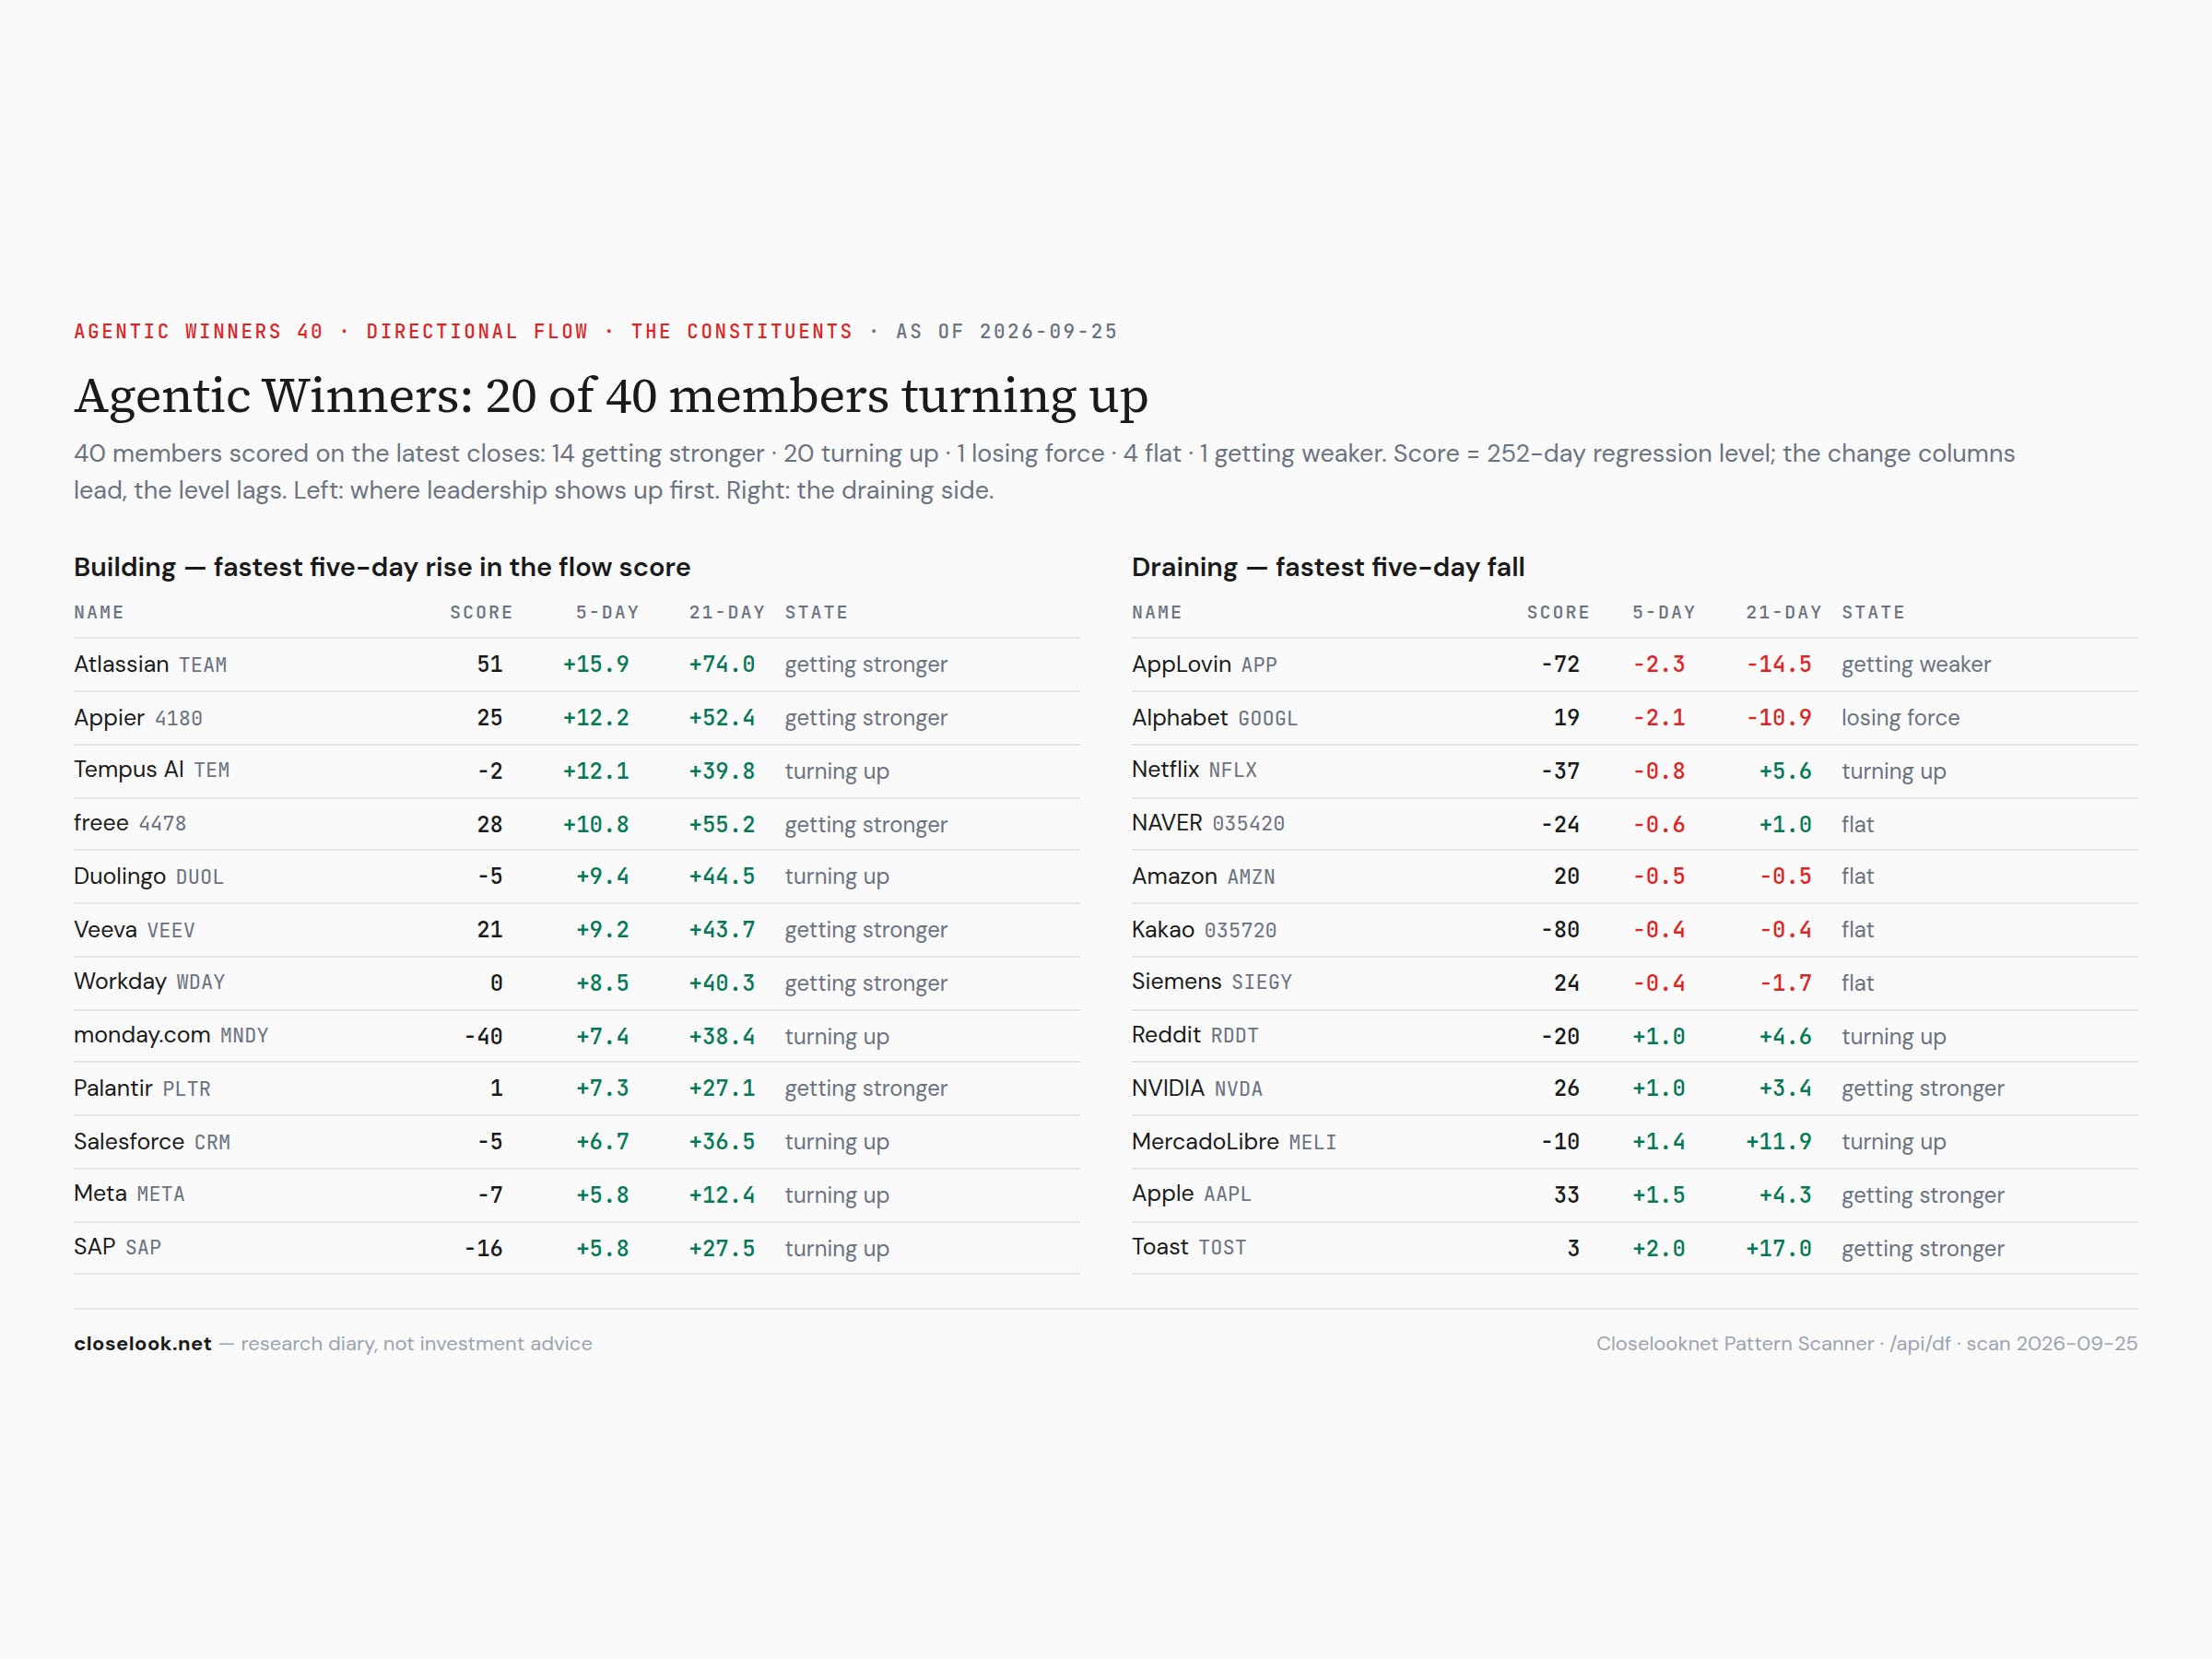
The flow laid over it — building from low levels. 20 of 40 members are reversing up and 14 accelerating up; only one is losing force and one accelerating down. But the absolute scores are low: the strongest are Money Forward 58, Atlassian 51, ServiceNow 45, Apple 33; the weakest CoStar −106, Intuit −88, Kakao −80, Kingdee −79, AppLovin −72. The fastest risers: Atlassian +15.9, Appier +12.2, Tempus +12.1, freee +10.8, Duolingo +9.4, Veeva +9.2. The applications index is the mirror of Rubin: the price is flat and falling on the month, and the flow is turning up almost everywhere. Last spring the index that bottomed first went on to lead; this autumn the question is whether the one that turns its flow first does.
The three indices, read as one sentence. The builder rose most while its flow faded; the runner rose while its flow built; the applications stood still while their flow turned. On price, capex leads the week, the month and the year. On flow, the order is reversed.
3 · The AI Board — the stack, instrument by instrument
The Handoff Board — the money went back up to the designers. Design over physical +5.29% on the week; execution over substrate +5.47%. Every downstream ratio fell: use over build −4.88%, verification over design −4.87%, operators over suppliers −5.20%, trust over execution −3.53%. Since the June 30 base, use over build is still the strongest ratio at +43%.
