

The Nasdaq 100 made a record close, global tech took out its June high, and Taiwan and Japan’s broad fund closed at records — while every mainland European market on the board fell, France, Spain and Austria by four to five percent, Switzerland and Britain with them, and India slid to its lowest close in a year. The dollar made its highest close of 2026 and the euro its lowest; the long bond made a new low every day of the week, and gold broke its first support. The world ex-US index lost its line again, and its lead over America for the year is down to six tenths of a point. America won a fourth week. This letter’s read for the fourth quarter — stay home, because the AI trade lives in America and Asia — and TSMC’s September sales next week are the first test of it.
1 · This Week’s Action
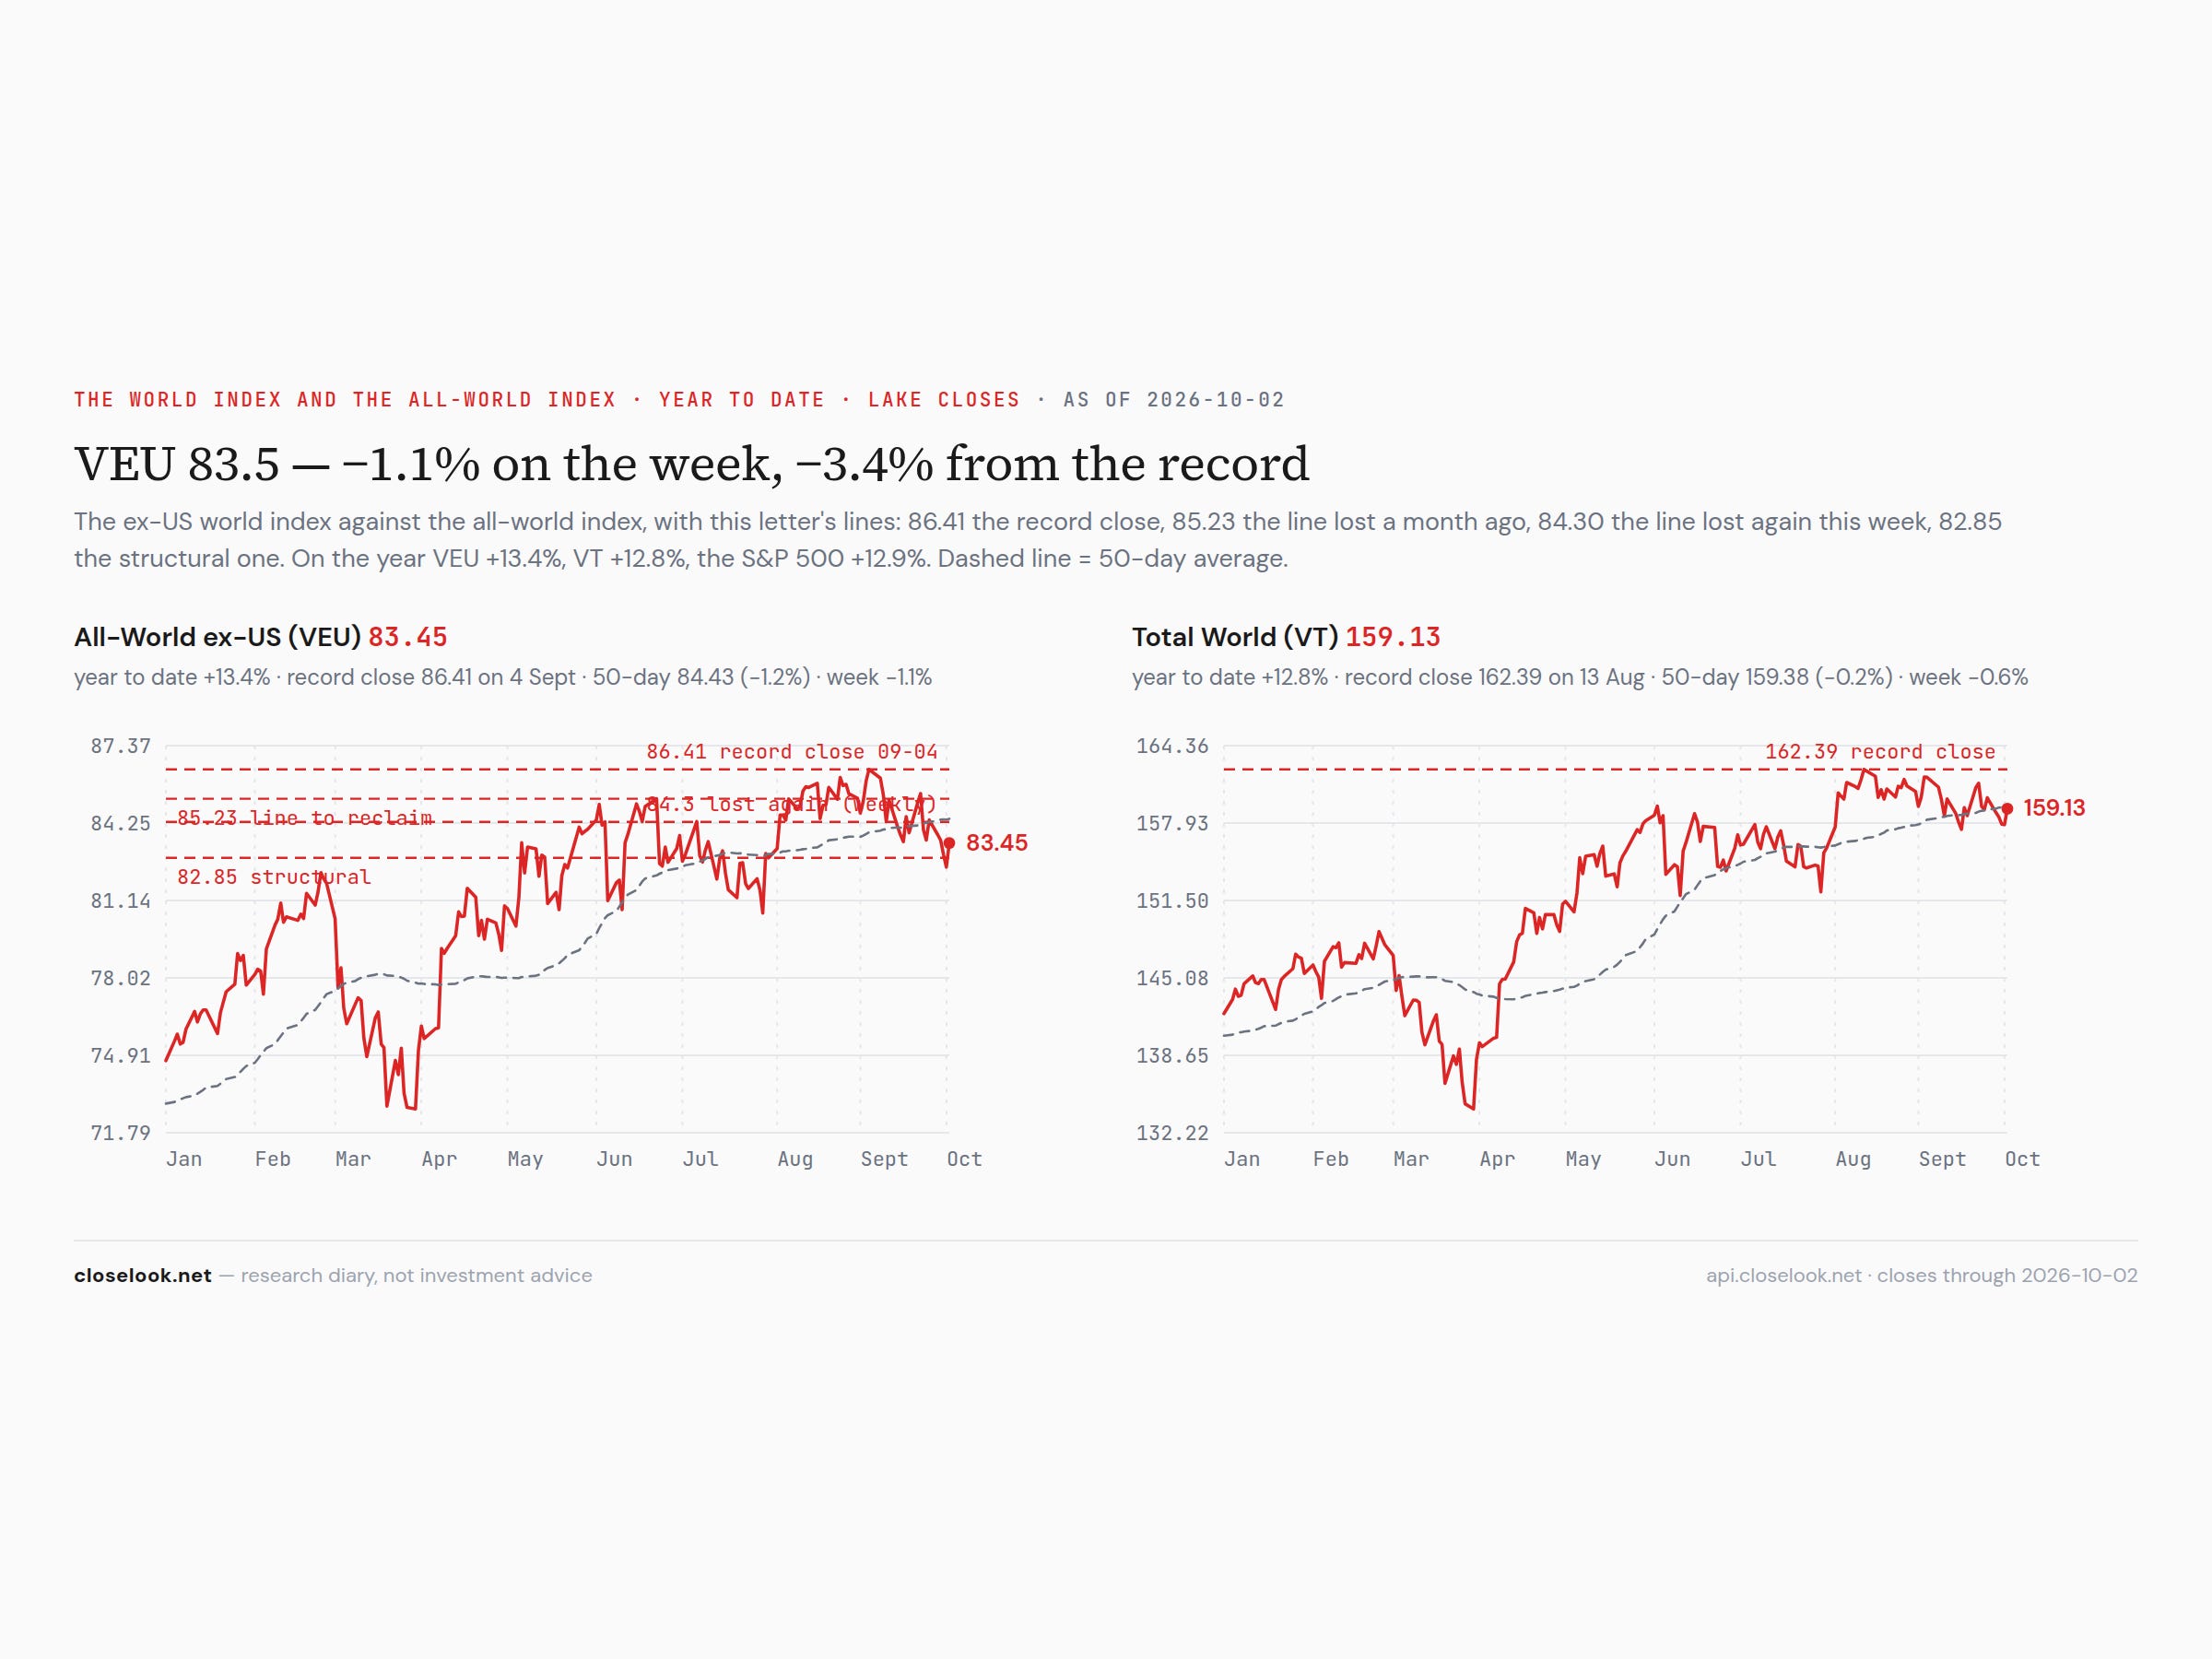
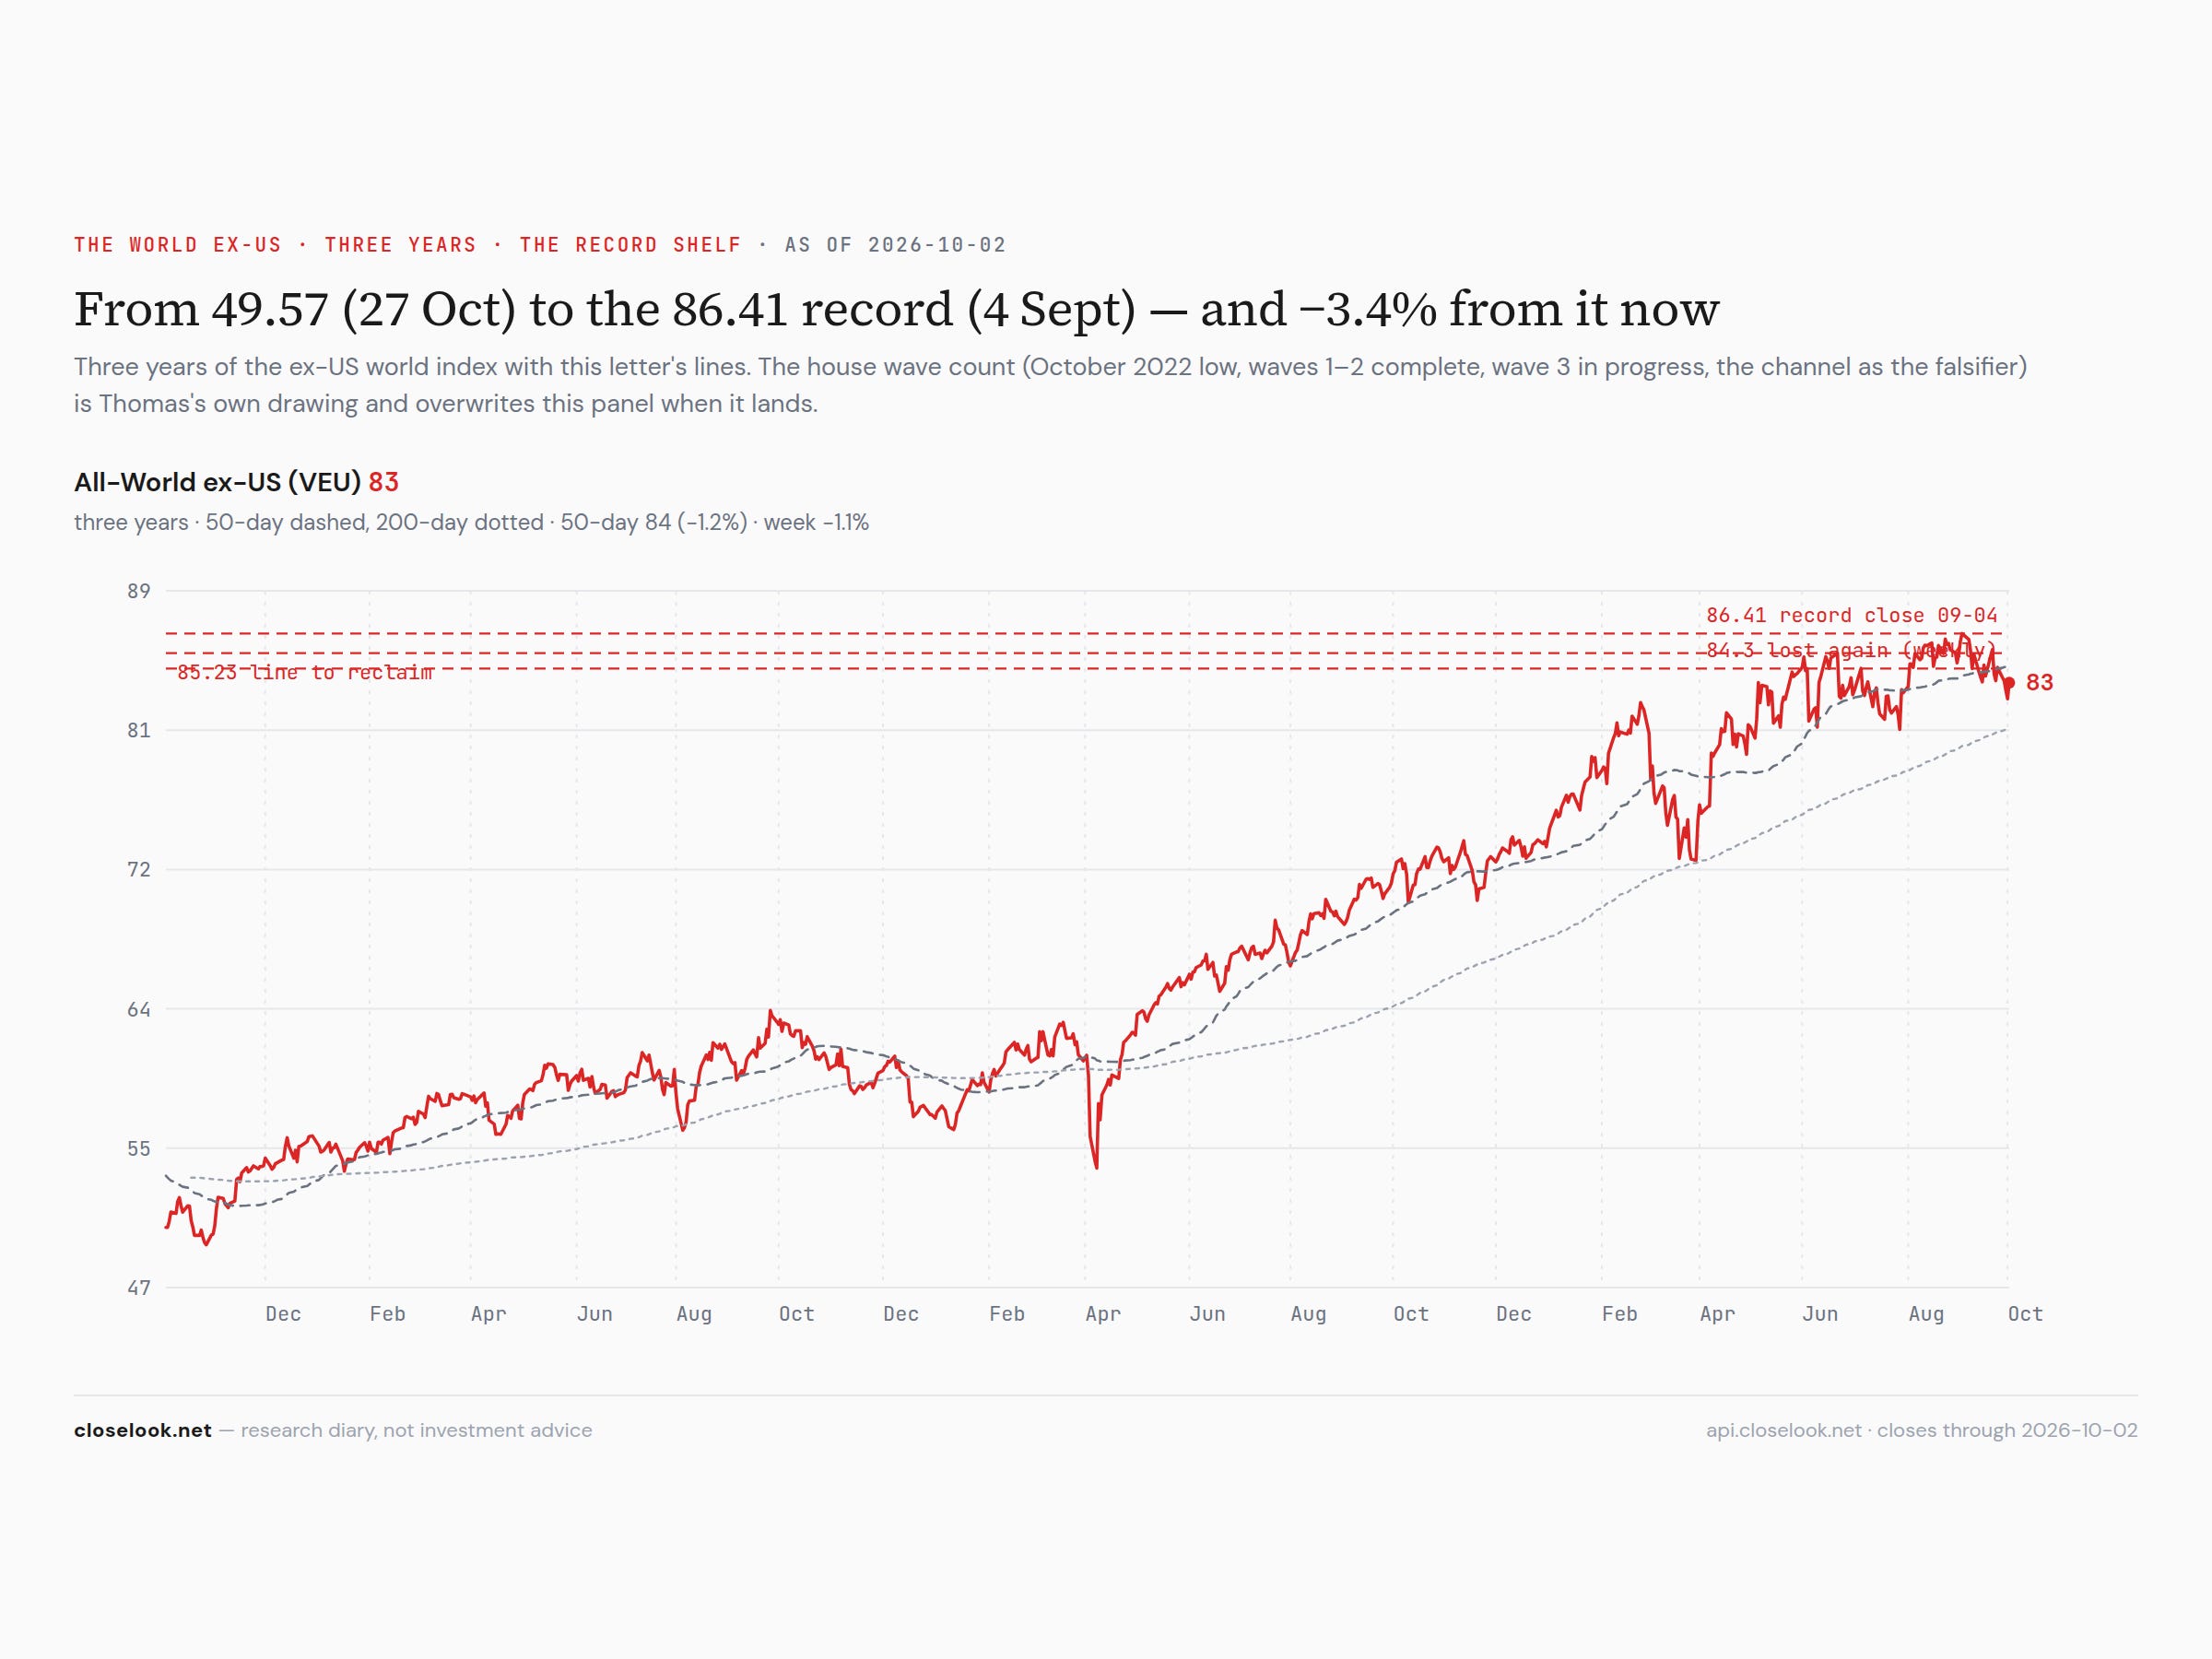
The global view. The ex-US world index closed the week at 83.45, down 1.10% — back under 84.30, the line it took back a week ago by eight cents. The path: Monday 83.77, Tuesday 83.56, Wednesday 82.97, Thursday 82.48 — a daily close under the 82.85 structural line, the first since July — and Friday 83.45, back above it for the weekly close. The index sits 3.4% under its September 4 record of 86.41. The all-world index closed 159.13, down 0.56%, 2.0% under its August high. The S&P 500 fund slipped 0.22%, 1.1% under its August high — but the Nasdaq 100 rose 1.01% to 30,916, a record close on Friday, and the fund that tracks it closed at a record too.
The year’s order is close to turning. VEU +13.4% for 2026, the S&P fund +12.9%, VT +12.8% — the ex-US lead over America is 0.6 points, from 1.6 last week, 2.3 the week before, 3.7 and 4.5 before that. Four consecutive stay-home weeks. The Nasdaq 100 fund, the part of America that carries the AI trade, is +22.0% on the year. The house cointegration monitor still lists the VEU/SPY pair as breaking.
Three speeds — the week in one picture. The world did not move as one market this week; it moved at three speeds, and the dividing line was the AI trade. America’s technology at records: the Nasdaq 100 at a record close, the US tech sector fund at a record 199.81 (+1.80%), global tech at a record 151.94 (+2.00%) — through the June high this letter has carried as a line since the summer. Asia’s chip markets ahead: Taiwan’s fund +1.35% to a record close of 116.33, the Taiex at a record 48,476; Korea’s fund +2.51% to 191.88; Japan’s fund +1.01% to a record close of 98.92. Europe and India behind: the Europe fund −2.54%, France −3.69%, Spain −4.72%, Austria −5.18%, Germany −2.27%, Switzerland −2.36%, Britain −2.41%; India −2.80%, with the Sensex at its lowest close in a year on Thursday.
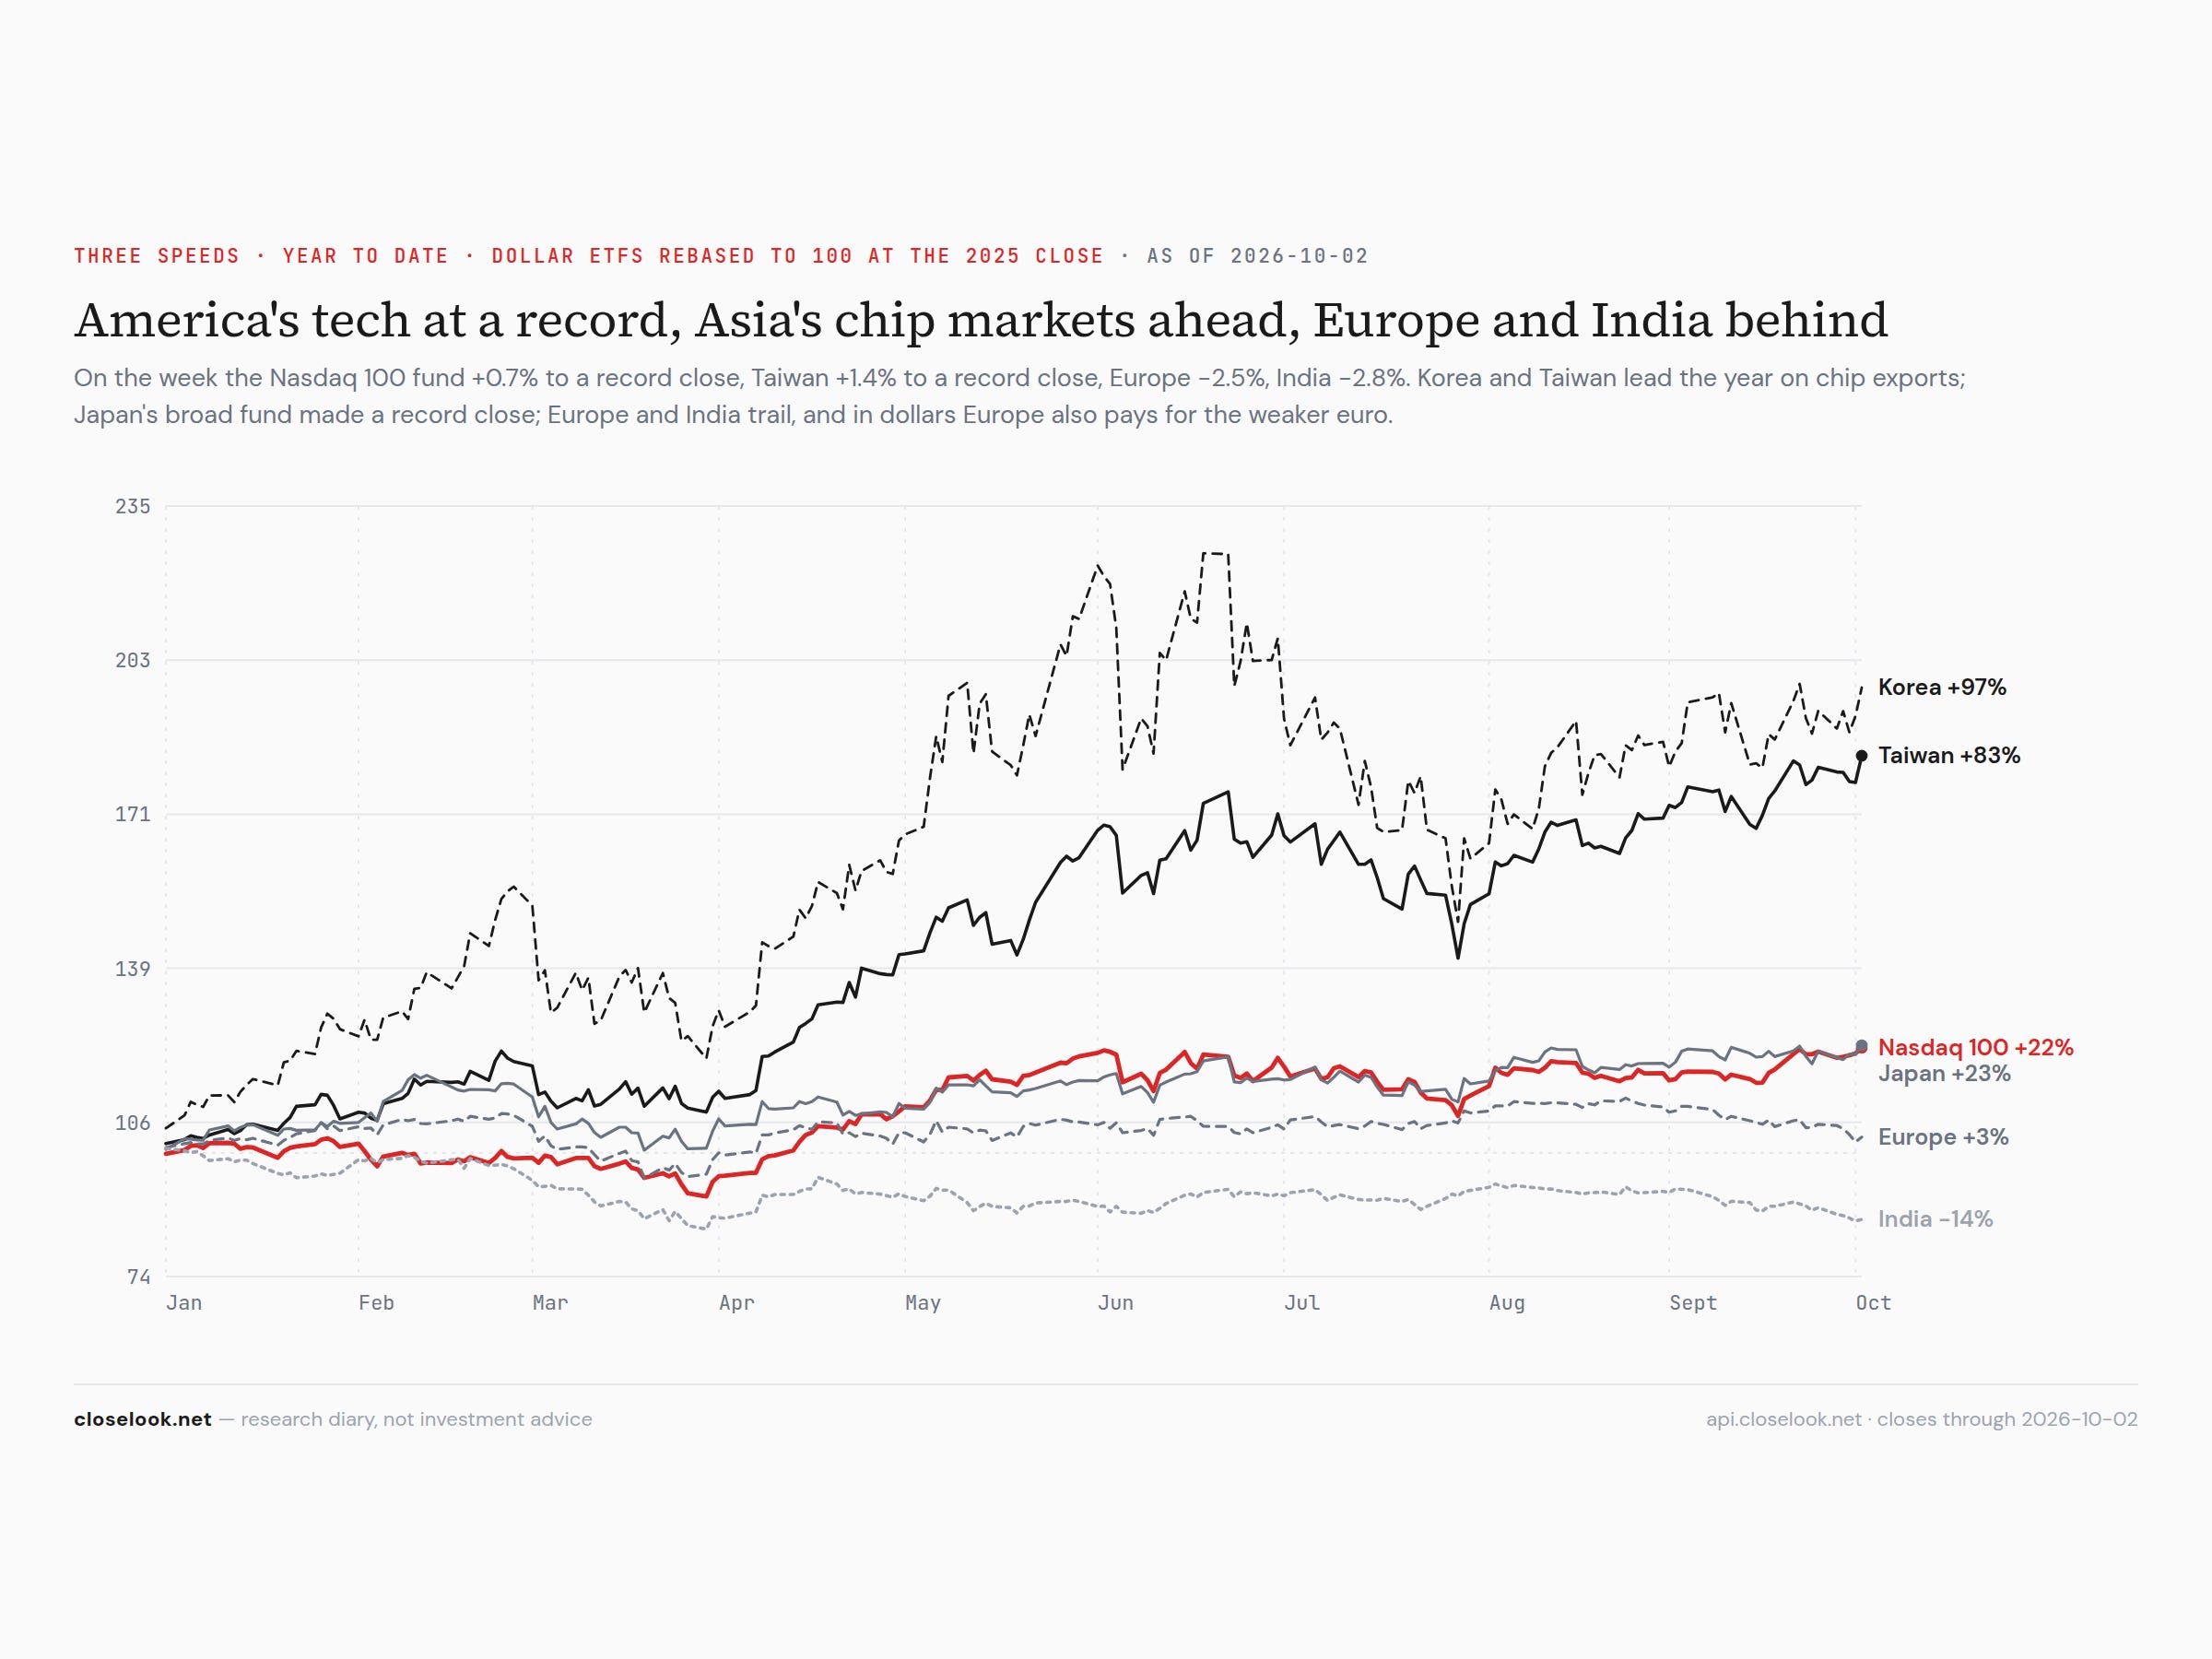
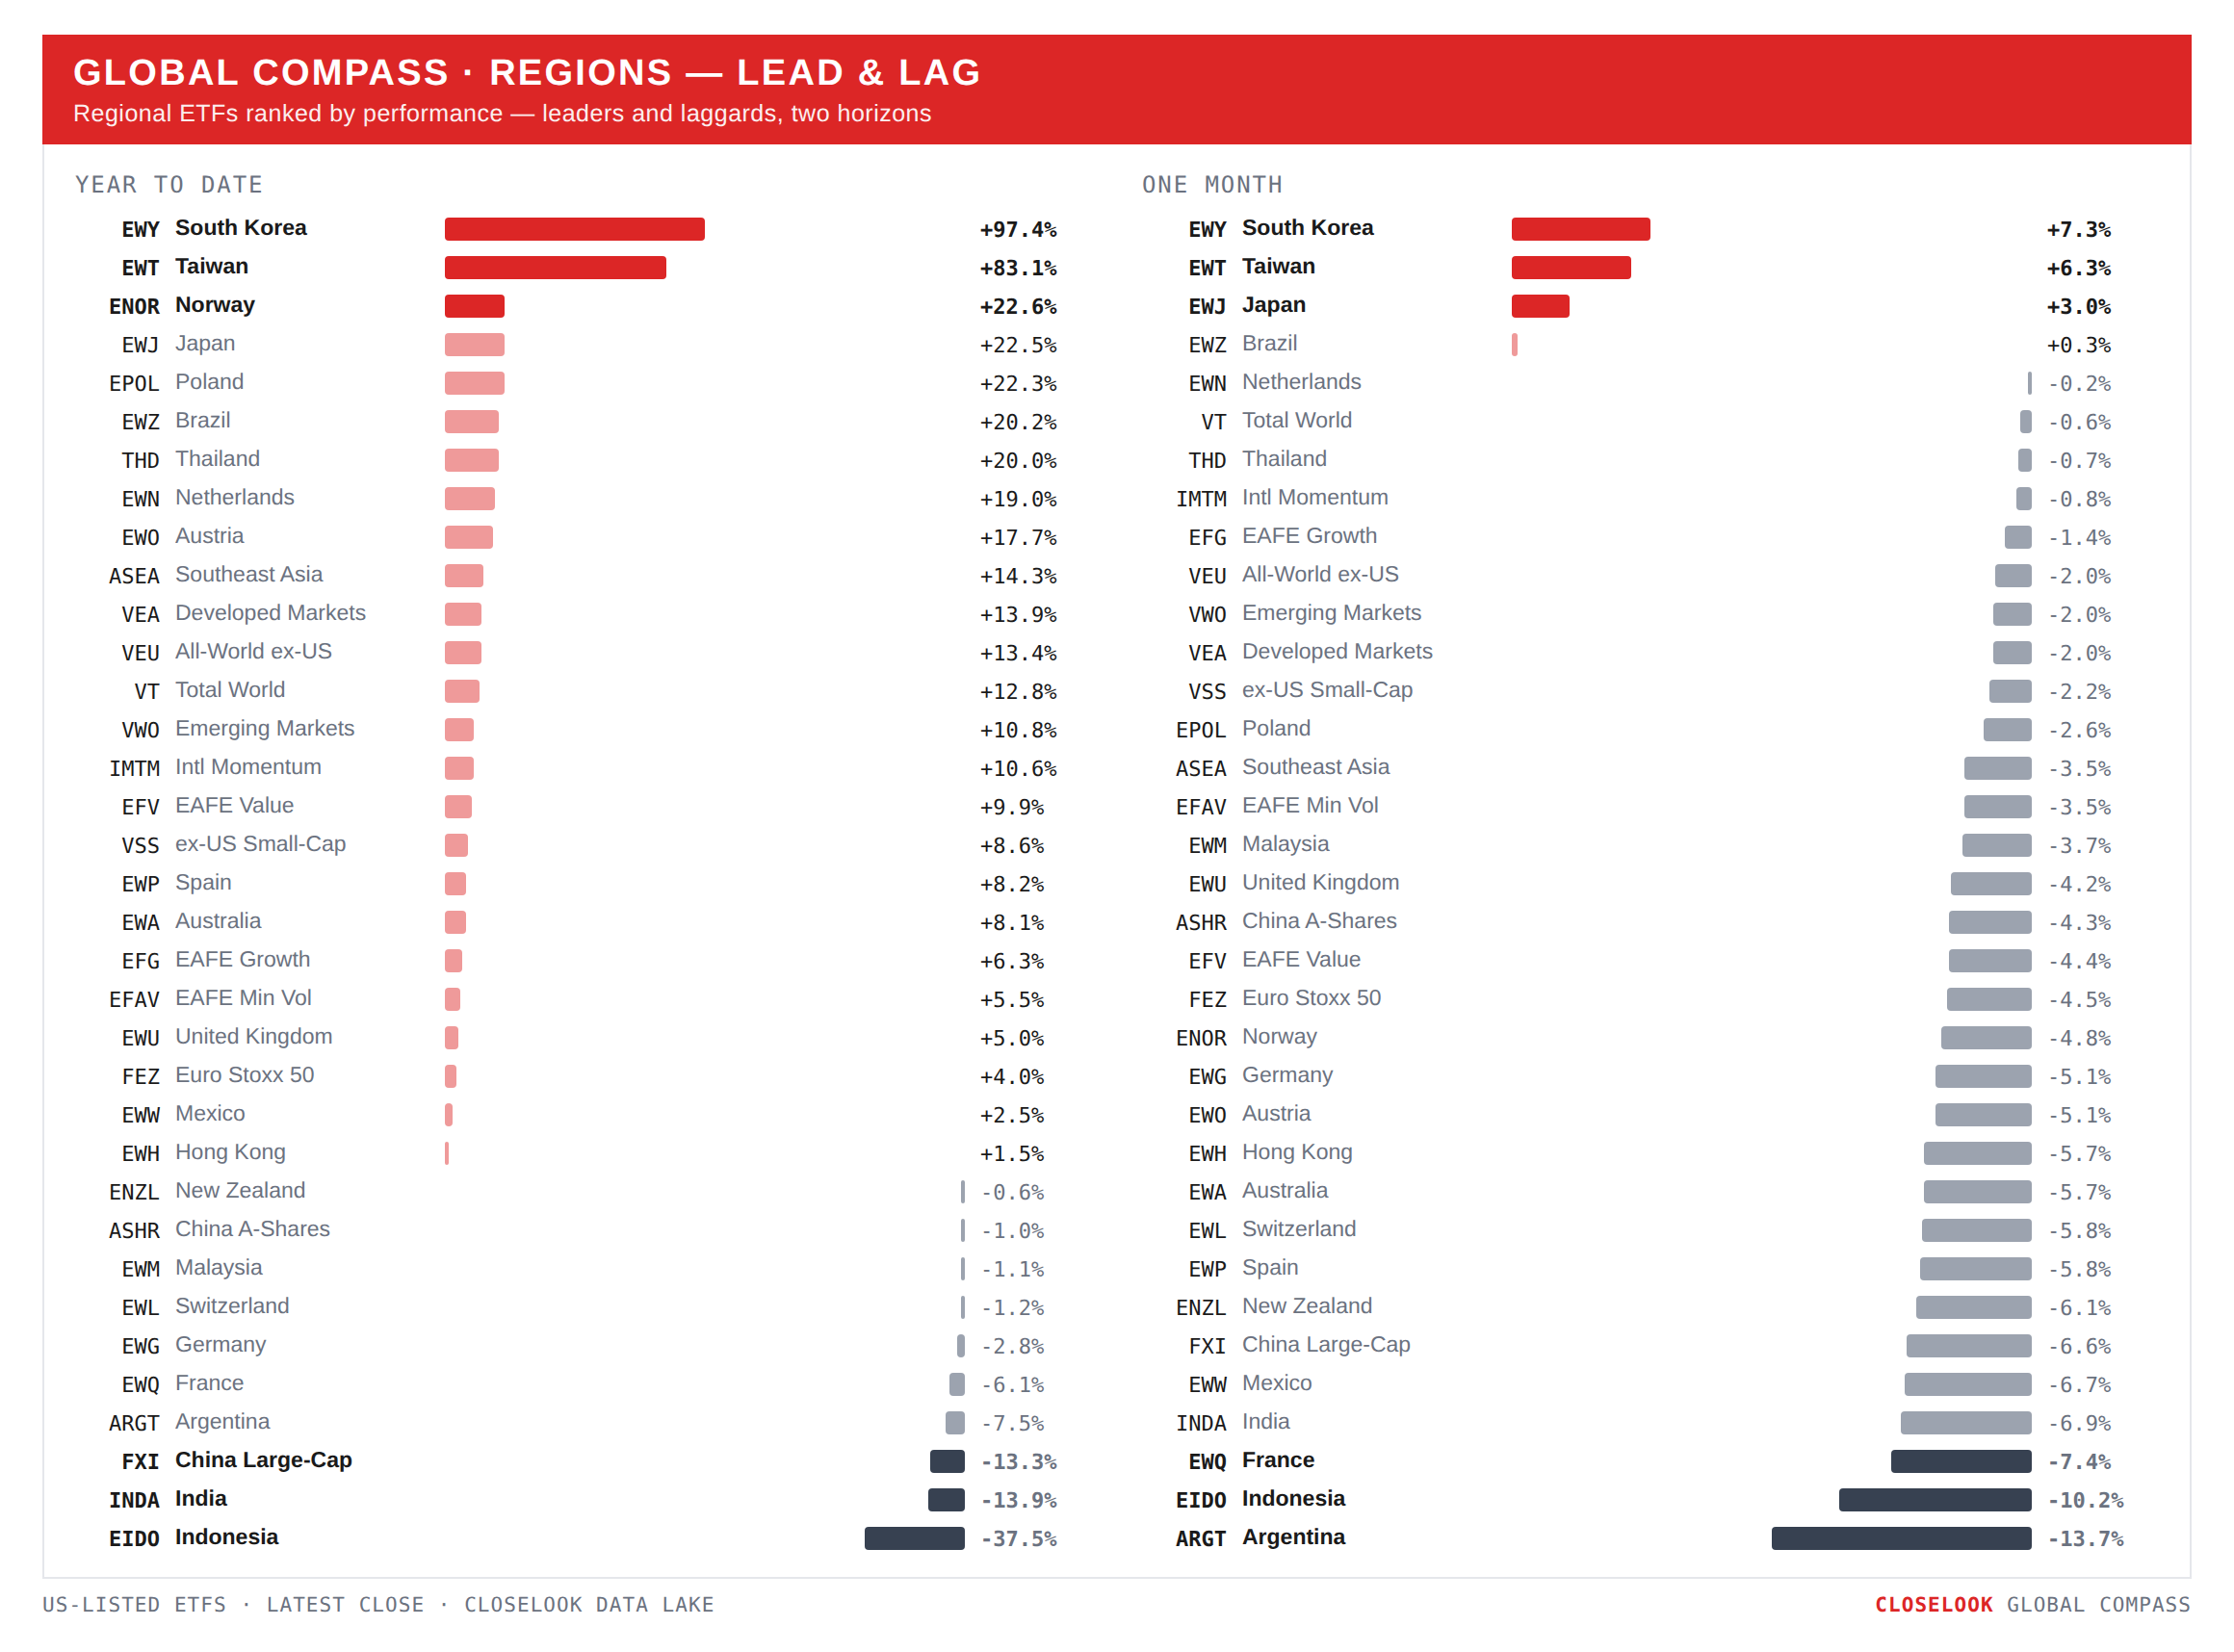
On the year the gap is the whole story: Korea +97%, Taiwan +83%, Japan +23%, the Nasdaq 100 +22% — against Europe +3% and India −14% in dollars. Four of the six legs in that chart carry the AI build-out — the chips, the chip equipment, the platforms that buy them. The two that do not are the two at the bottom.
The dollar — the high of the year, and the euro at its low. The third speed has a currency attached. The dollar fund rose 0.94% and made its highest close of 2026 on Thursday at 28.96; the dollar index closed Friday at 101.92, +0.94%. Against the euro the move was larger: EUR/USD fell 1.22% to 1.1253, after 1.1248 on Thursday — the euro’s lowest close of the year — and is down 4.2% since January. A weaker euro is the European market’s second cost this year: a dollar investor who owns Europe loses on the market and again on the translation, and a euro investor at home holds an asset that buys less of everything priced in dollars, from chips to oil.
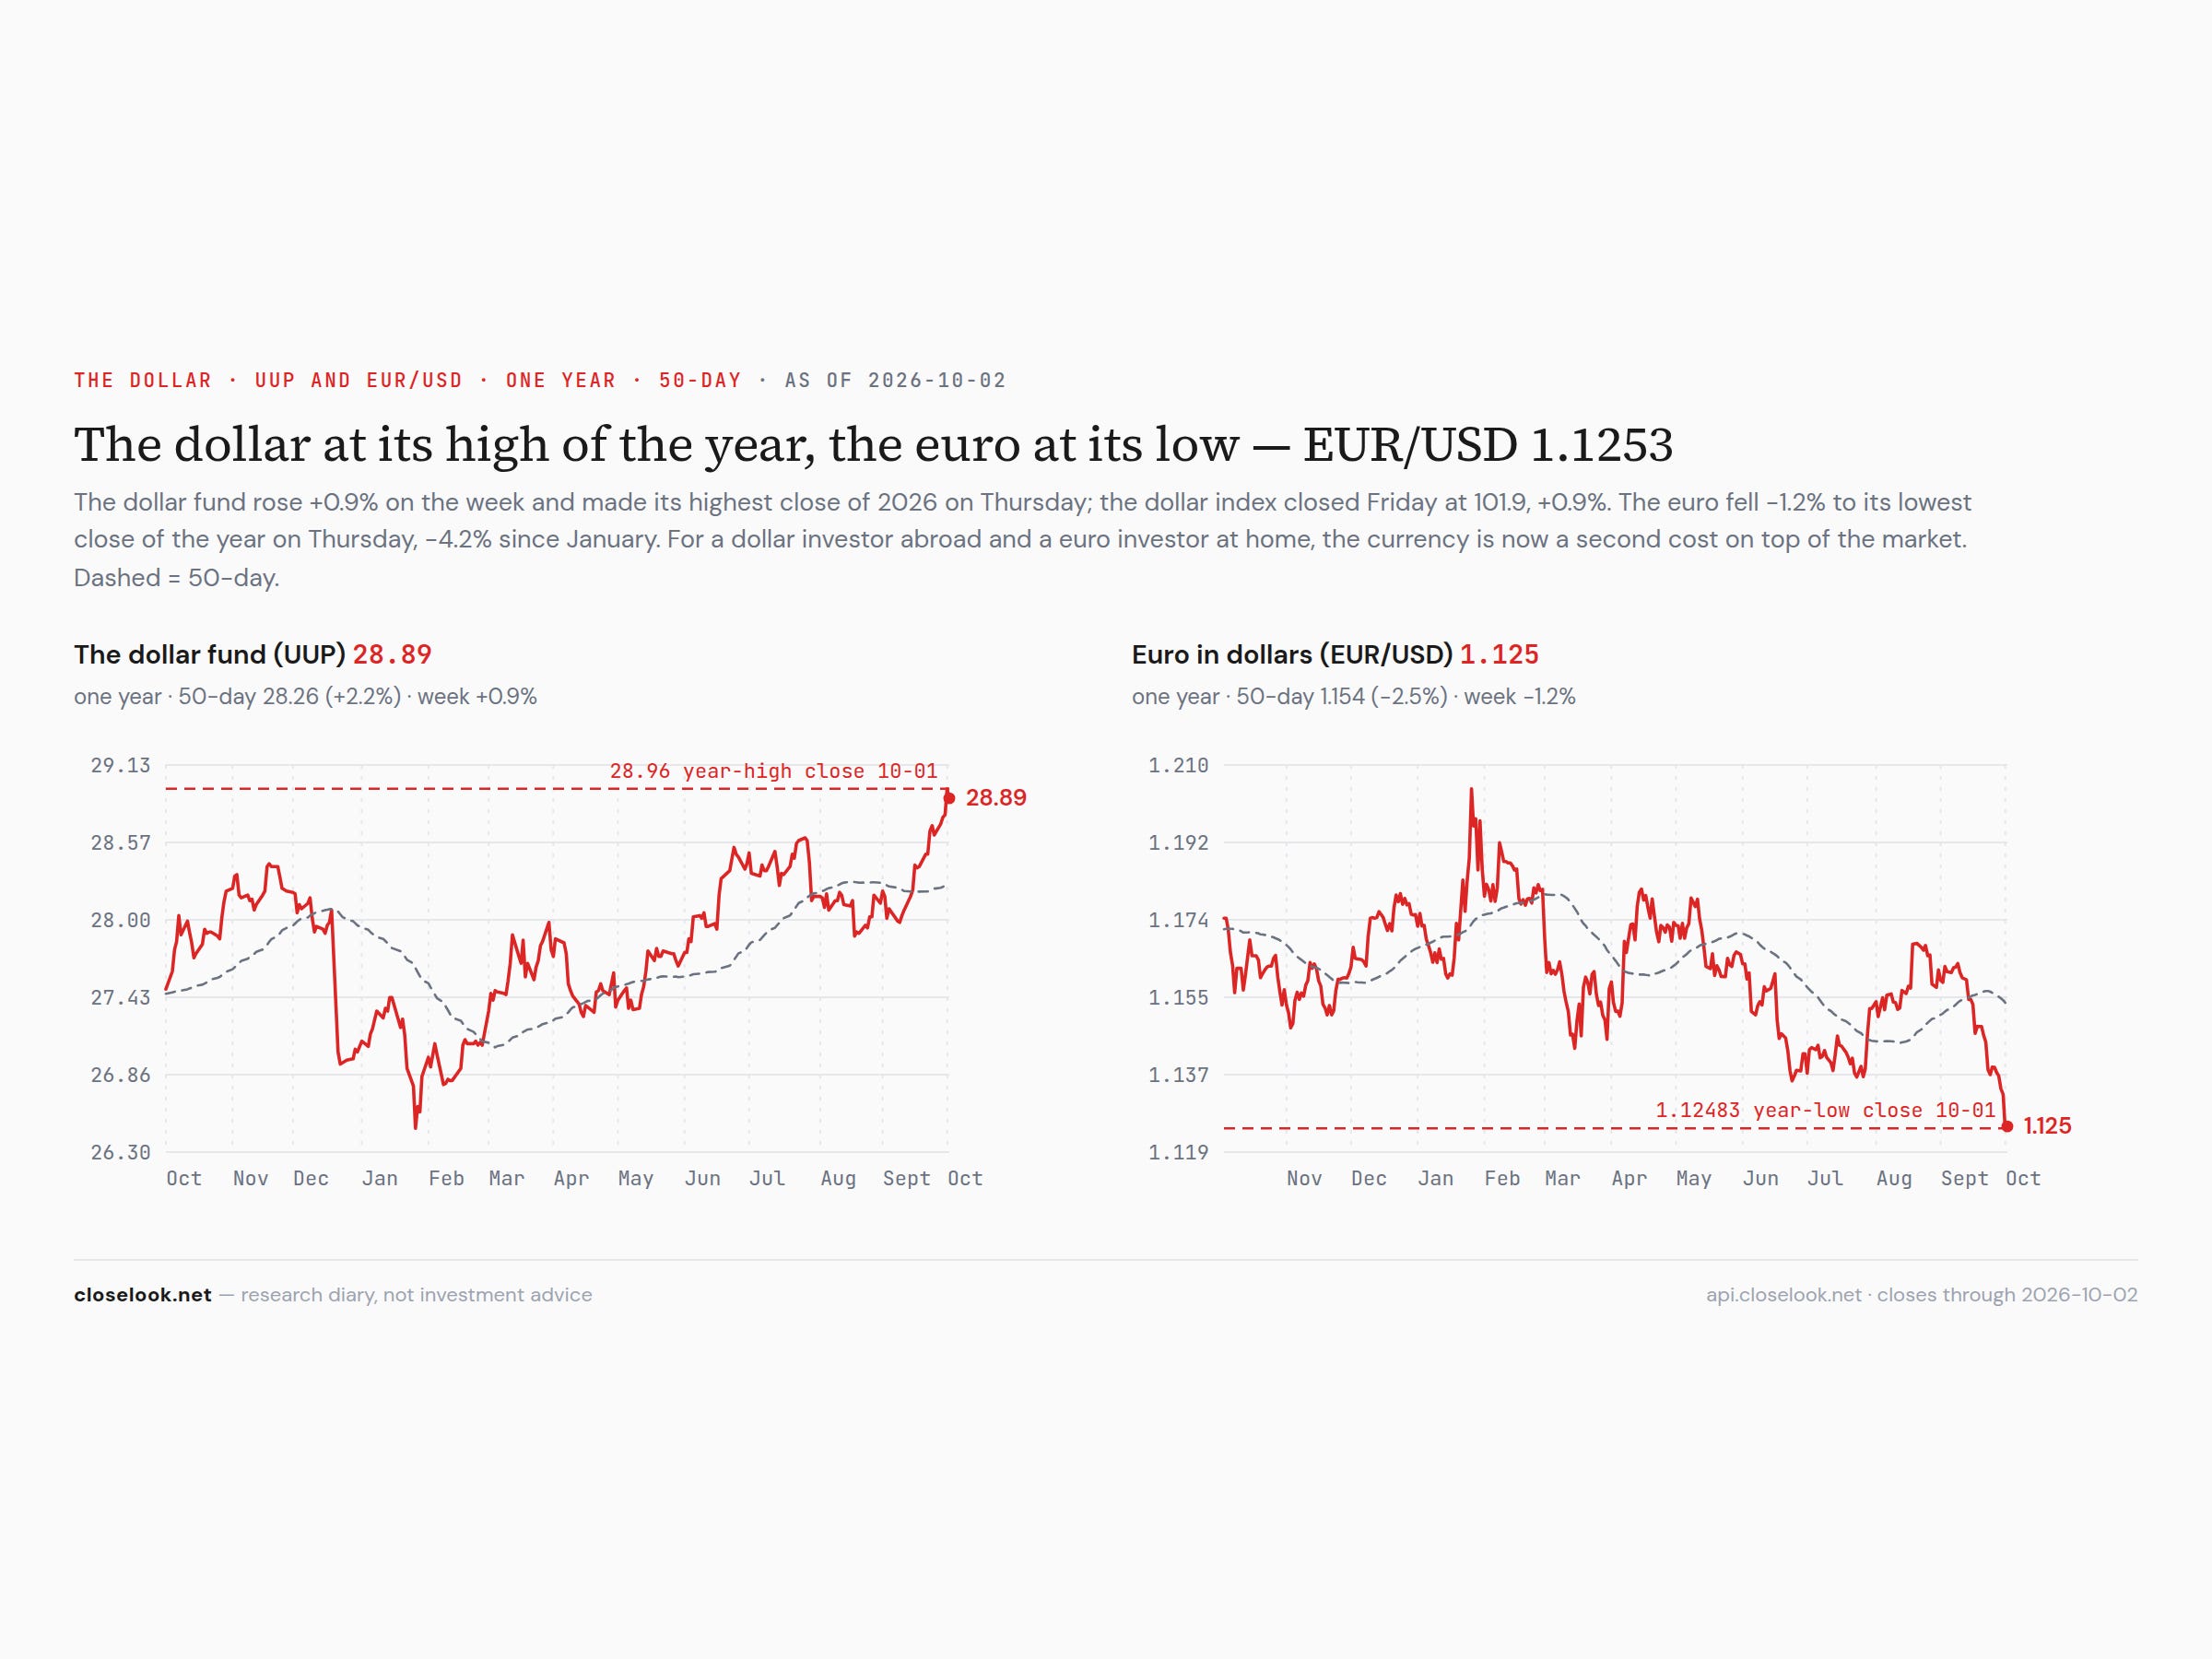
Why the dollar is strong — the same reason the yields are high. America’s yields rise because its economy grows; Europe’s rise because its sovereign credit is weaker and its growth is not there — Friday’s Pulse set the two side by side, country by country. A rate rise for growth draws money in; a rate rise for credit pushes it out. The dollar is where that difference shows up first. This week it showed up in a jobs report that was weak — 29,000 jobs in September, with July and August cut by 60,000 — and a ten-year yield that ended the day higher anyway, at 5.28%, while the euro made its low. When weak American data cannot weaken the dollar, the market is telling you how it ranks the alternatives.
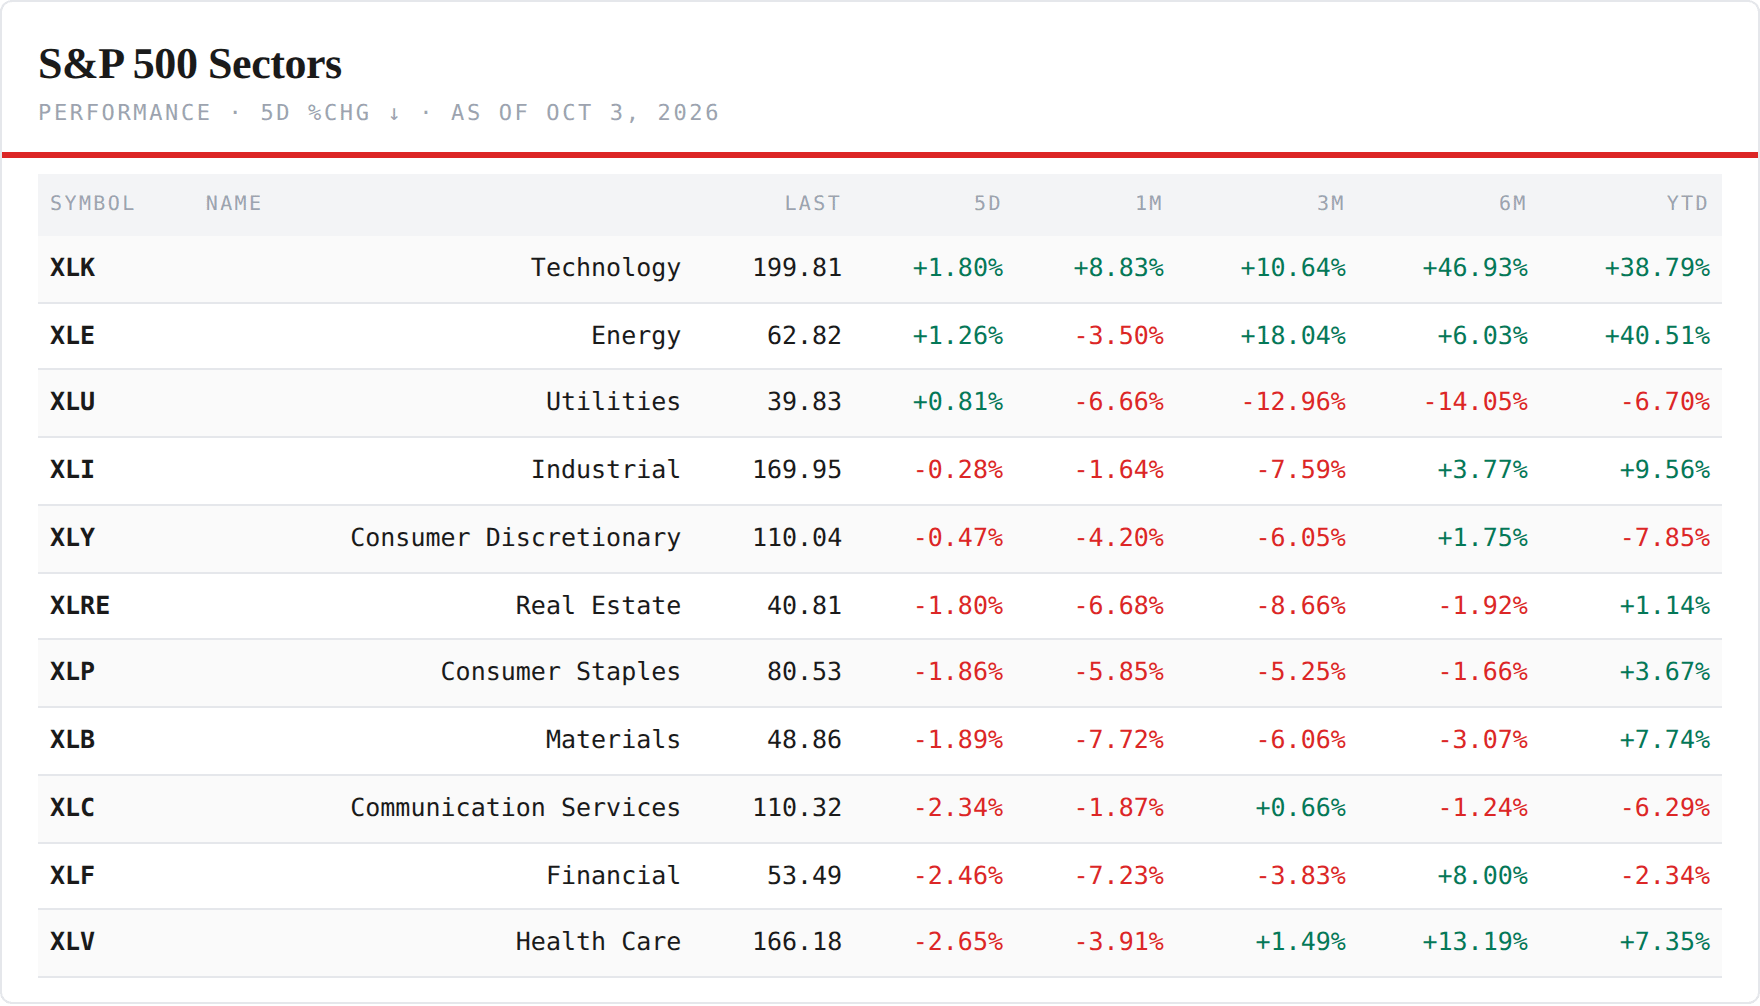
The regional board — five green of thirty-five. The top five: Brazil +3.72%, Korea +2.51%, Taiwan +1.35%, Japan +1.01%, EAFE growth +0.08%. The bottom: Austria −5.18%, Spain −4.72%, Argentina −4.60%, Poland −4.06%, France −3.69%, Hong Kong −3.10%, Mexico −3.07%. Last week twenty-two were green; this week five. The best-to-worst spread widened to 8.90 points from 7.38. A red board that widens is money leaving most places and concentrating in a few — and the few are the same chip corridor as last week, with Brazil the one commodity exception.
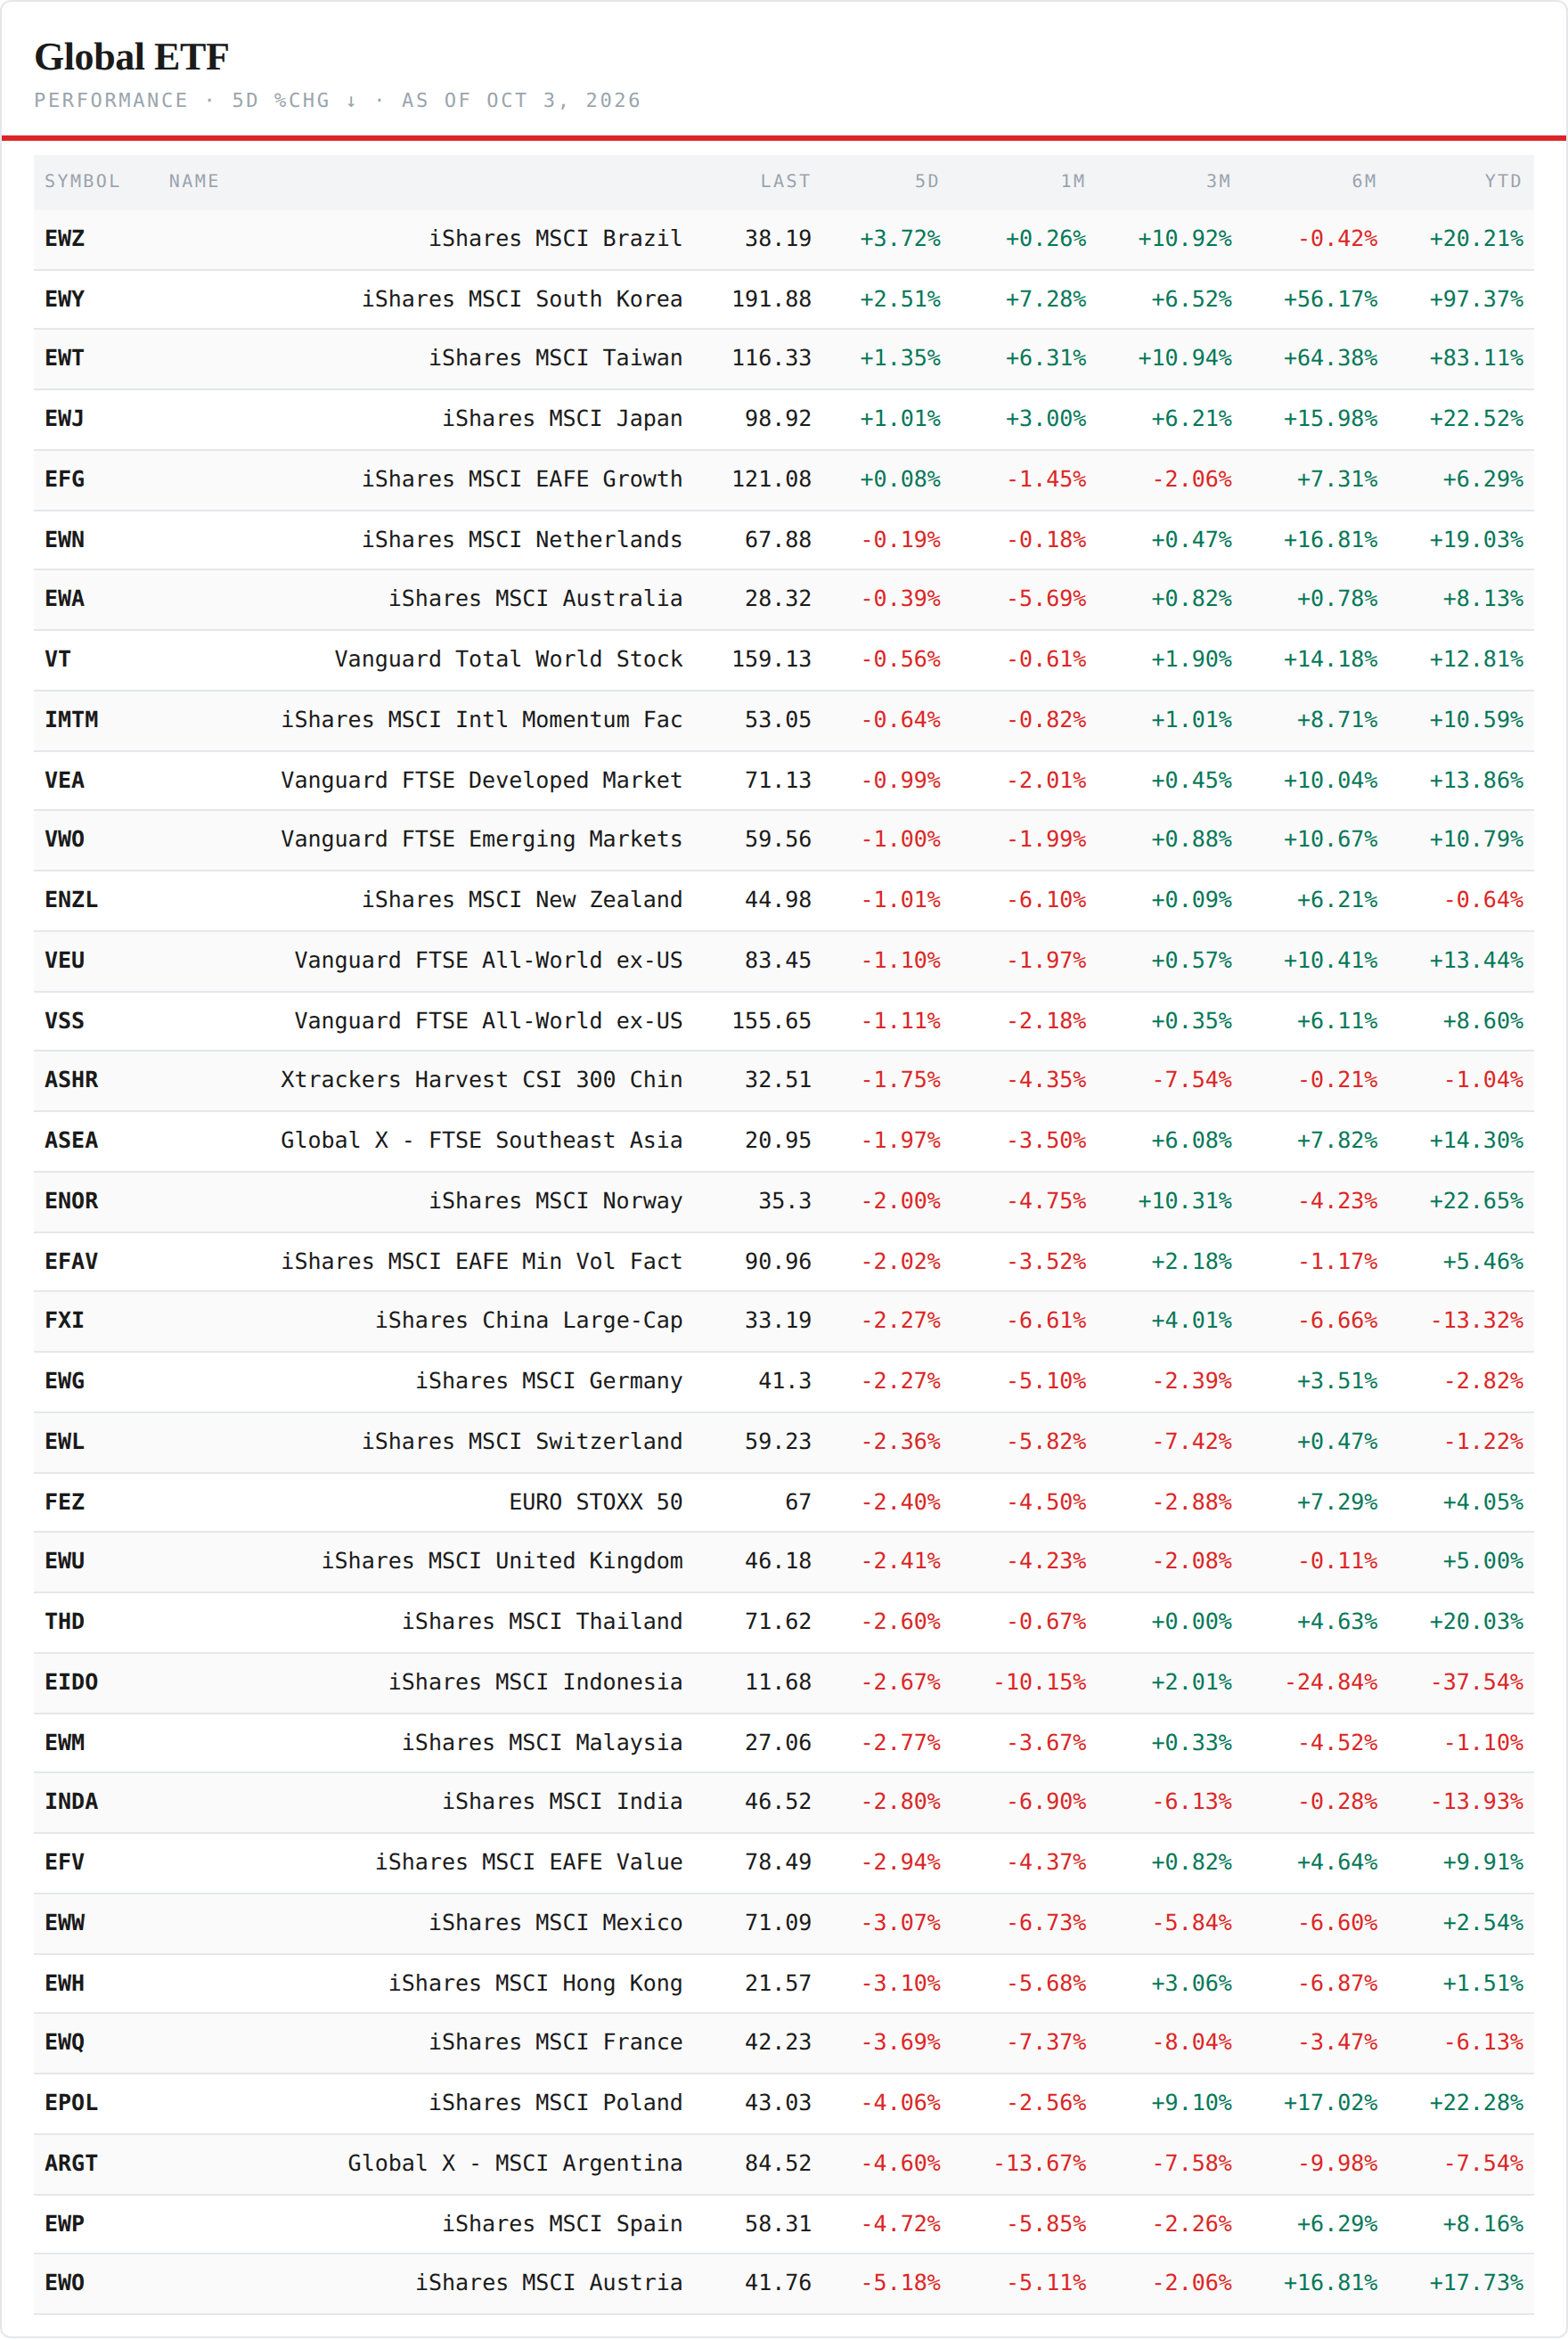
The cross-asset backdrop — the dollar and the Nasdaq, nothing else. Four green of twelve: the dollar fund +0.94%, the Nasdaq top-30 fund +0.90%, the Nasdaq 100 +0.68%, the bitcoin fund +0.34%. The red eight: silver −5.85%, gold −3.37%, the long bond −2.32%, the belly −1.06%, copper miners −0.95%, oil −0.65%, the US top-20 fund −0.37%, the S&P −0.22%. Oil slipped as Washington offered barrels from its strategic reserve on Wednesday. In one line: the market bought the currency of the country that grows and the stocks of the companies that grow fastest inside it, and sold everything that stores value — metal, duration, even the top-20 megacap basket.
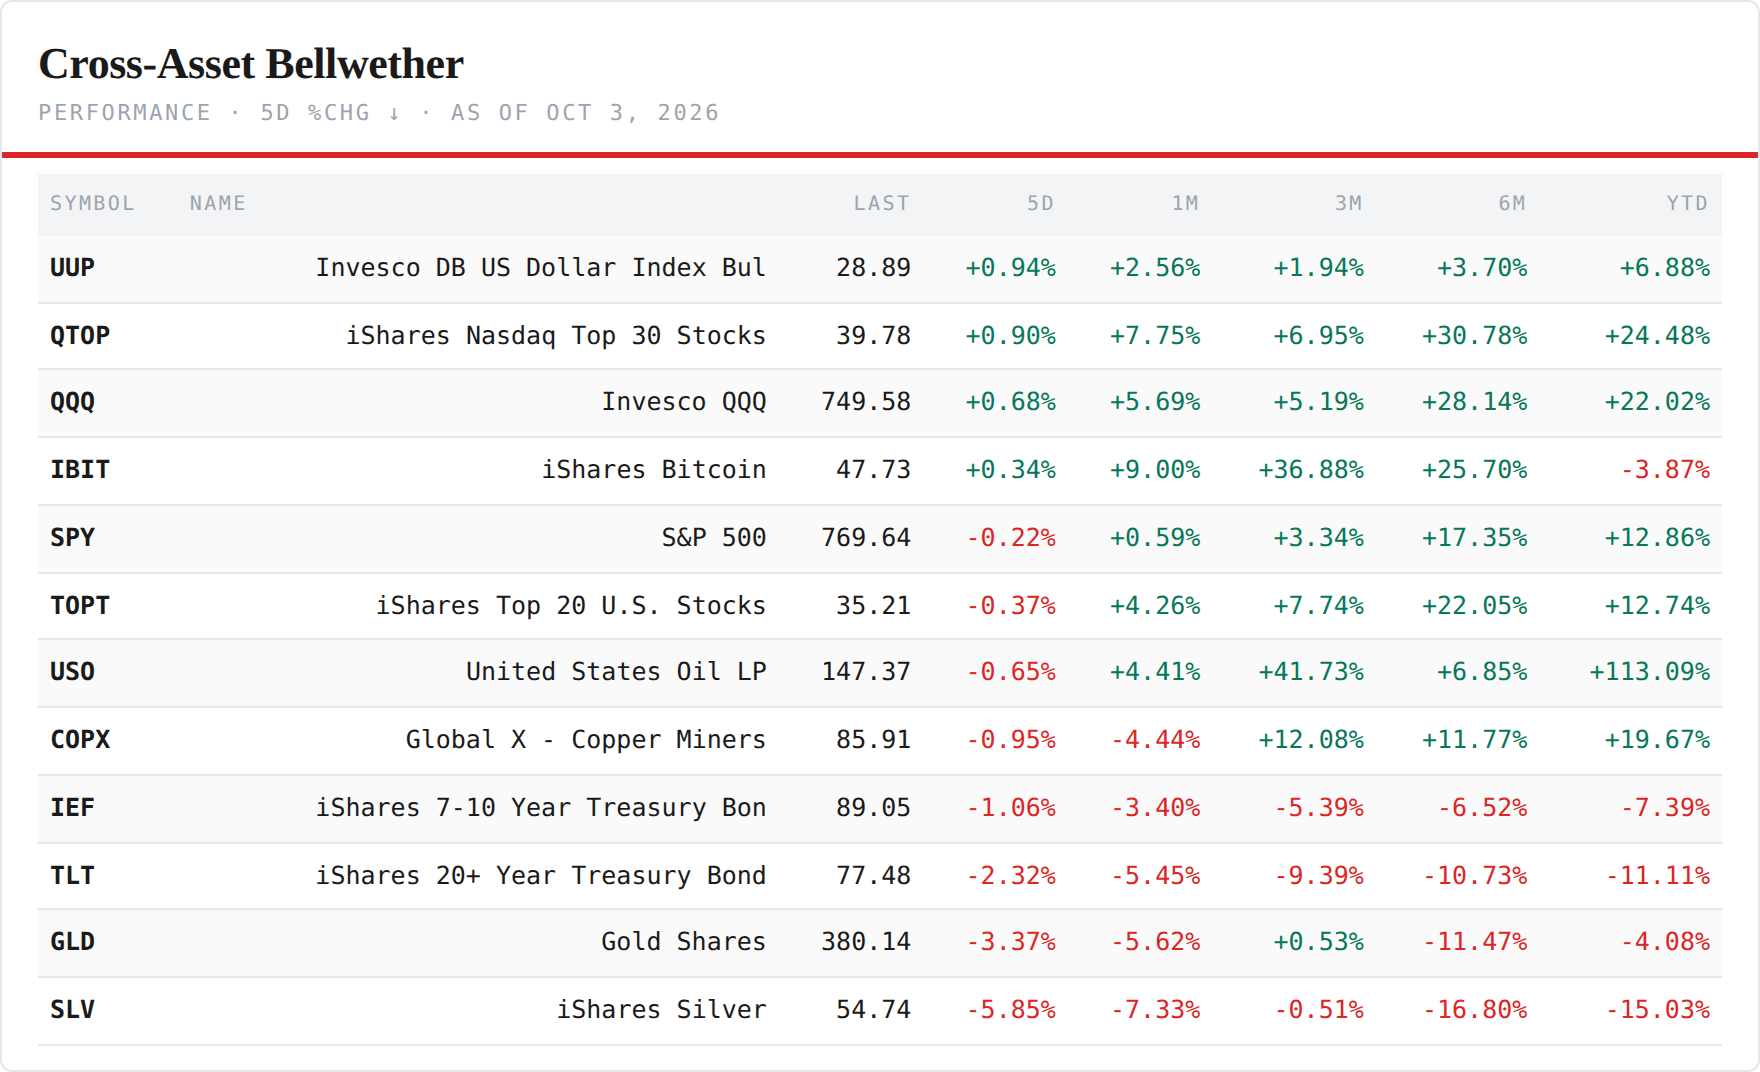
The US sectors — three of eleven green. Technology +1.80%, energy +1.26%, utilities +0.81%. The bottom: health care −2.65%, financials −2.46%, communications −2.34%, materials −1.89%, staples −1.86%, real estate −1.80%. Communications fell with Meta’s week after its agent rally; financials fell as the long end rose again. The equal-weight S&P fell 0.65% and small caps 0.16%. The index was held up by one sector, and that sector made a record.
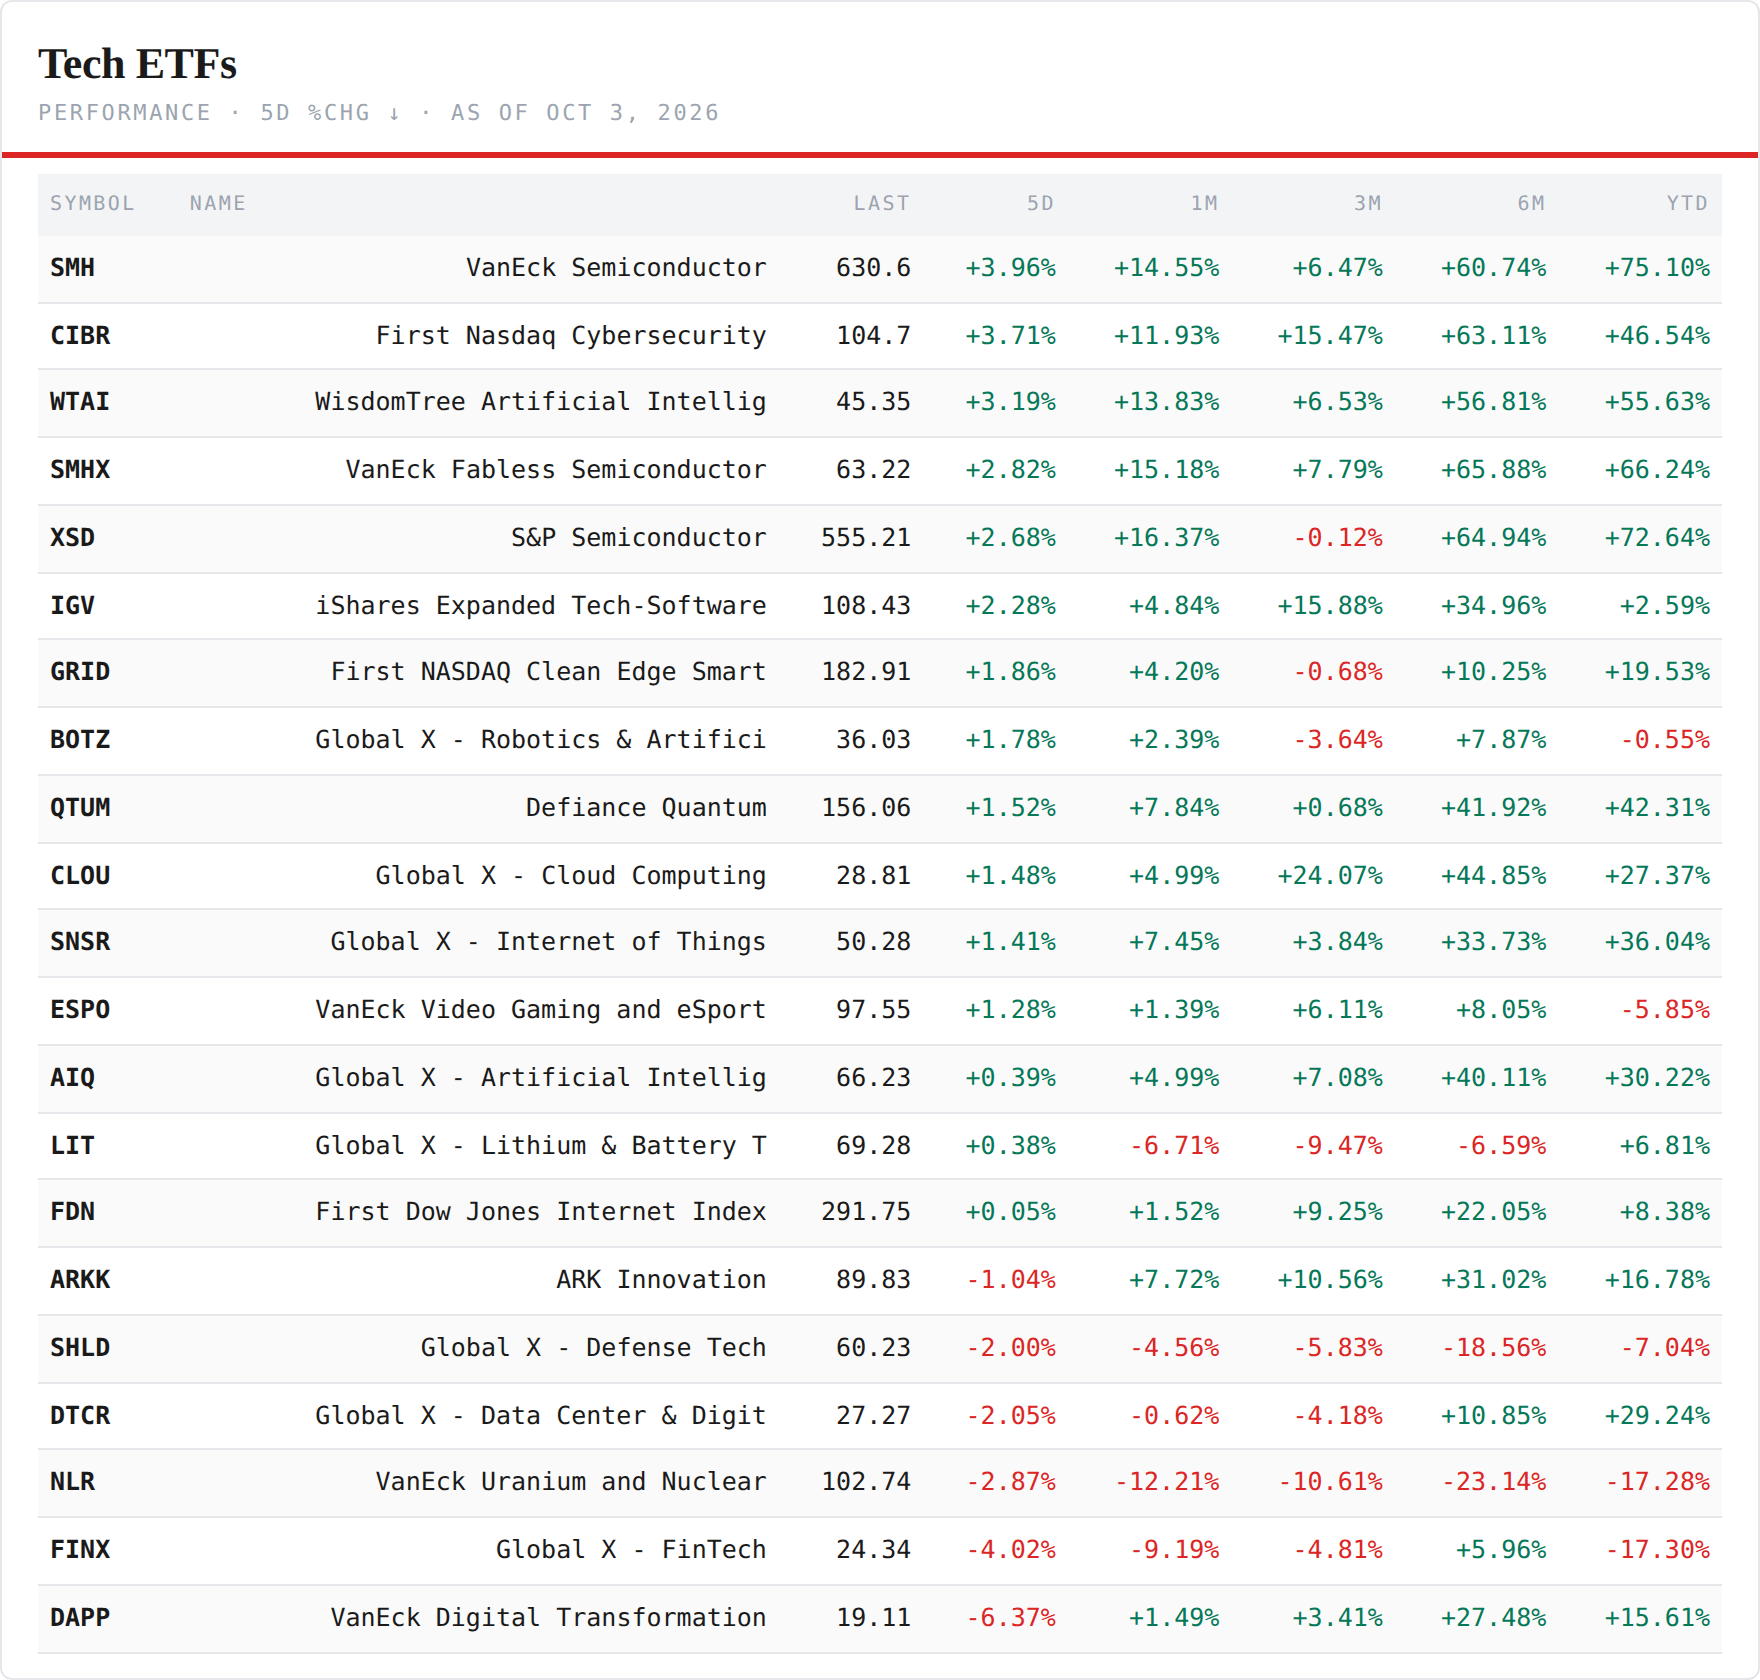
The tech ETFs — fifteen of twenty-one green. The chip majors +3.96%, cybersecurity +3.71%, the WisdomTree AI fund +3.19%, the fabless vehicle +2.82%, the equal-weight semis +2.68%, software +2.28%. The red six: digital transformation −6.37%, fintech −4.02%, uranium −2.87%, data centers −2.05%, defense tech −2.00%, ARK −1.04%. The memory vehicle DRAM was flat (−0.21%) after Micron’s record quarter on Wednesday — the numbers were superb and the stocks did not move, a market that had already paid for them. Software rose with the chips for a second week: both halves of the stack bid at once.
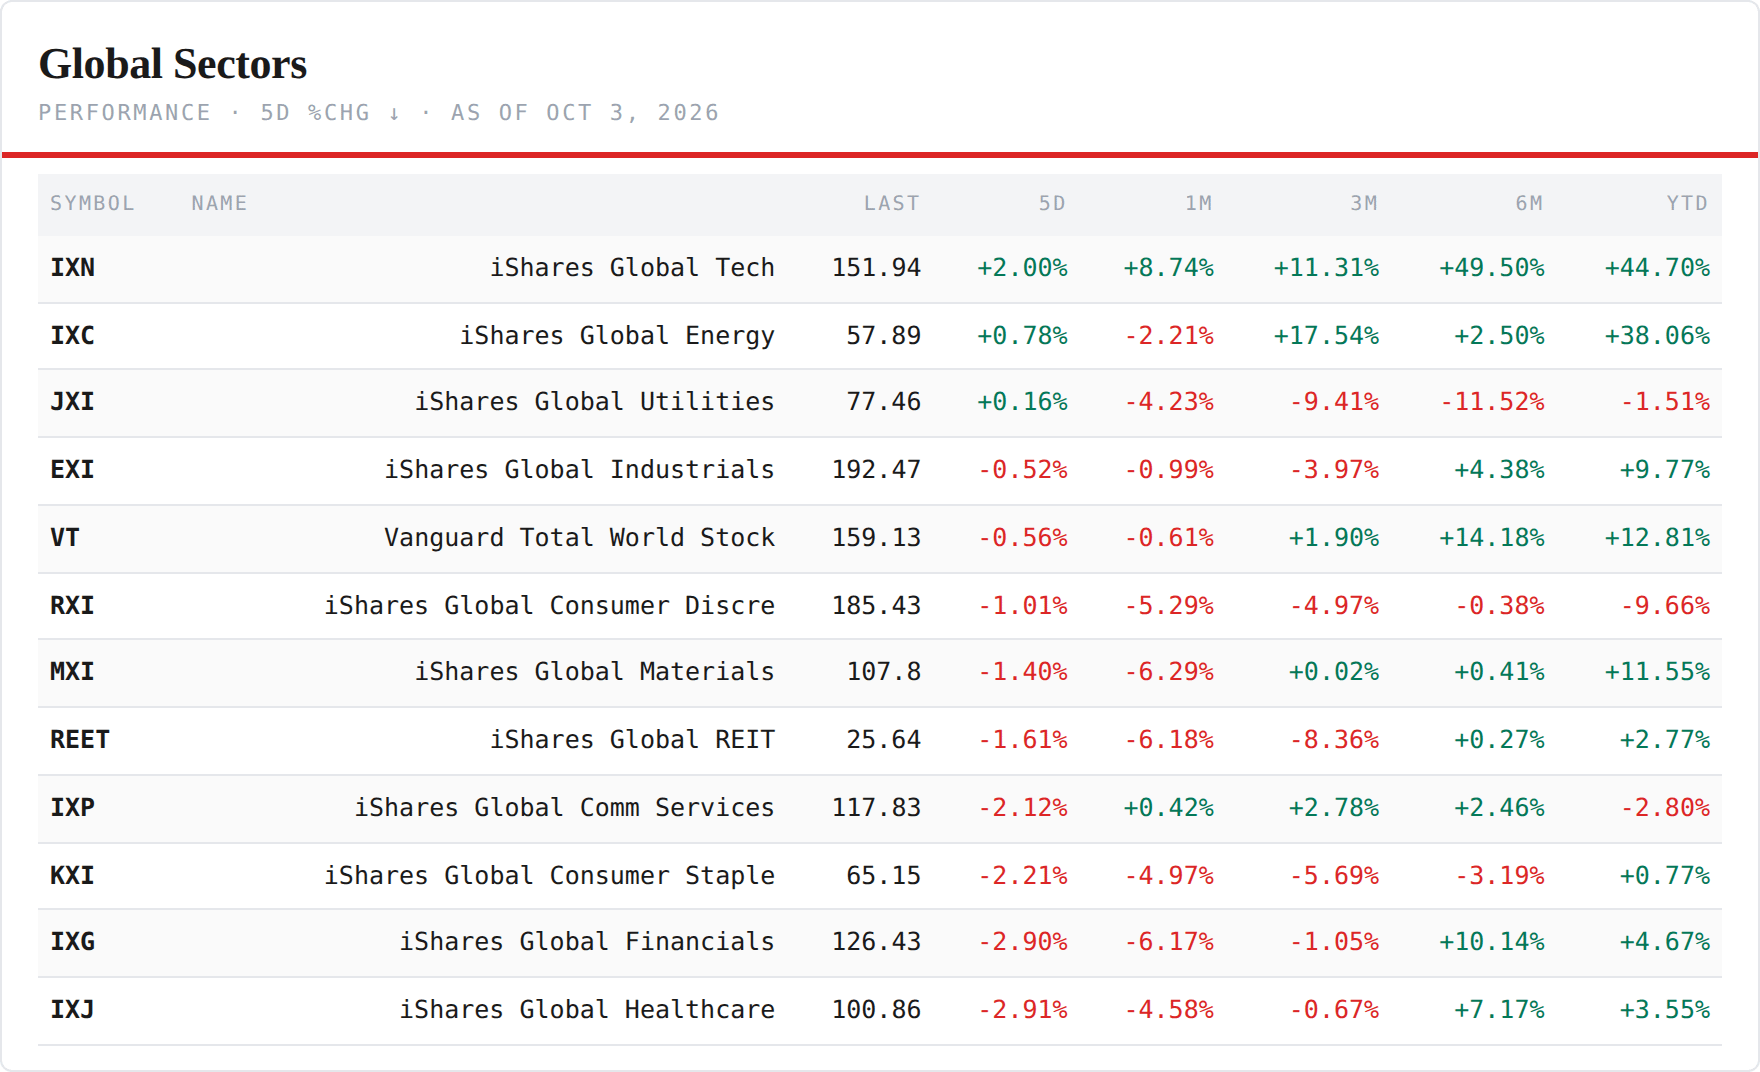
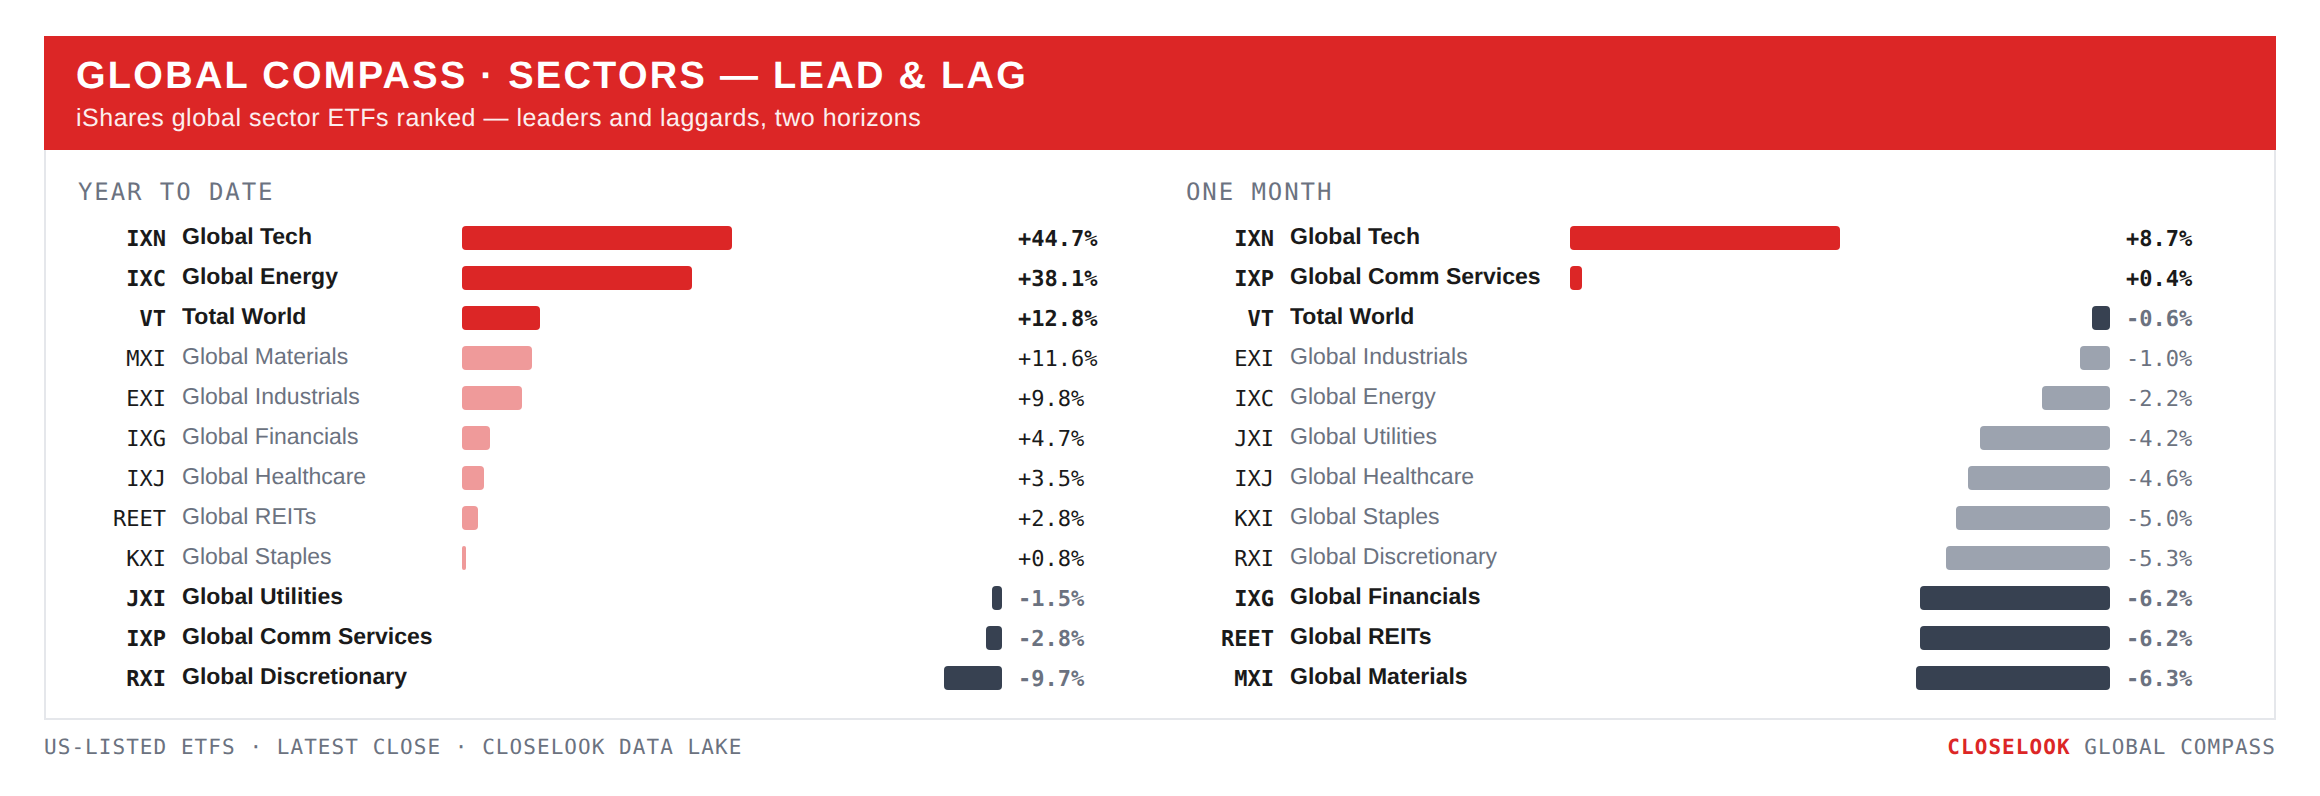
The global sectors — tech at a record, the rest red. Three of eleven green: technology +2.00% to 151.94 — a record close, through the 149.74 June high — energy +0.78%, utilities +0.16%. The bottom: health care −2.91%, financials −2.90% to 126.43, staples −2.21%, communications −2.12%, REITs −1.61%, materials −1.40% to 107.80. Financials spent a fourth week under the 134.55 August line, materials a sixth under the February line. One global sector at a record, the cyclical and defensive benches both lower: that is concentration, not breadth.
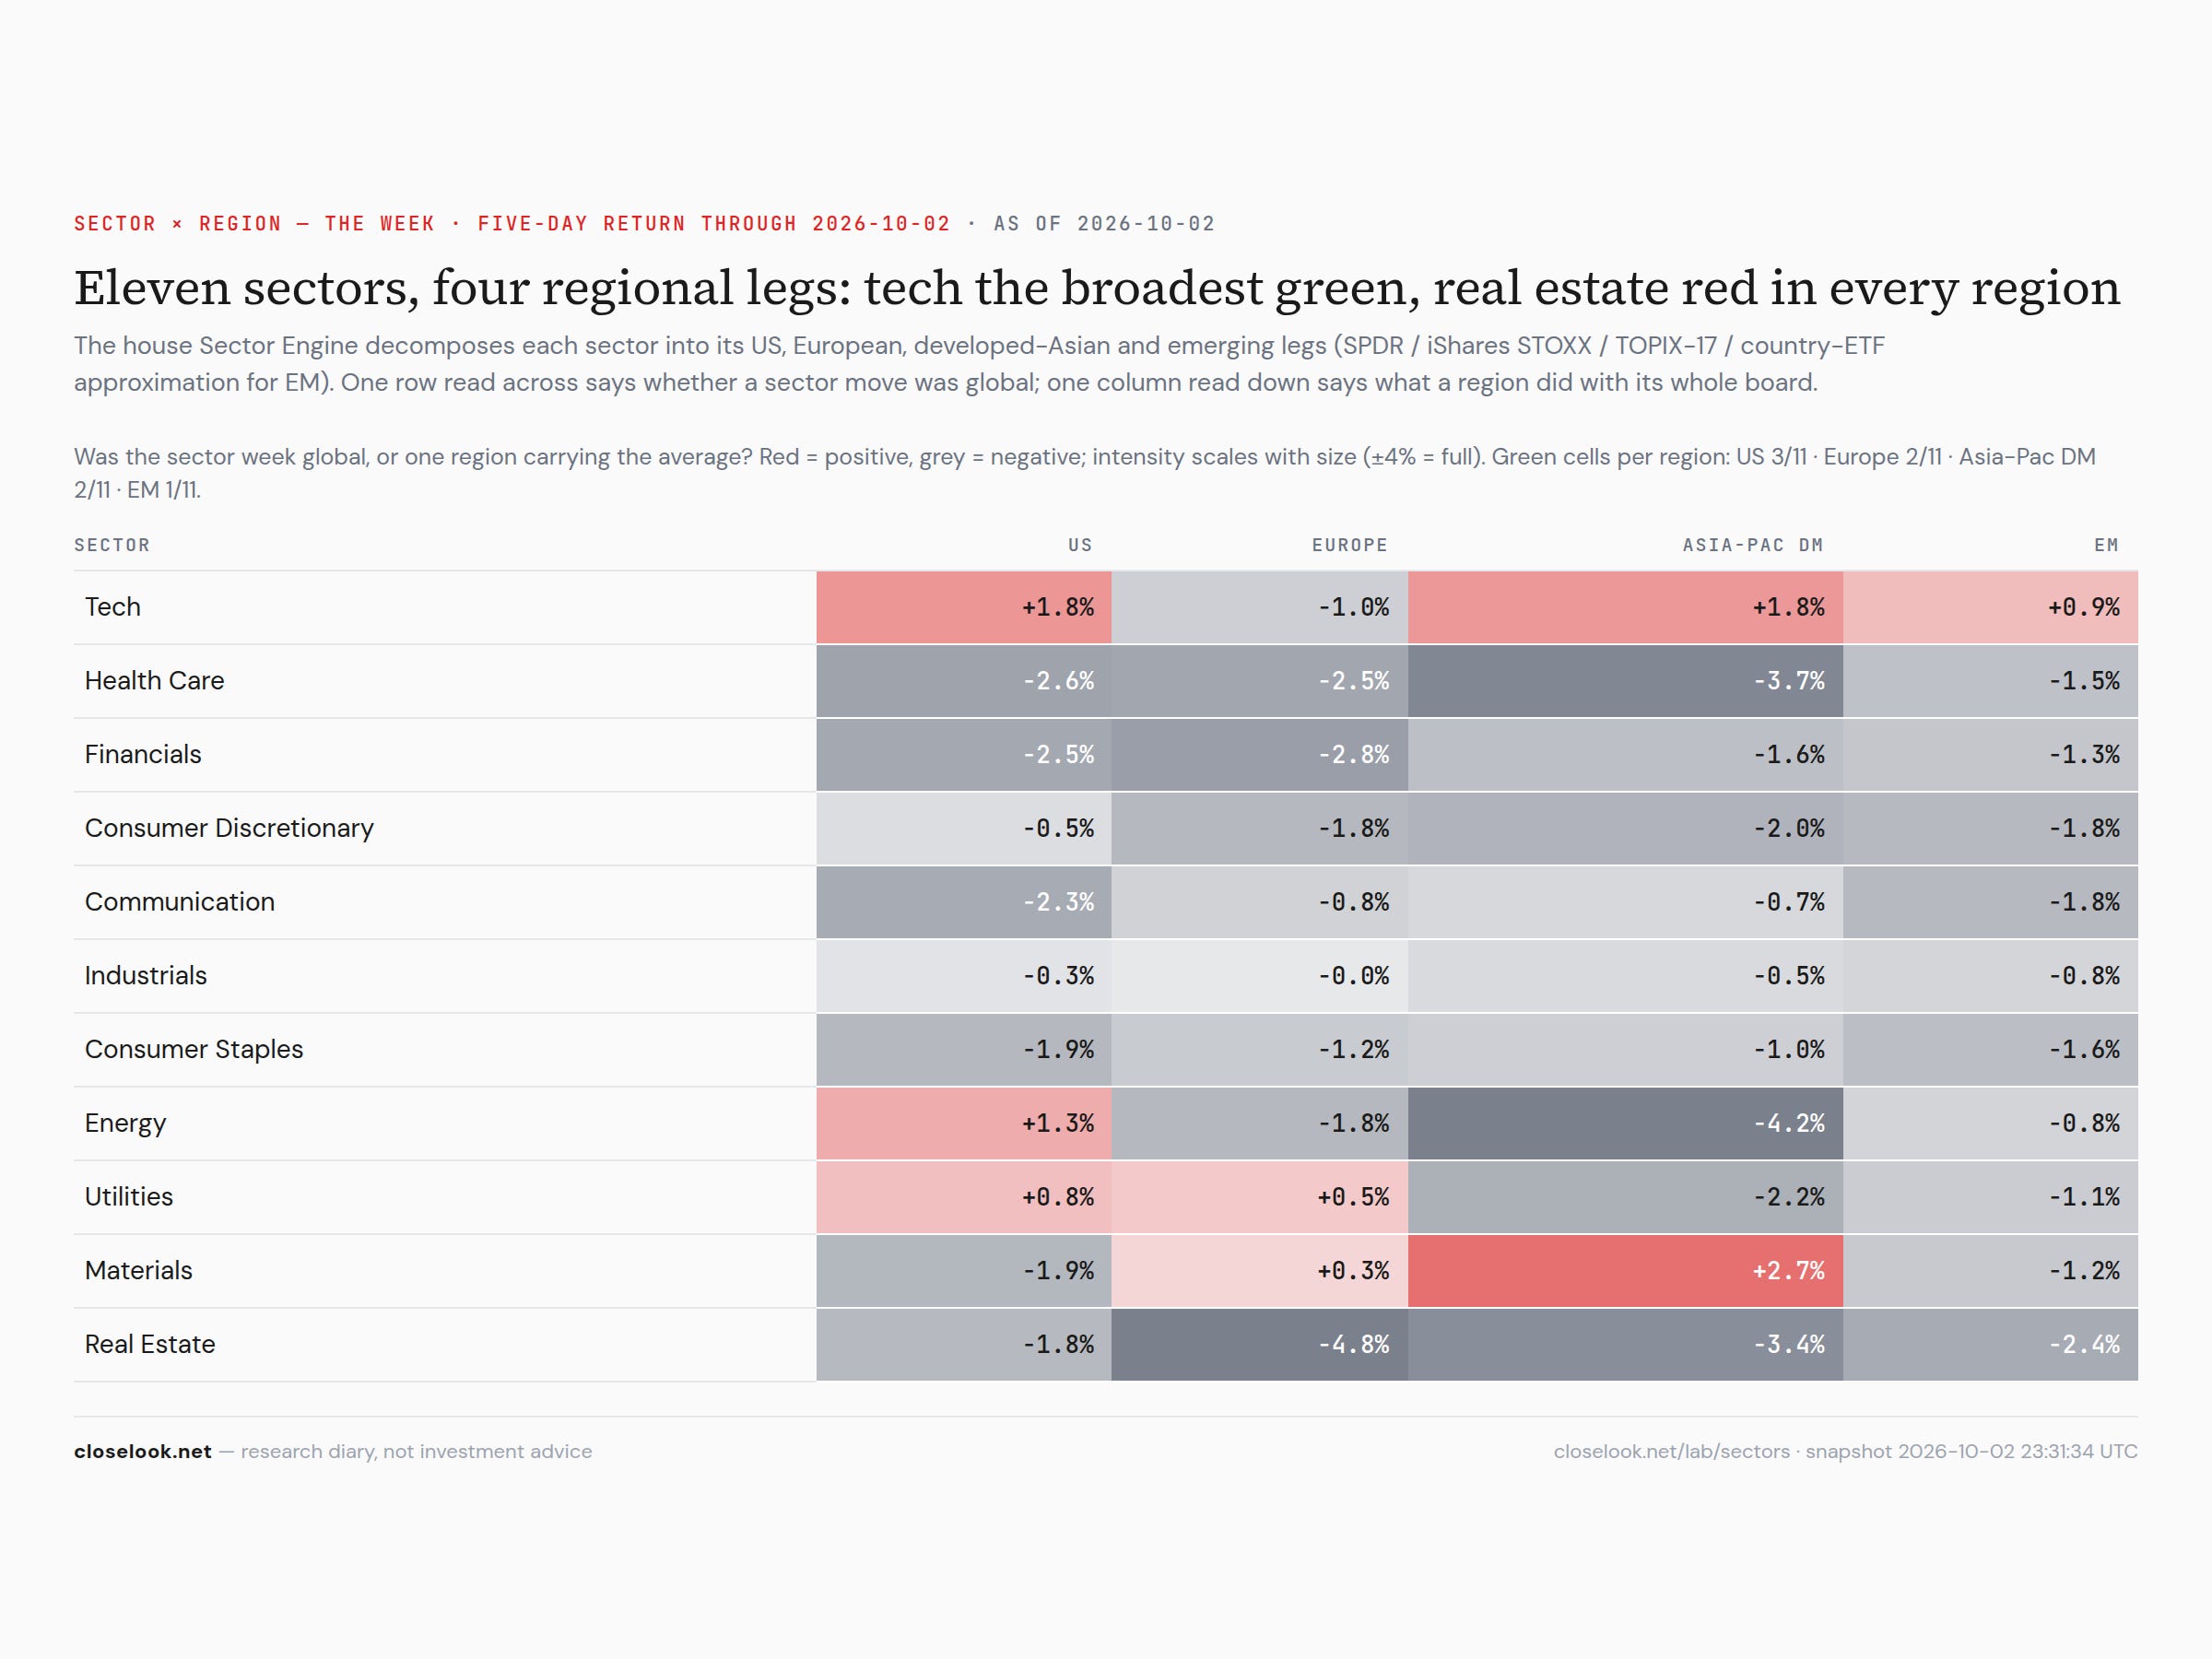
Was the sector week global, or one region carrying it? The house Sector Engine decomposes each sector into four regional legs. Technology rose in three of the four: the US +1.8%, developed Asia +1.8%, emerging markets +0.9% — and fell in Europe, −1.0%. Real estate fell in every region, Europe worst at −4.8%; health care fell in all four. The US-minus-Europe spread was positive in eight sectors of eleven, technology +2.8 points, real estate +2.9, energy +3.1. Last week tech was green in every region. This week Europe’s leg broke away — the same week its sovereign spreads widened.
The Global Compass
Regions: developed and emerging tied; the corridor beat both. VEA −0.99% against VWO −1.00% — a dead heat on the broad wrappers, both red, with the chip exporters at the top and Mexico, Hong Kong, India and Indonesia at the bottom. China’s large caps fell 2.27% and its A-shares 1.75% into Golden Week, which shut the mainland from Thursday.
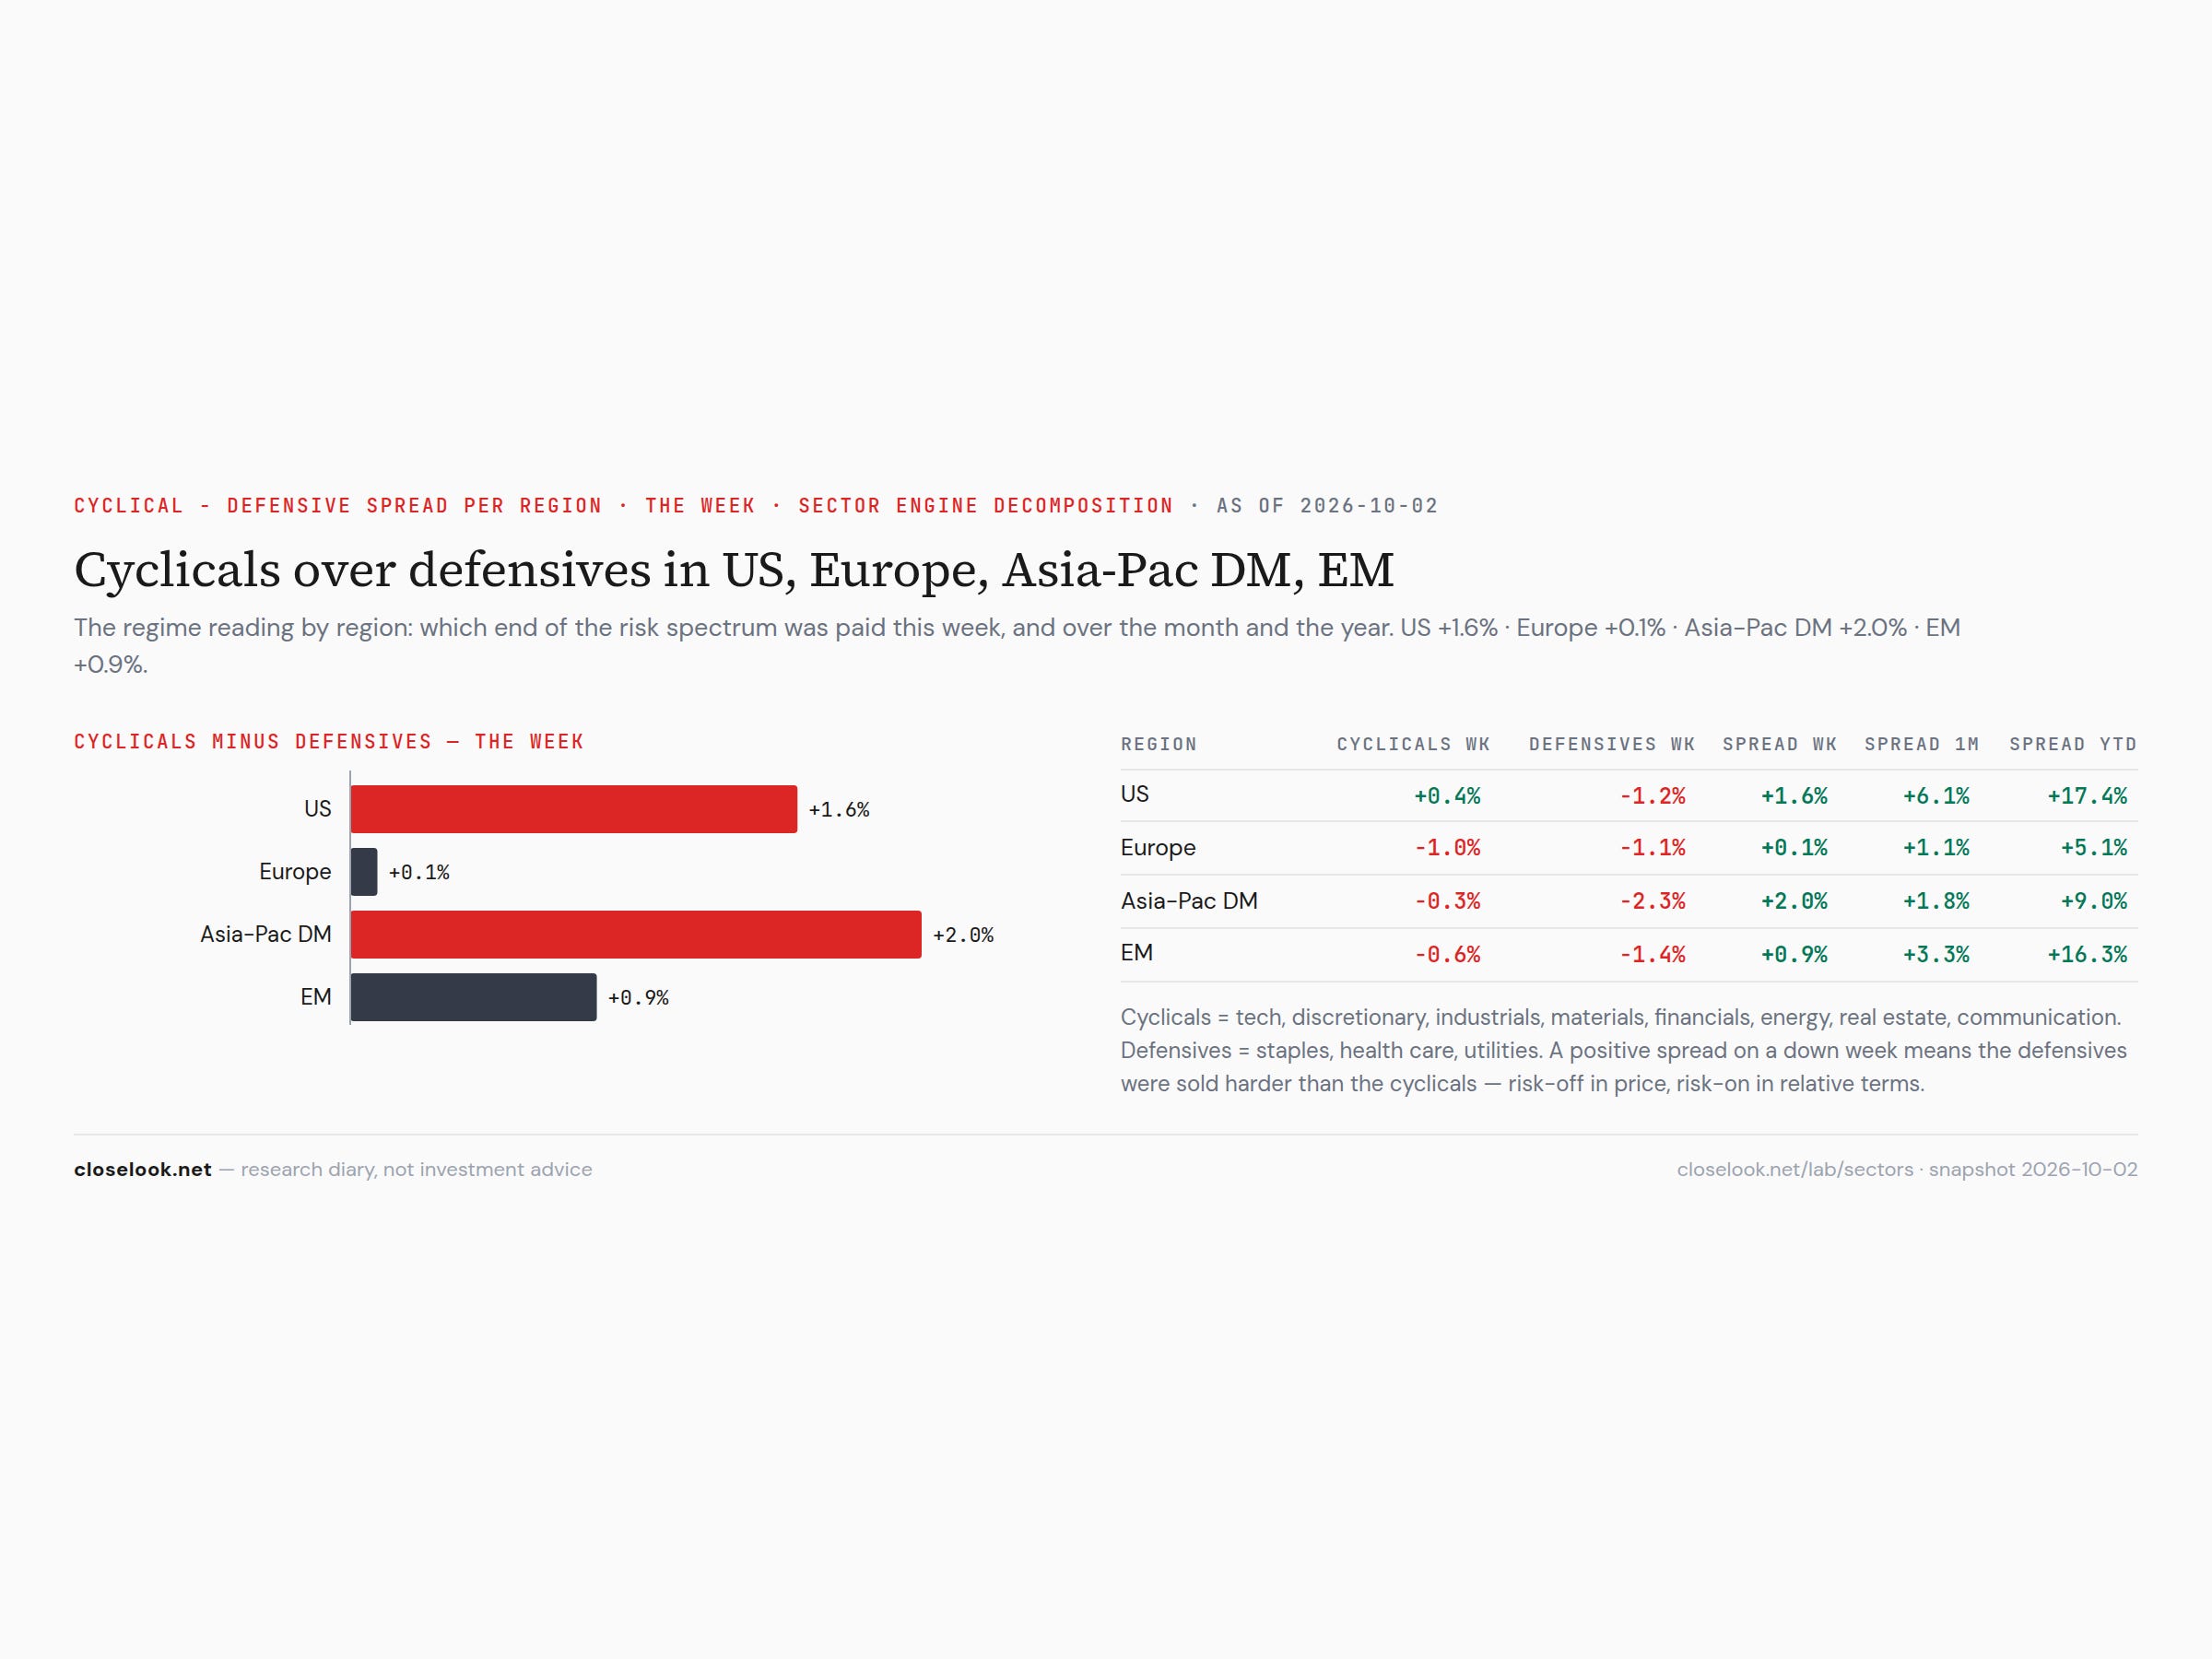
Sectors: cyclicals over defensives everywhere except Europe. The engine’s cyclical-minus-defensive spread was +1.6 points in the US, +2.0 in developed Asia, +0.9 in emerging markets — and +0.1 in Europe, where cyclicals and defensives fell together. On the year the US spread is +17.4 points and Europe’s +5.1. Europe did not rotate this week; it de-rated across the board.
Sectors: the leaders’ bench, at the new distances. Technology 151.94, a record, after closing the 0.5% gap in two sessions. Industrials 192.47, 6.9% under August. Financials 126.43, 7.7% under its September 3 record, four weeks under its line. Materials 107.80, 9.0% under its August 25 record, six weeks under the February line. Last week the bench split; this week the split widened: one sector at the top, the commodity and credit pair drifting further down.
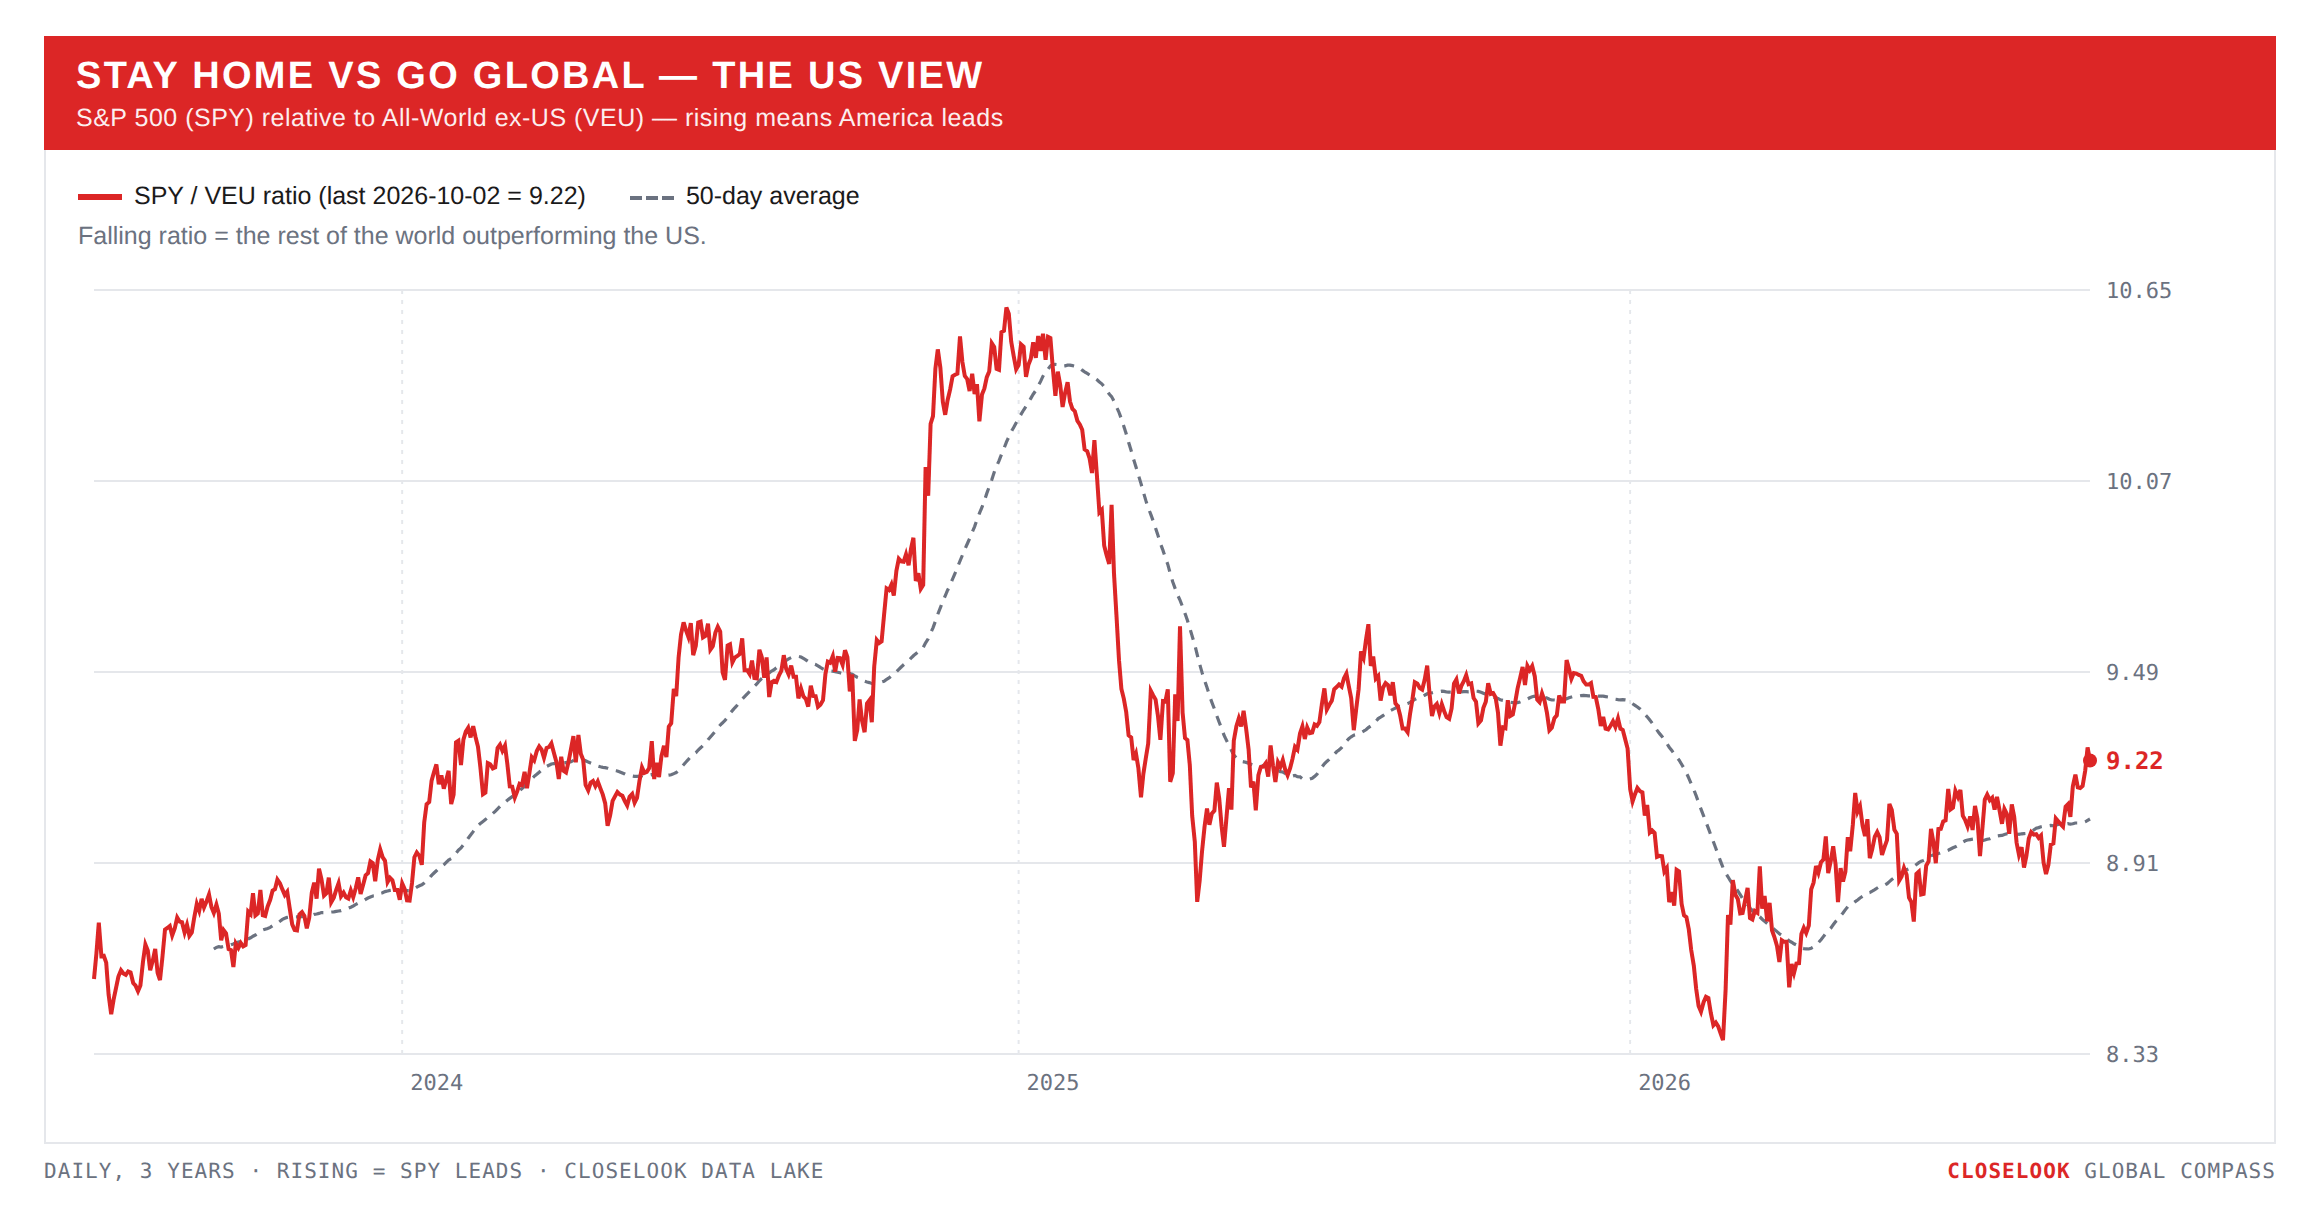
Stay home vs go global — the US view. America won a fourth week: SPY −0.22%, VT −0.56%, VEU −1.10%. The year still reads ex-US first, by a hair: +13.4% against +12.9% against +12.8%. In four weeks the lead has gone from 4.5 points to 0.6. On the current pace the year’s order flips within a fortnight, and the line on the chart below says the same thing more quietly: the SPY/VEU ratio has turned up from its September low.
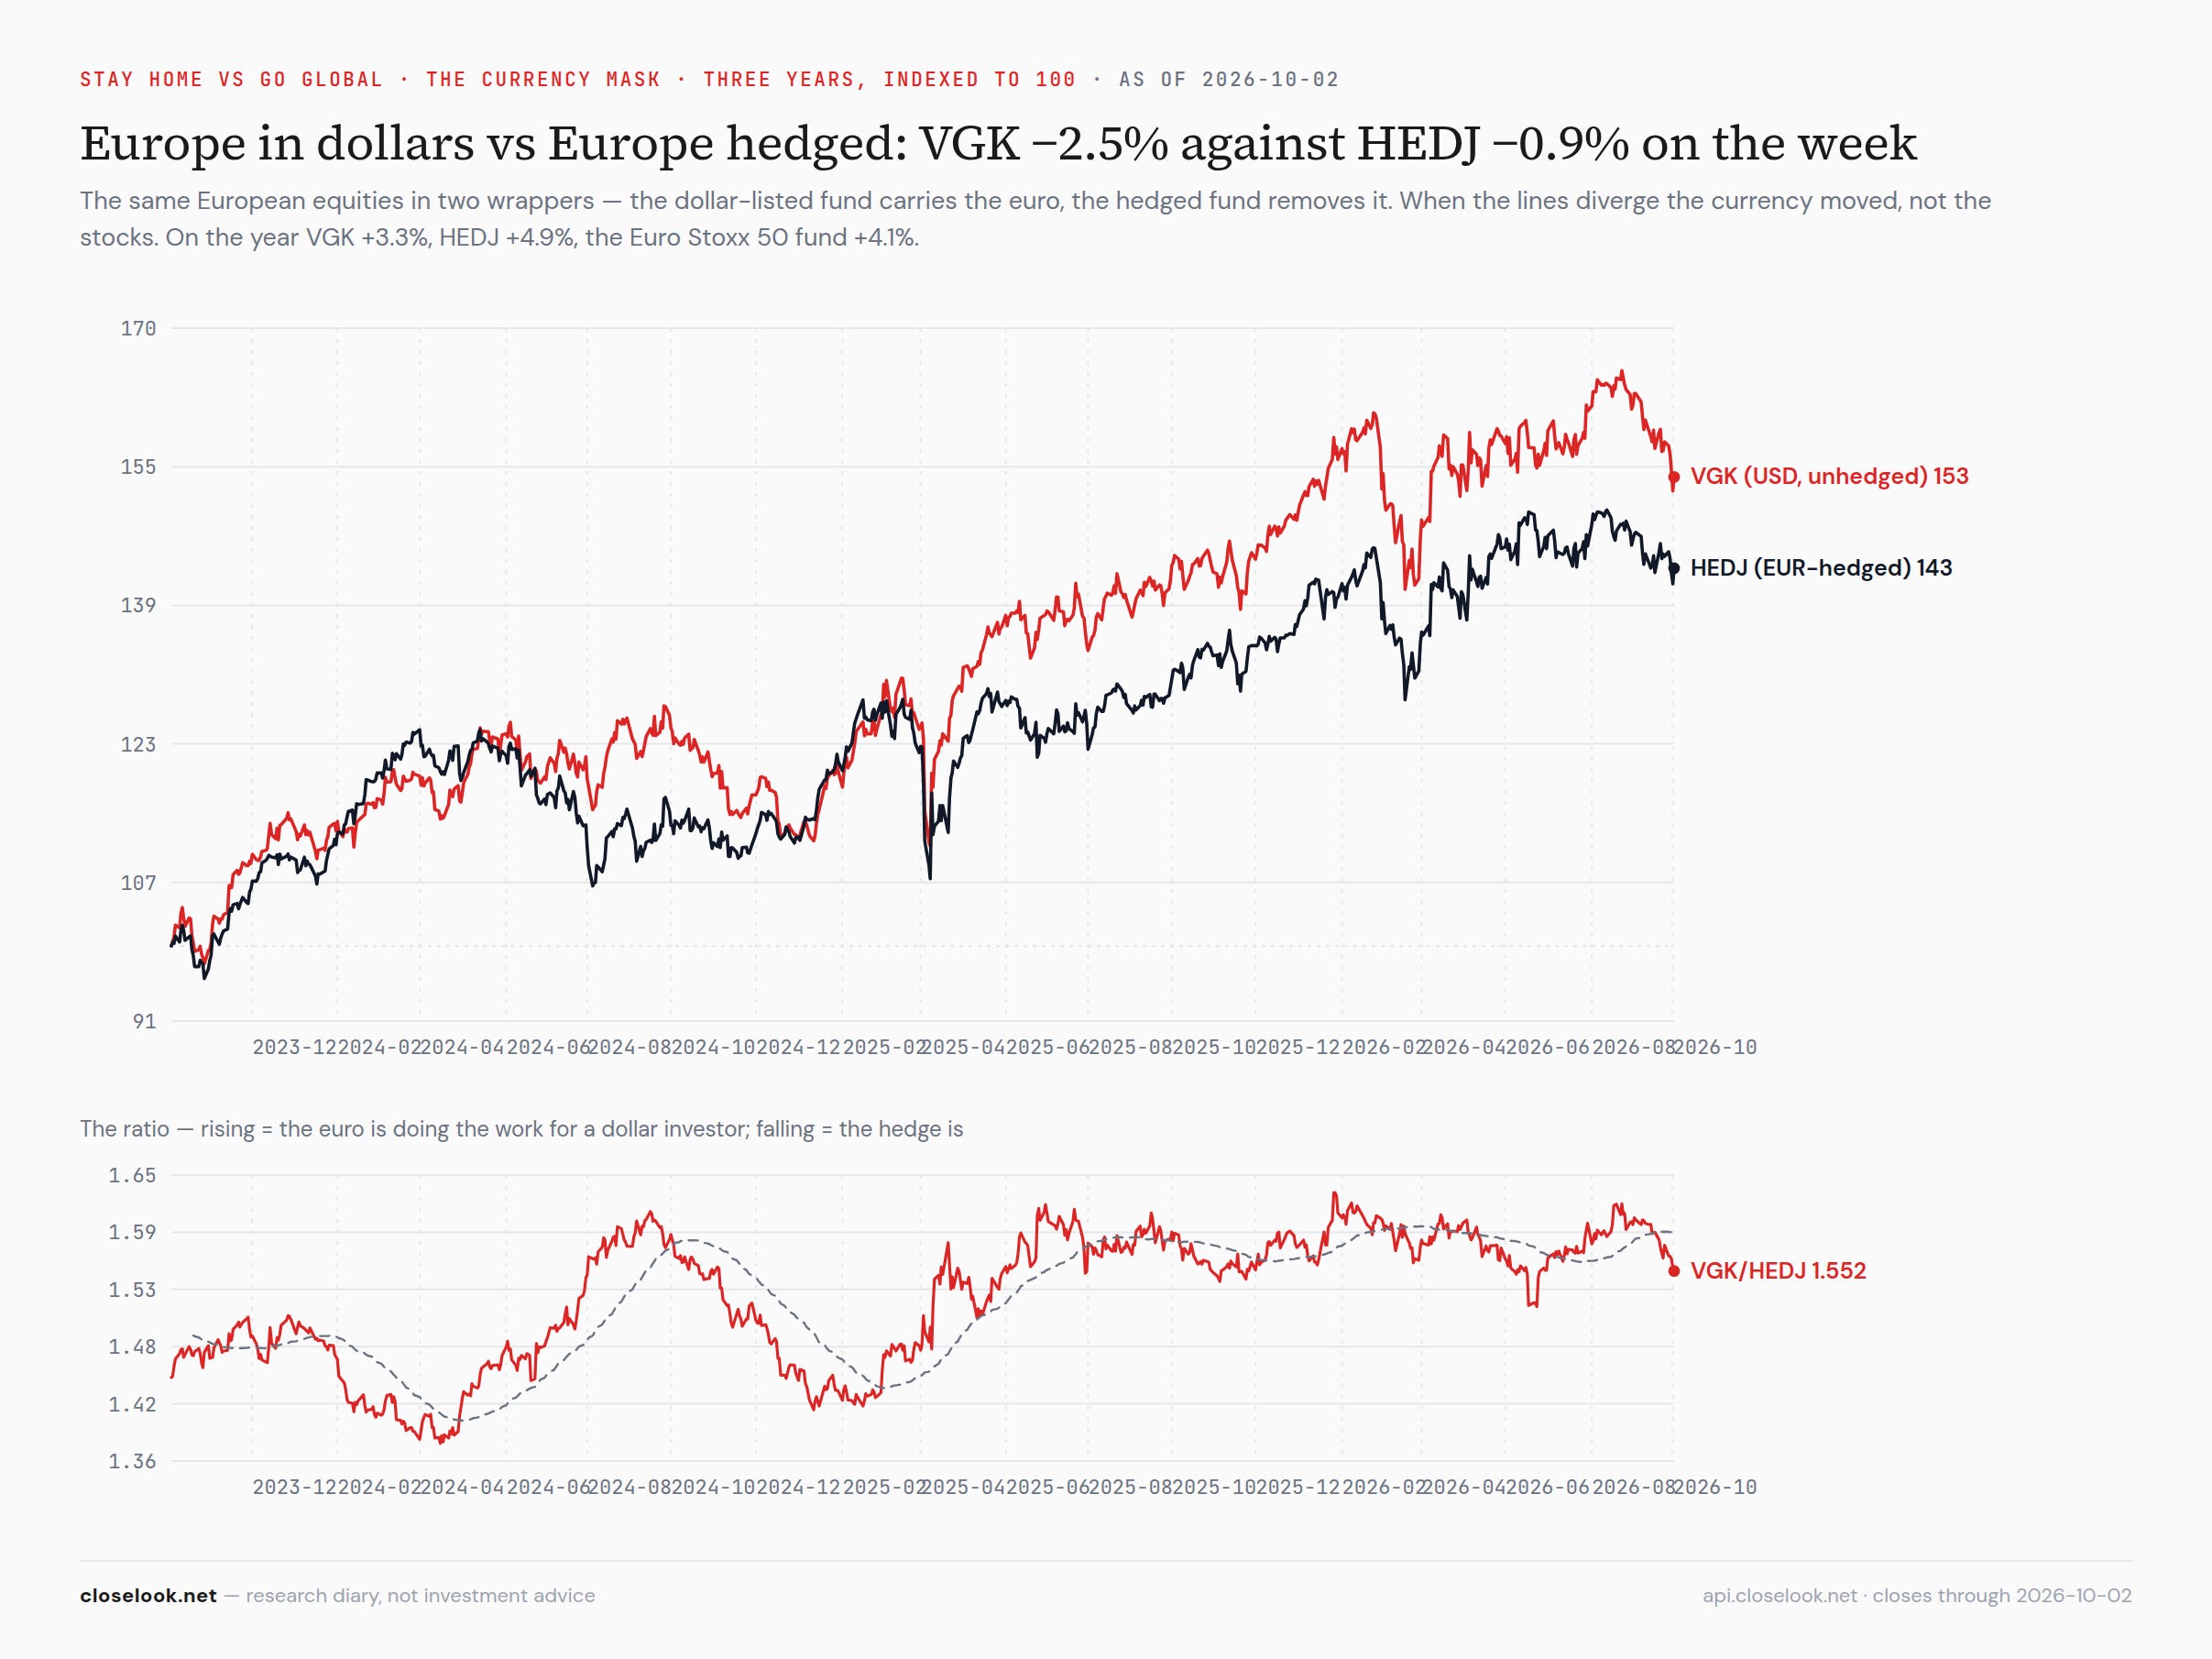
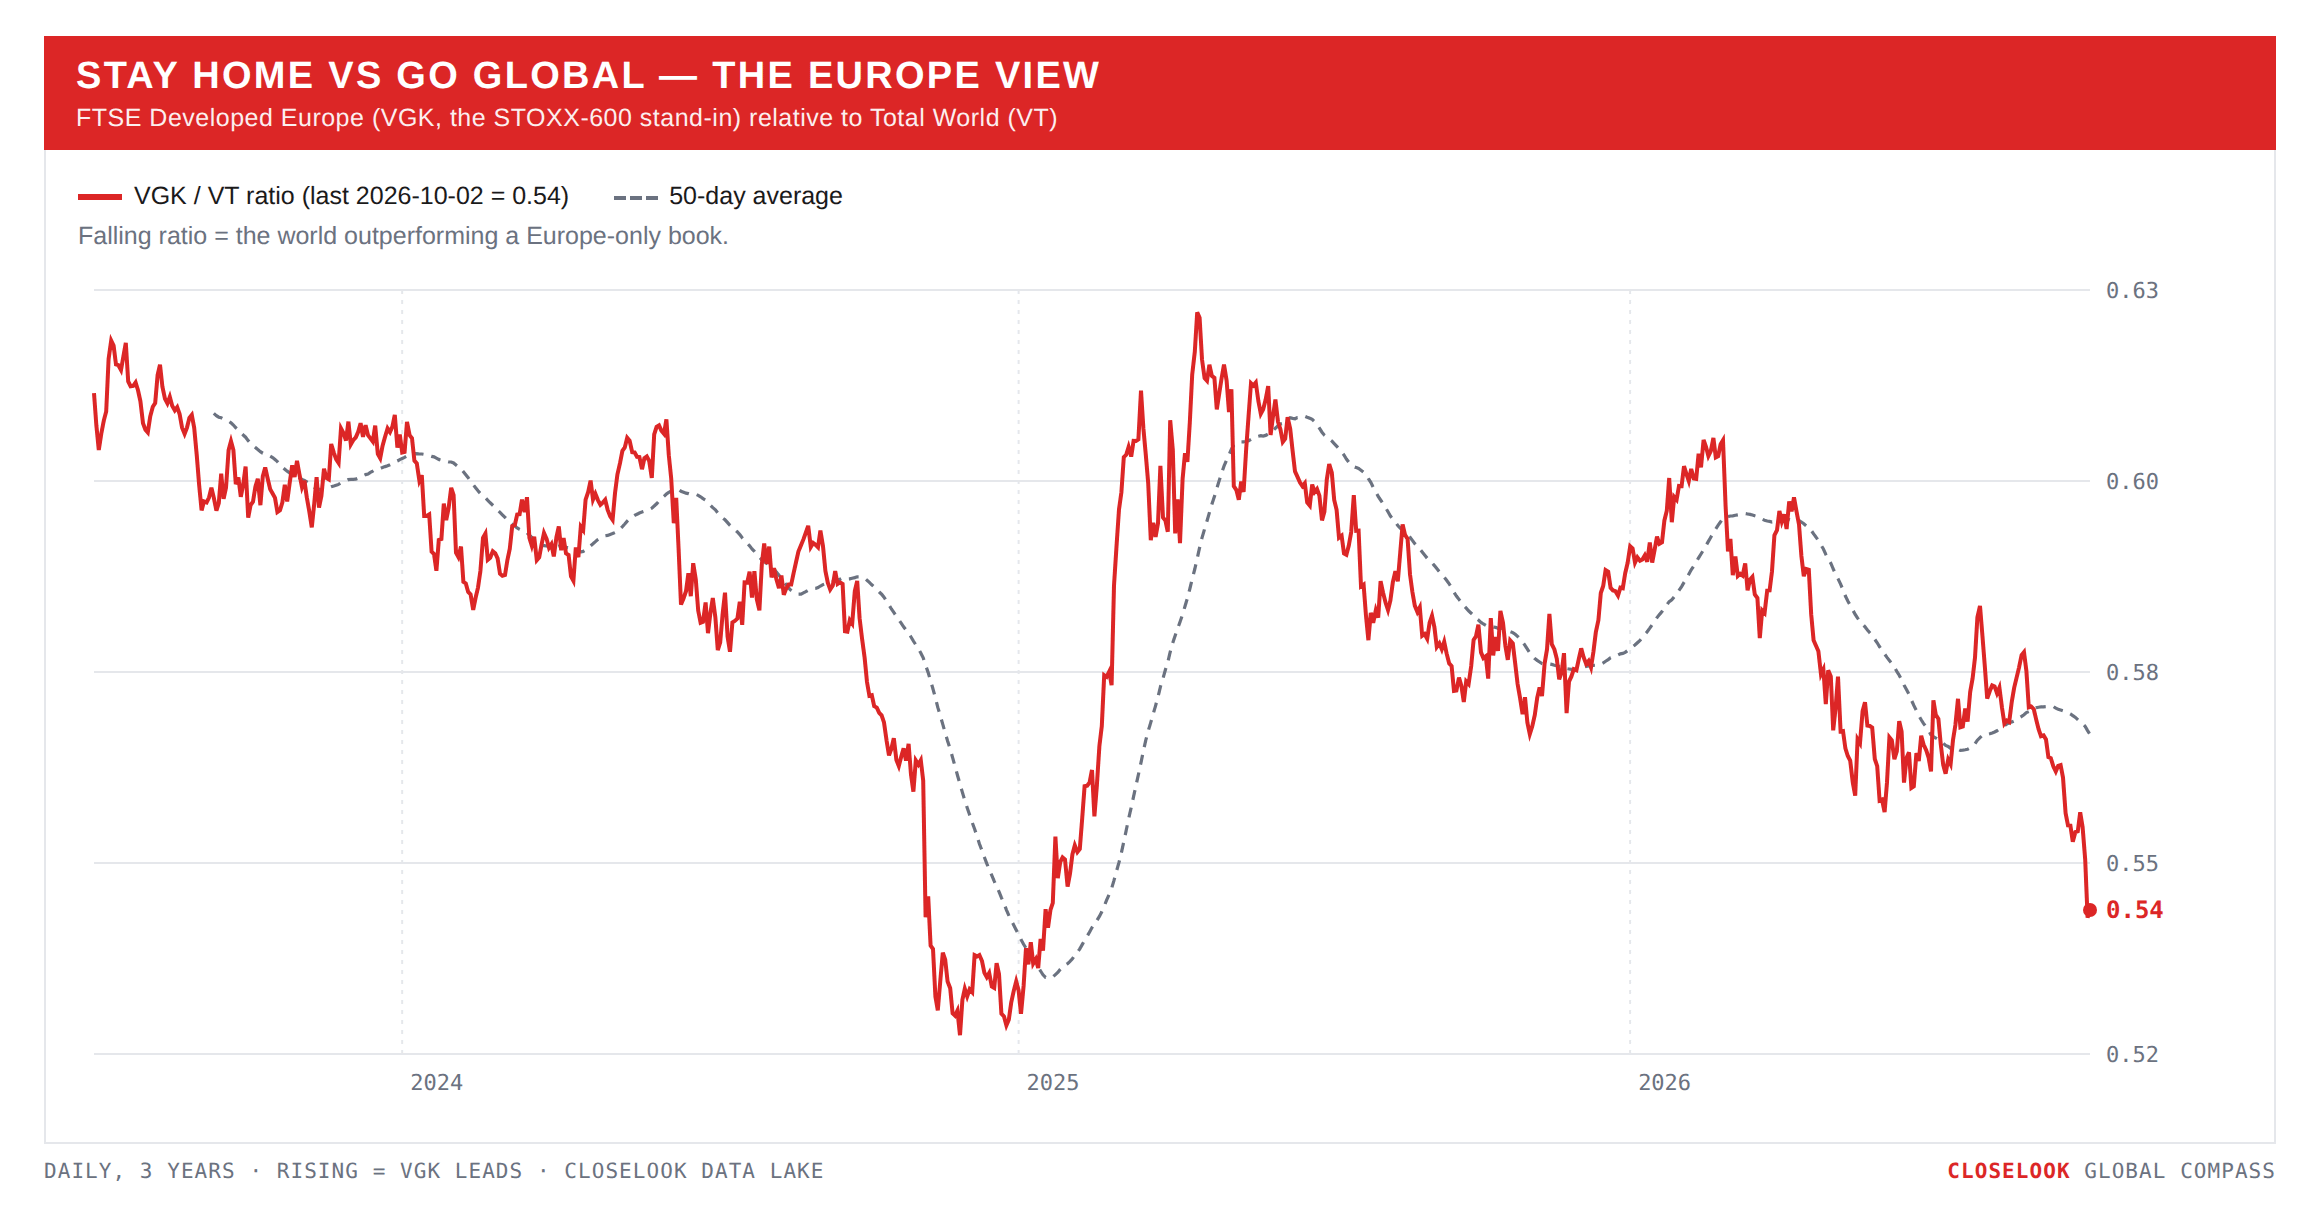
Stay home vs go global — the Europe view: the currency became the cost. The euro-hedged Europe fund fell 0.94%; the dollar-listed one fell 2.54% — 1.6 points of the loss were the euro. In local terms: the STOXX 600 −1.28%, the Euro Stoxx 50 −1.02%, the DAX −0.70% to 25,231, the CAC −1.96% to 7,920, Spain’s IBEX −3.12%, the FTSE 100 −2.18%, Switzerland’s SMI −1.90%. For seven weeks this letter has called the gap between the two funds a mask that flips. This week it did not flip. It cost.
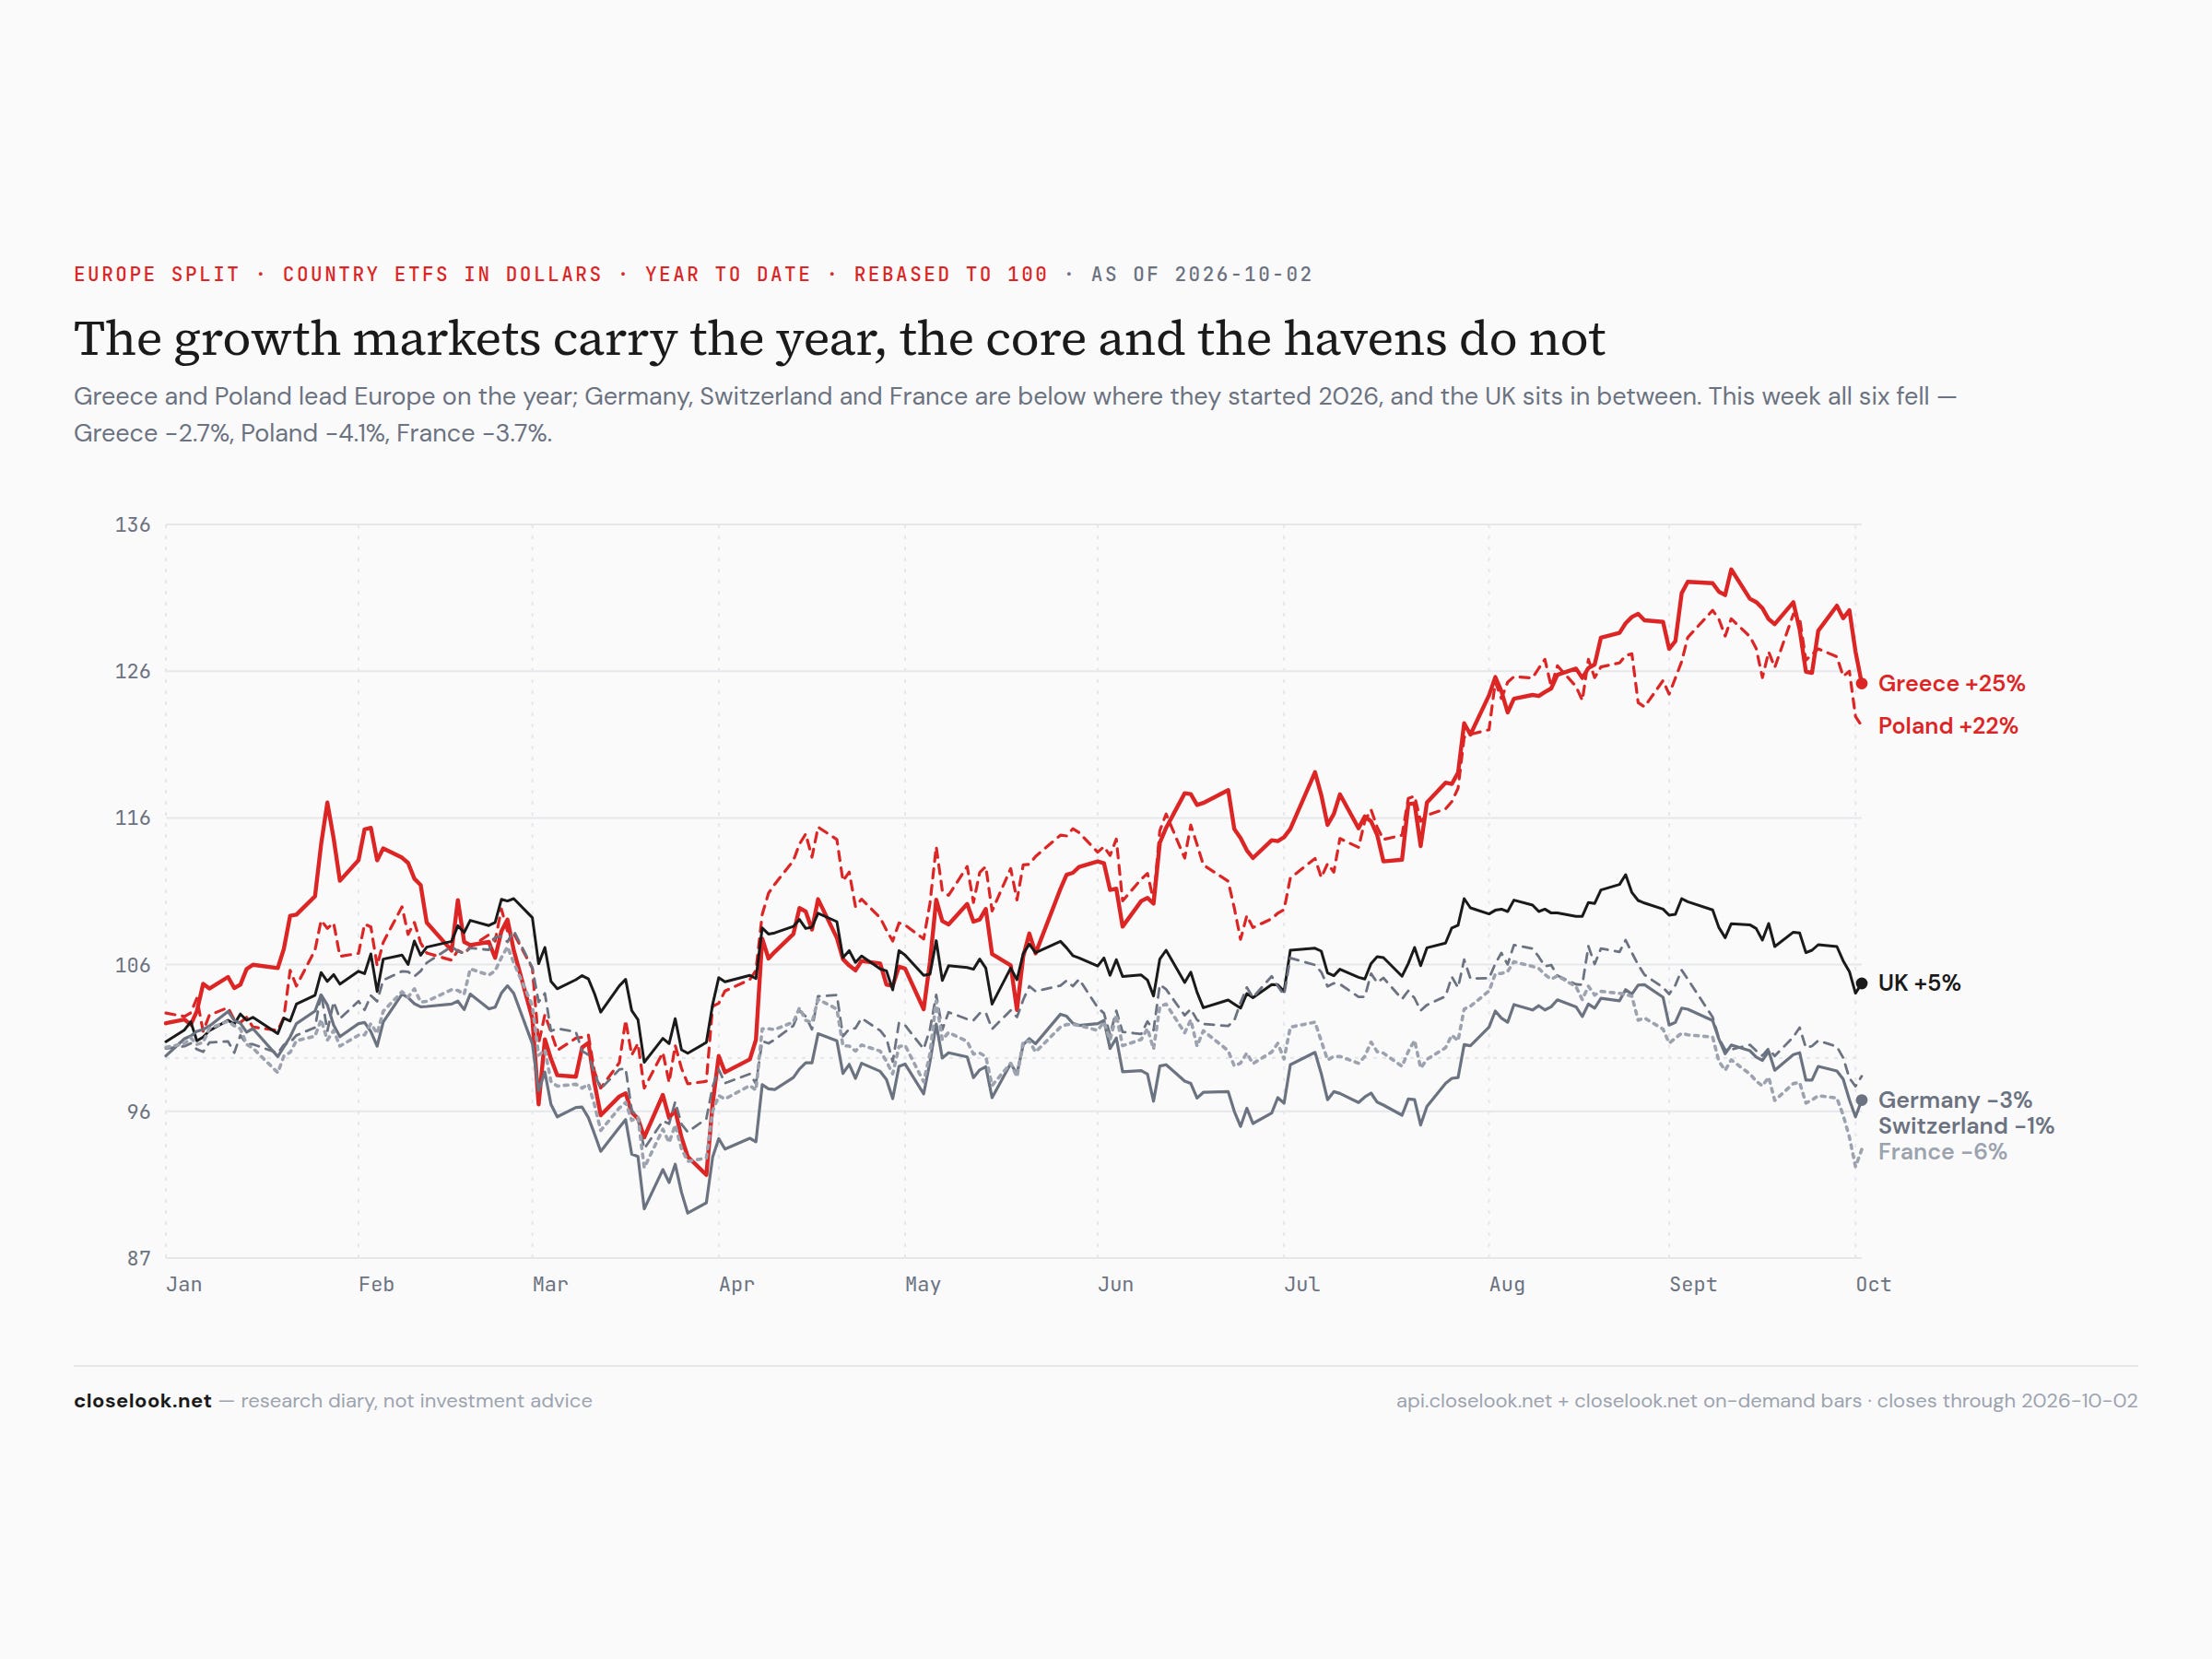
Europe split — the growth markets and everyone else. The year in Europe is not one market either. Greece +25% and Poland +22% in dollars; Britain +5%; the Netherlands +19% and Austria +18% on the ASML and chip-equipment leg; Switzerland −1%, Germany −3%, France −6%. The two markets with their own growth — Poland’s economy, Greece’s repaired finances, now cheaper to borrow for than France — carry the year. The core and the havens do not. This week was the exception: Greece fell 2.75% and Poland 4.06%, both more than the core. When money leaves a region, it leaves the best-performing corners too — they are where the gains are to take. The thesis is a year’s thesis; the week tested it.
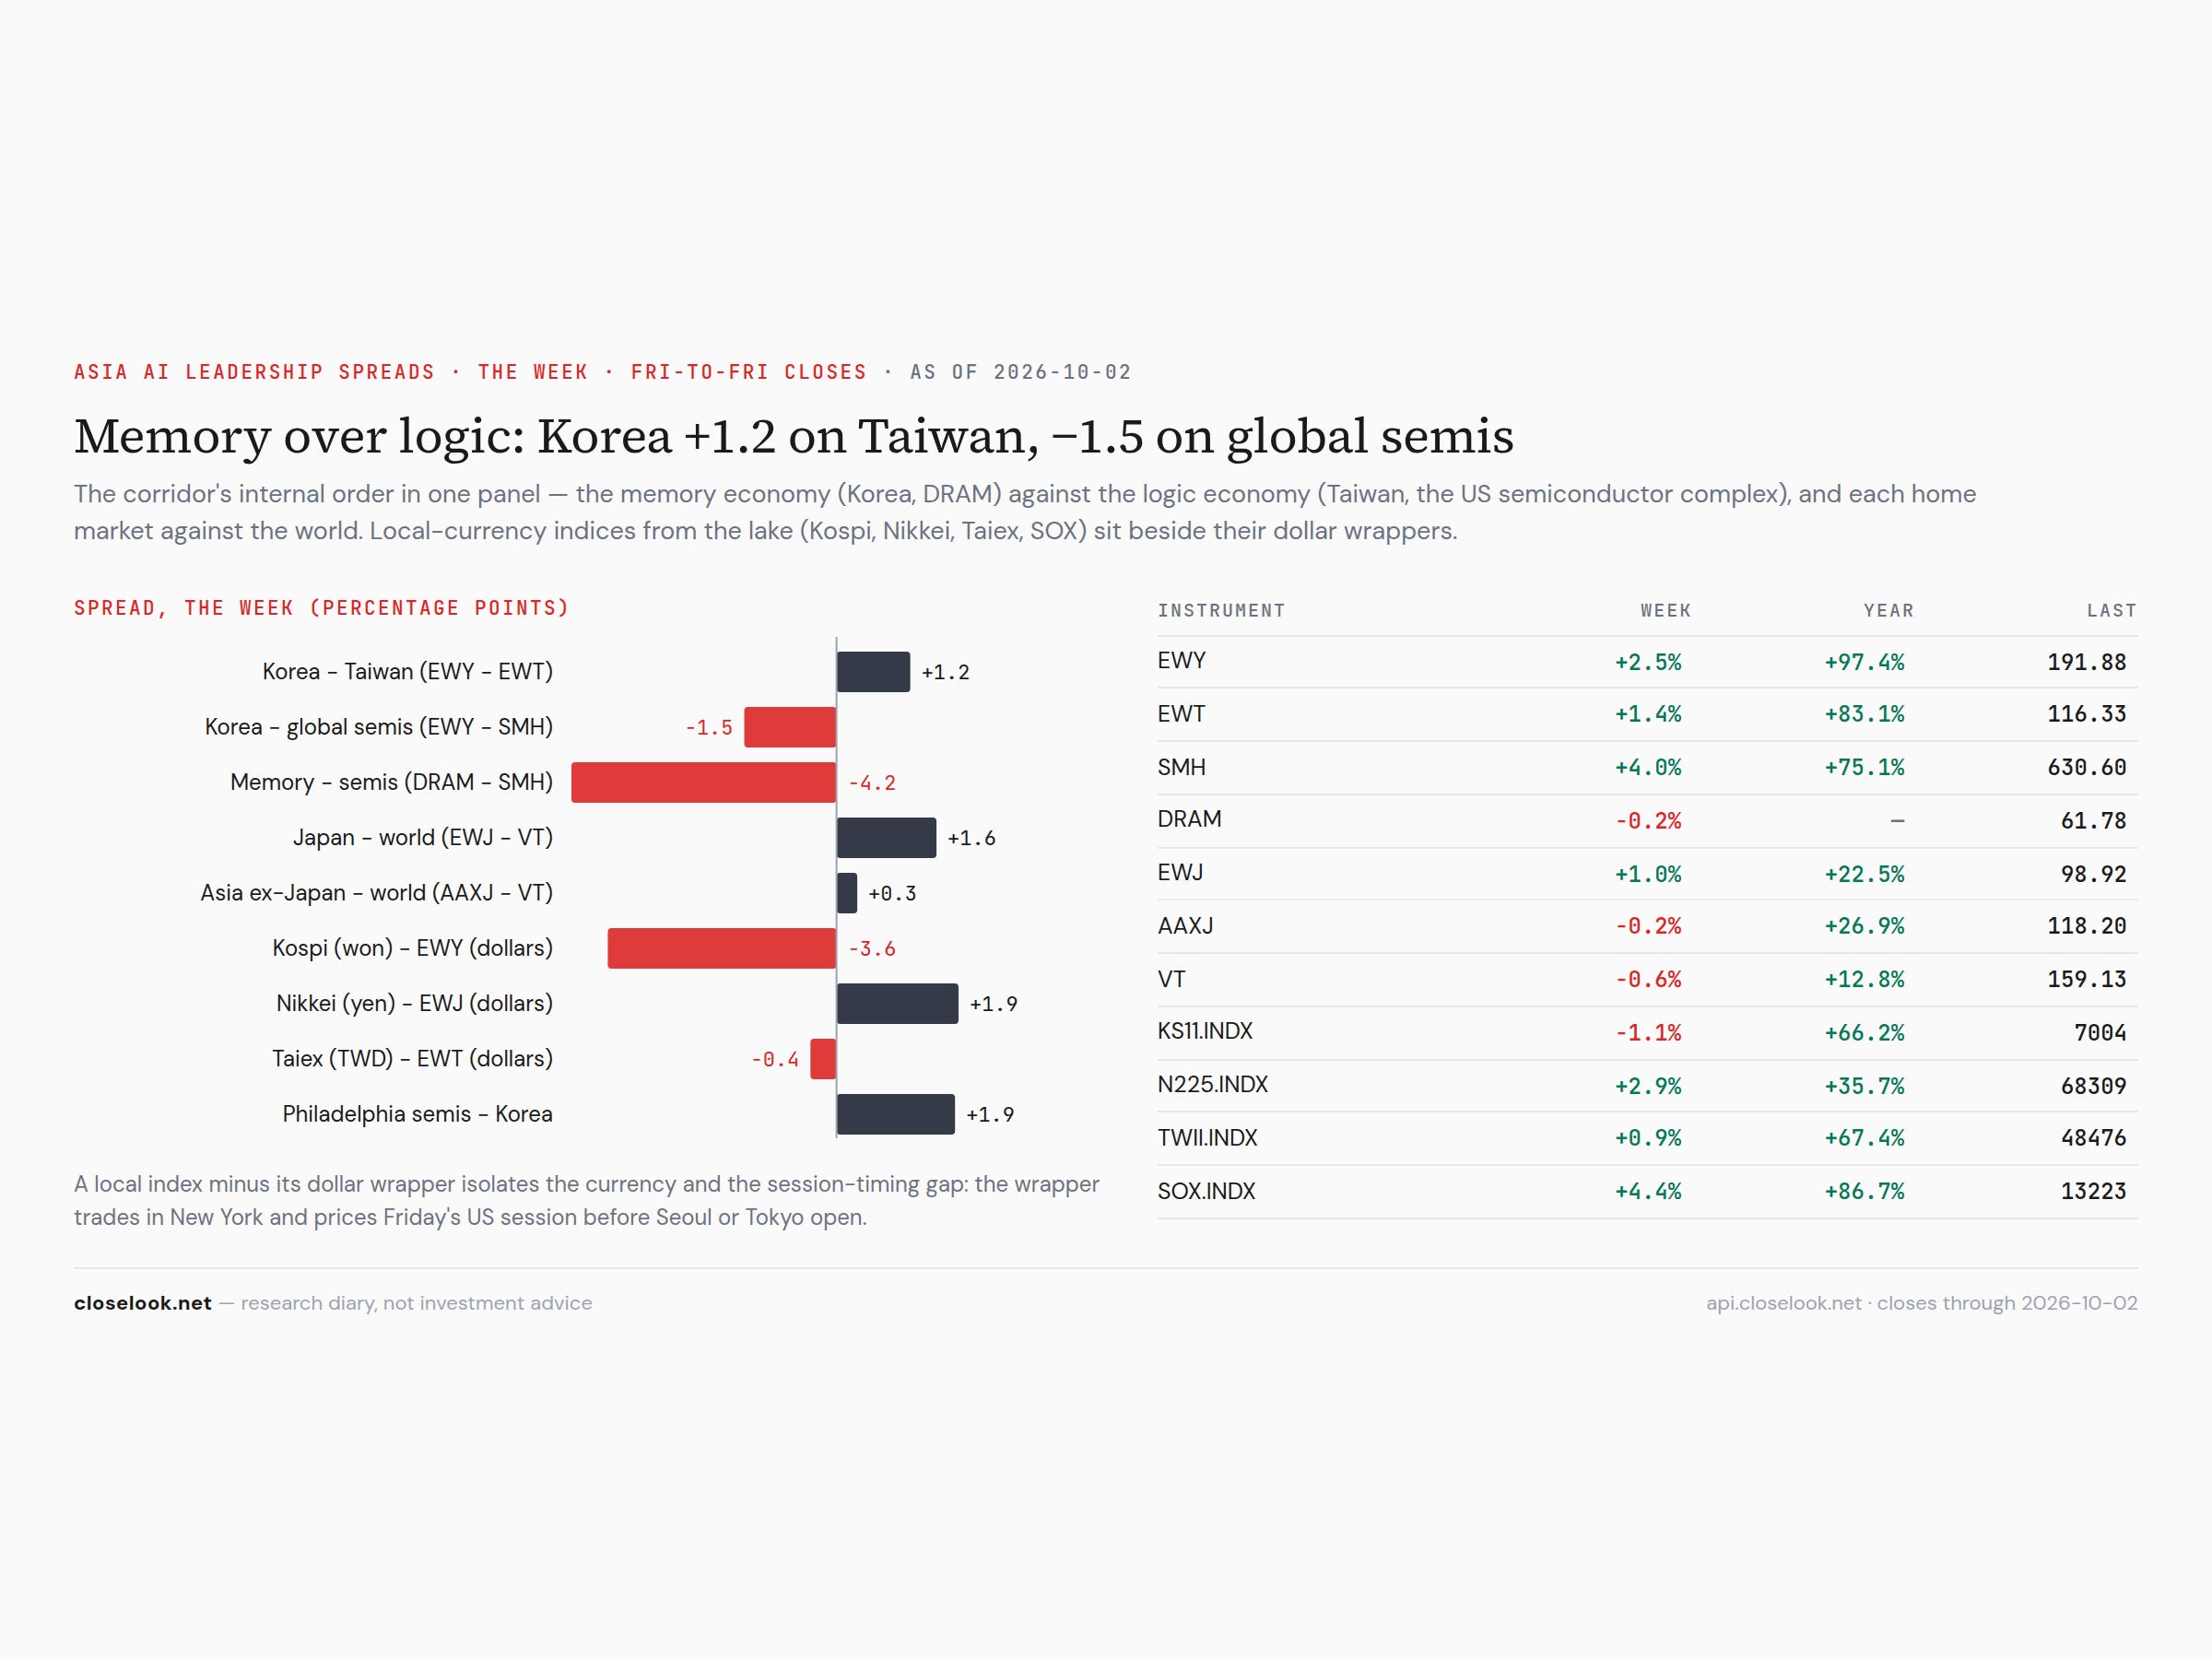
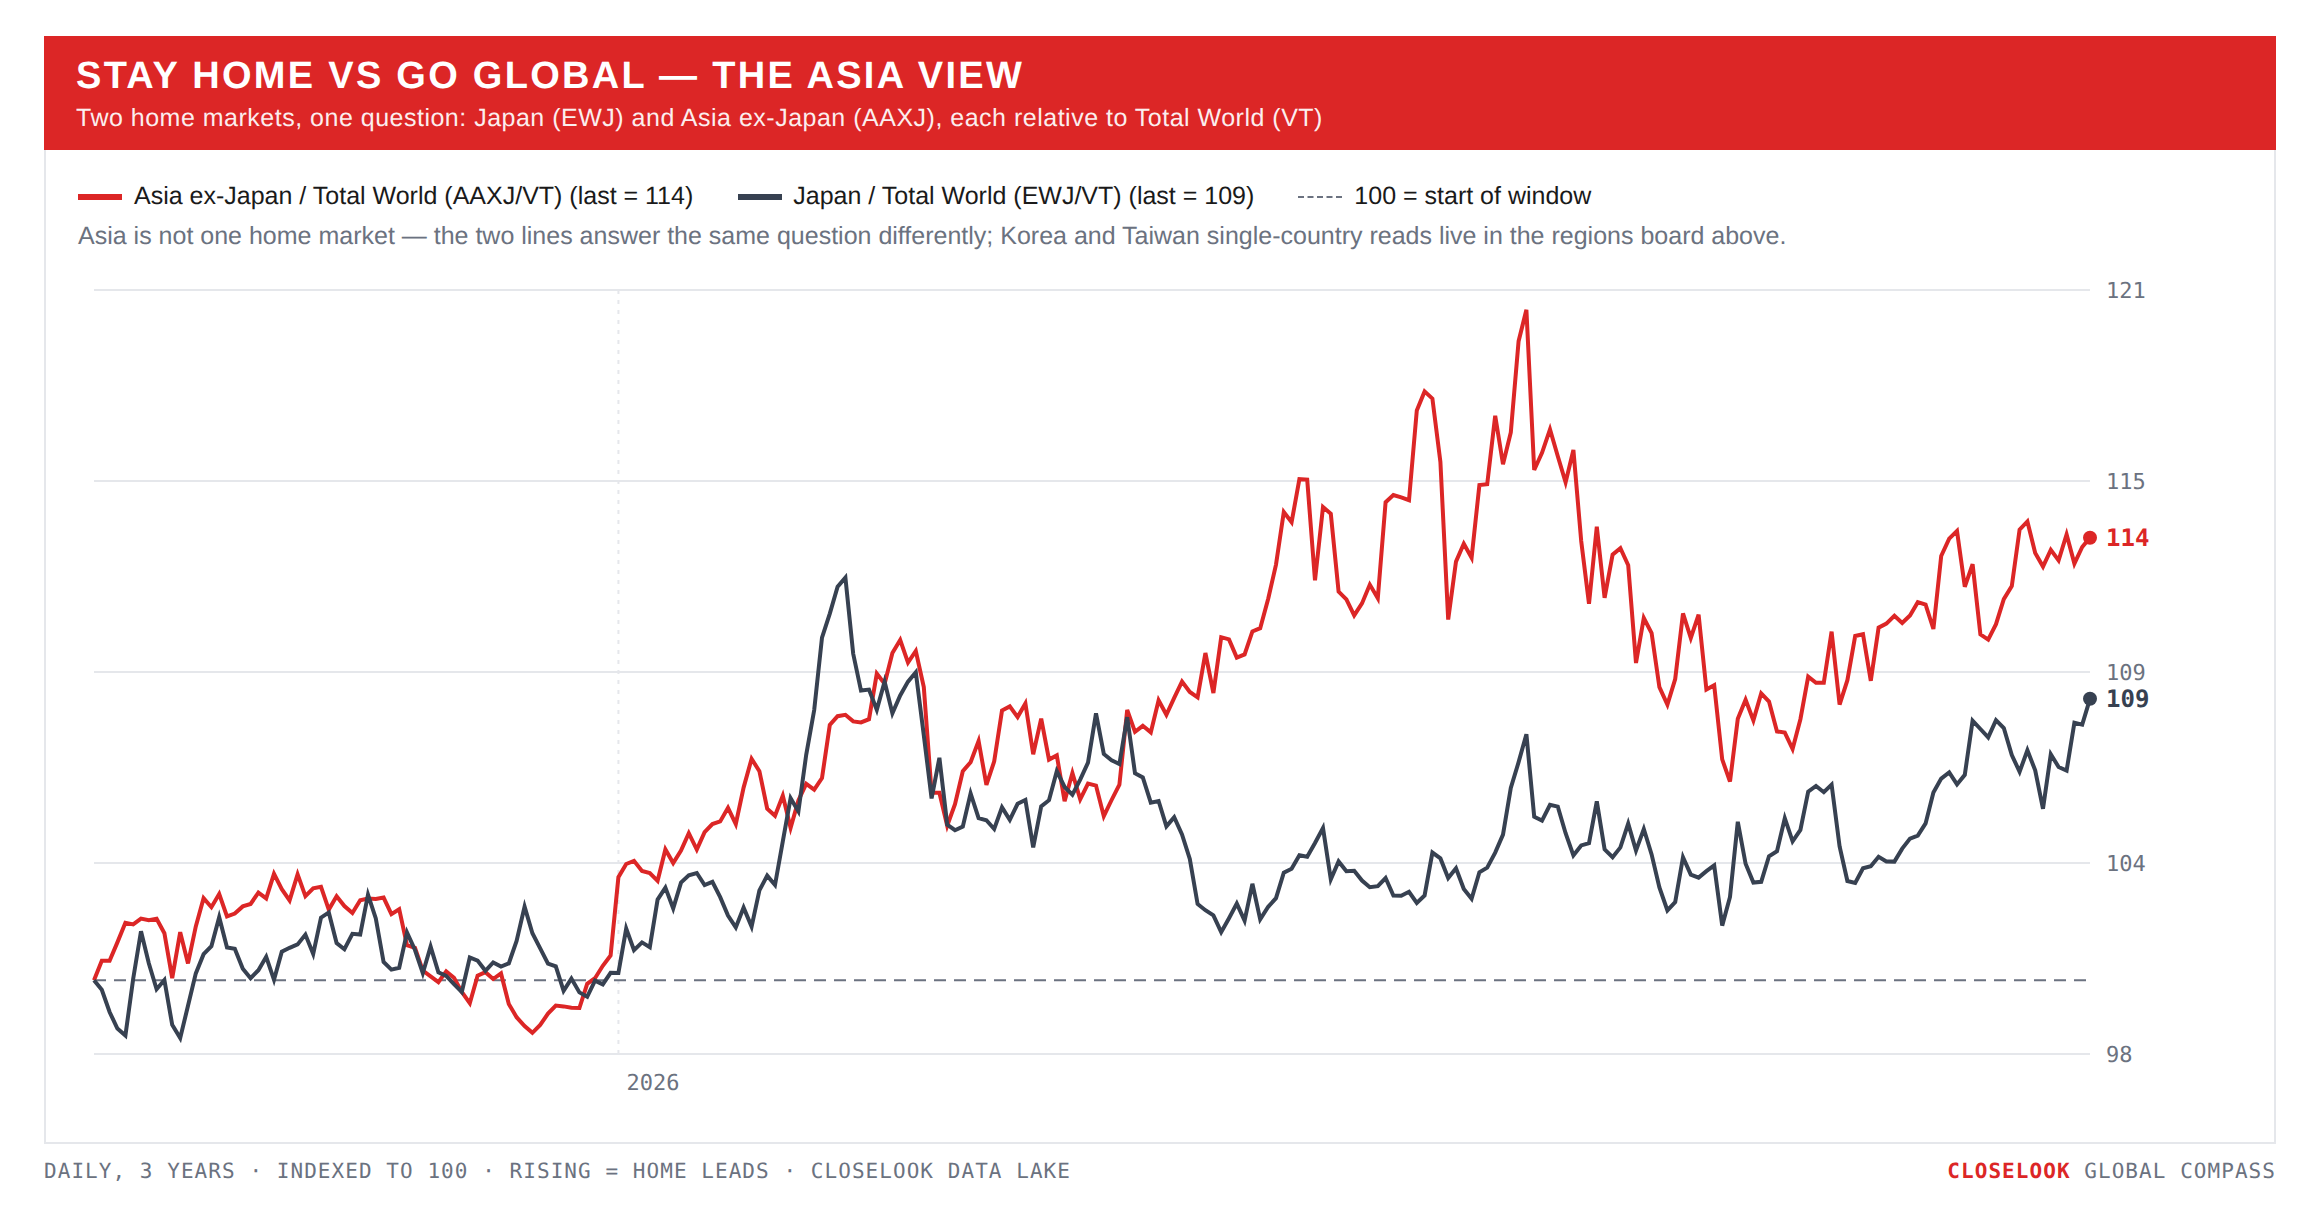
Stay home vs go global — the Asia view: the AI markets ahead, the rest behind. Taiwan: EWT +1.35% to a record close, the Taiex +0.94% to a record 48,476. Korea: EWY +2.51% to 191.88; the Kospi closed Monday 2.7% lower as it reopened after the Chuseok holiday — owed two strong New York sessions it had missed — and the tech-heavy Kosdaq rose 5.8% on the week. Japan split down the middle: the Nikkei, heavy in chip-equipment names, +2.93% to 68,309 on Micron’s record quarter (+3.3% on Thursday alone), while the broad TOPIX fell 0.91%. That is “parts of Japan” in two numbers: the AI part up three percent, the rest of Japan down one. India: −2.80%, the Nifty −2.78%, the Sensex at 71,910 on Thursday, its lowest close in a year. Hong Kong −2.19% before its holiday. The yen closed at 157.83.
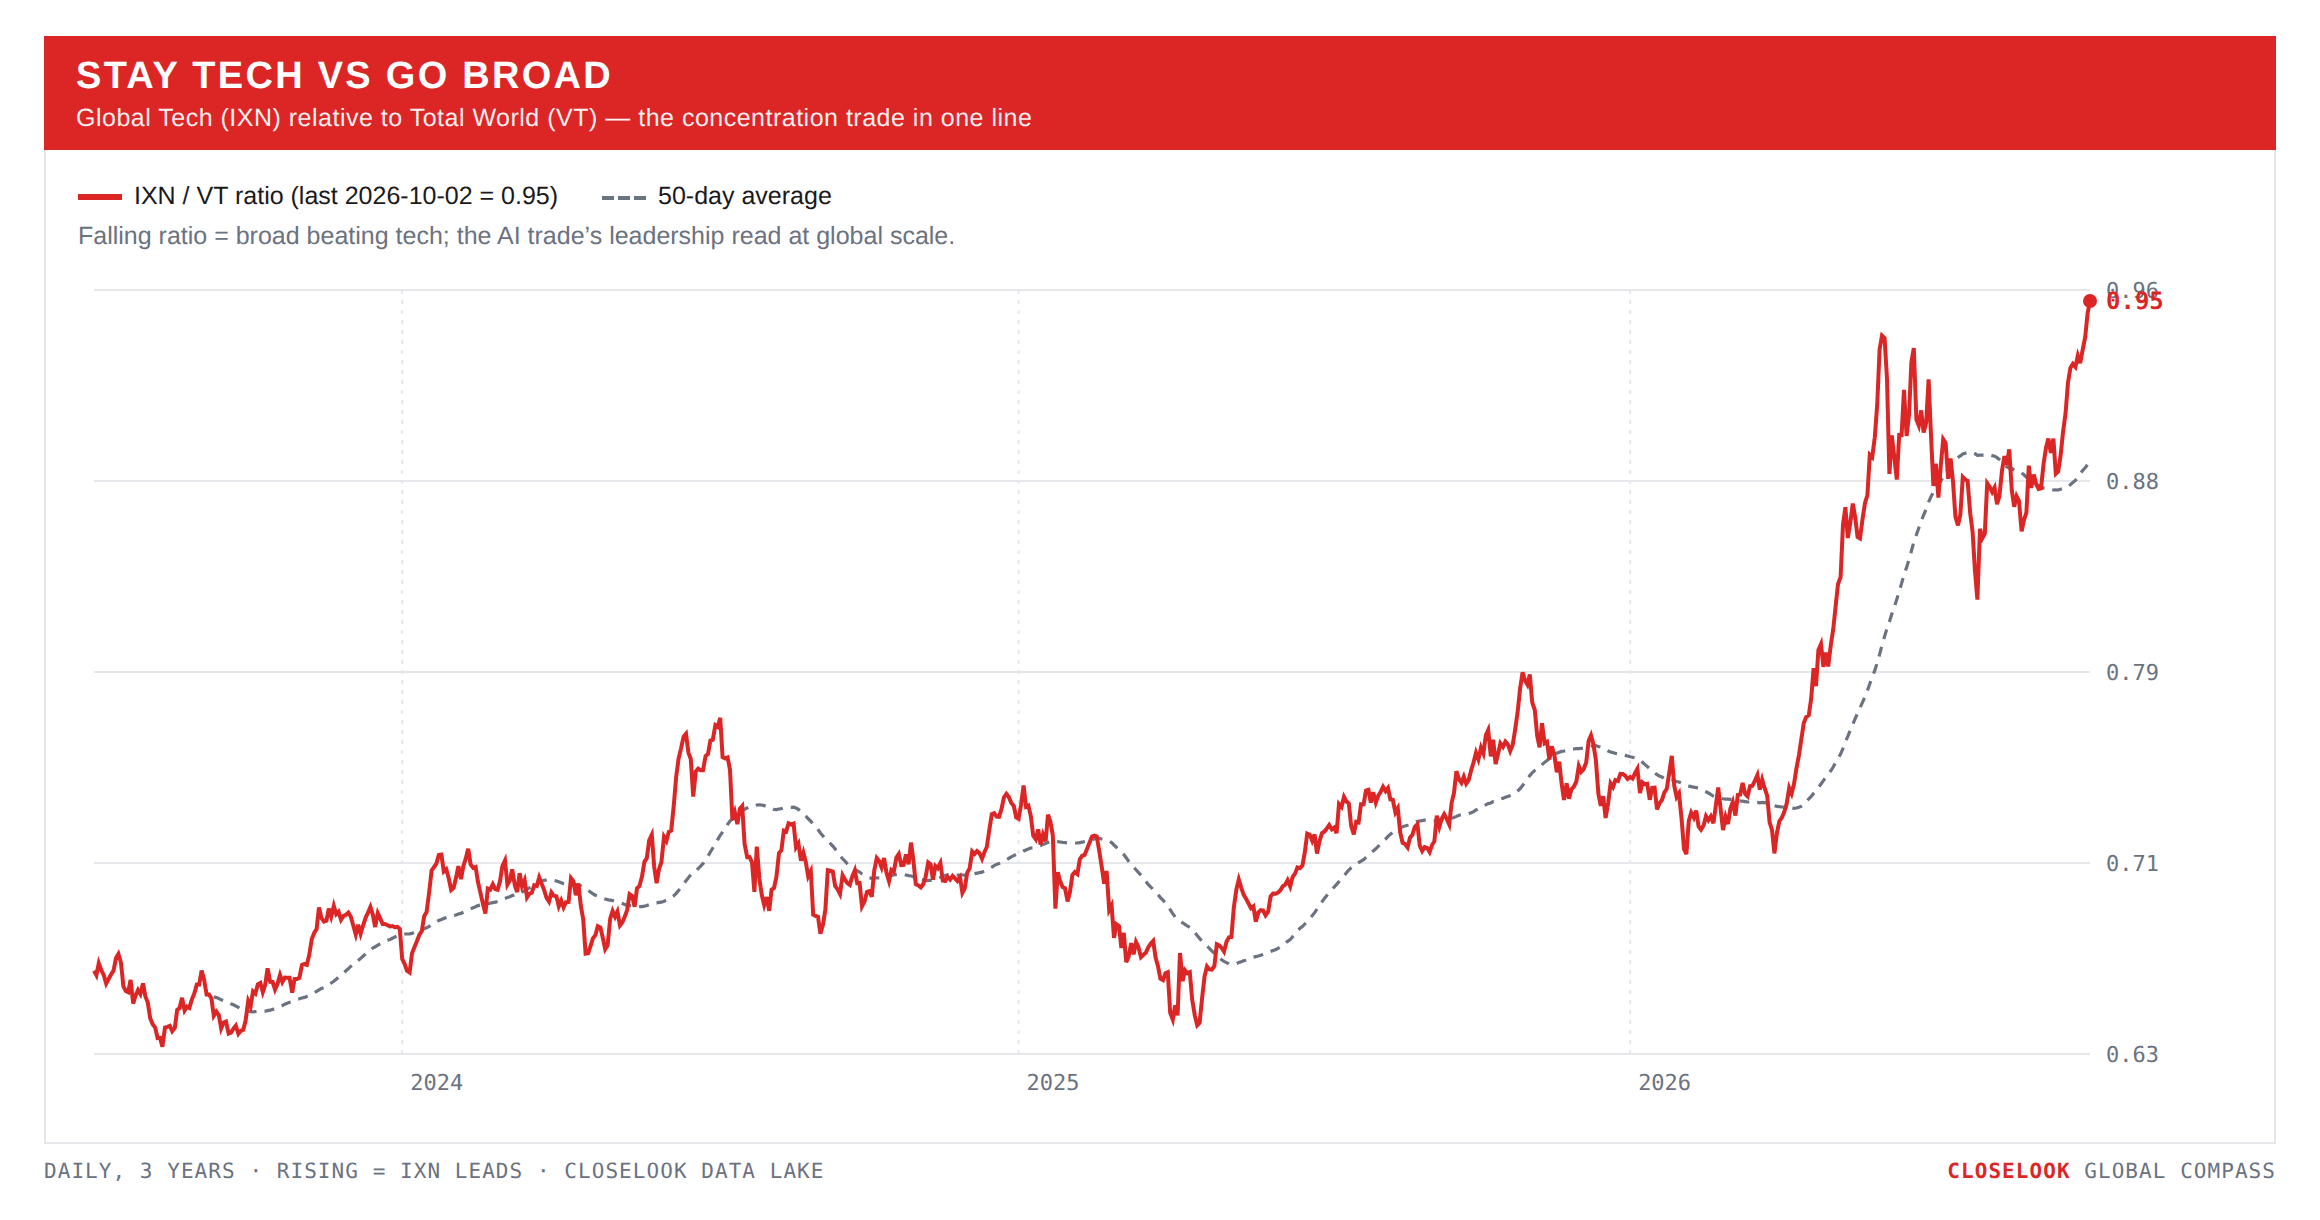
Stay tech vs go broad. Tech led again, at home and abroad. The Nasdaq 100 +1.01% against the S&P’s −0.27% and the equal-weight S&P’s −0.65%; global tech +2.00% against the world’s −0.56%. Technology was the best US sector and the best global sector for a second week, and this week both made records. The ratio of global tech to the world index is at its high of the year.
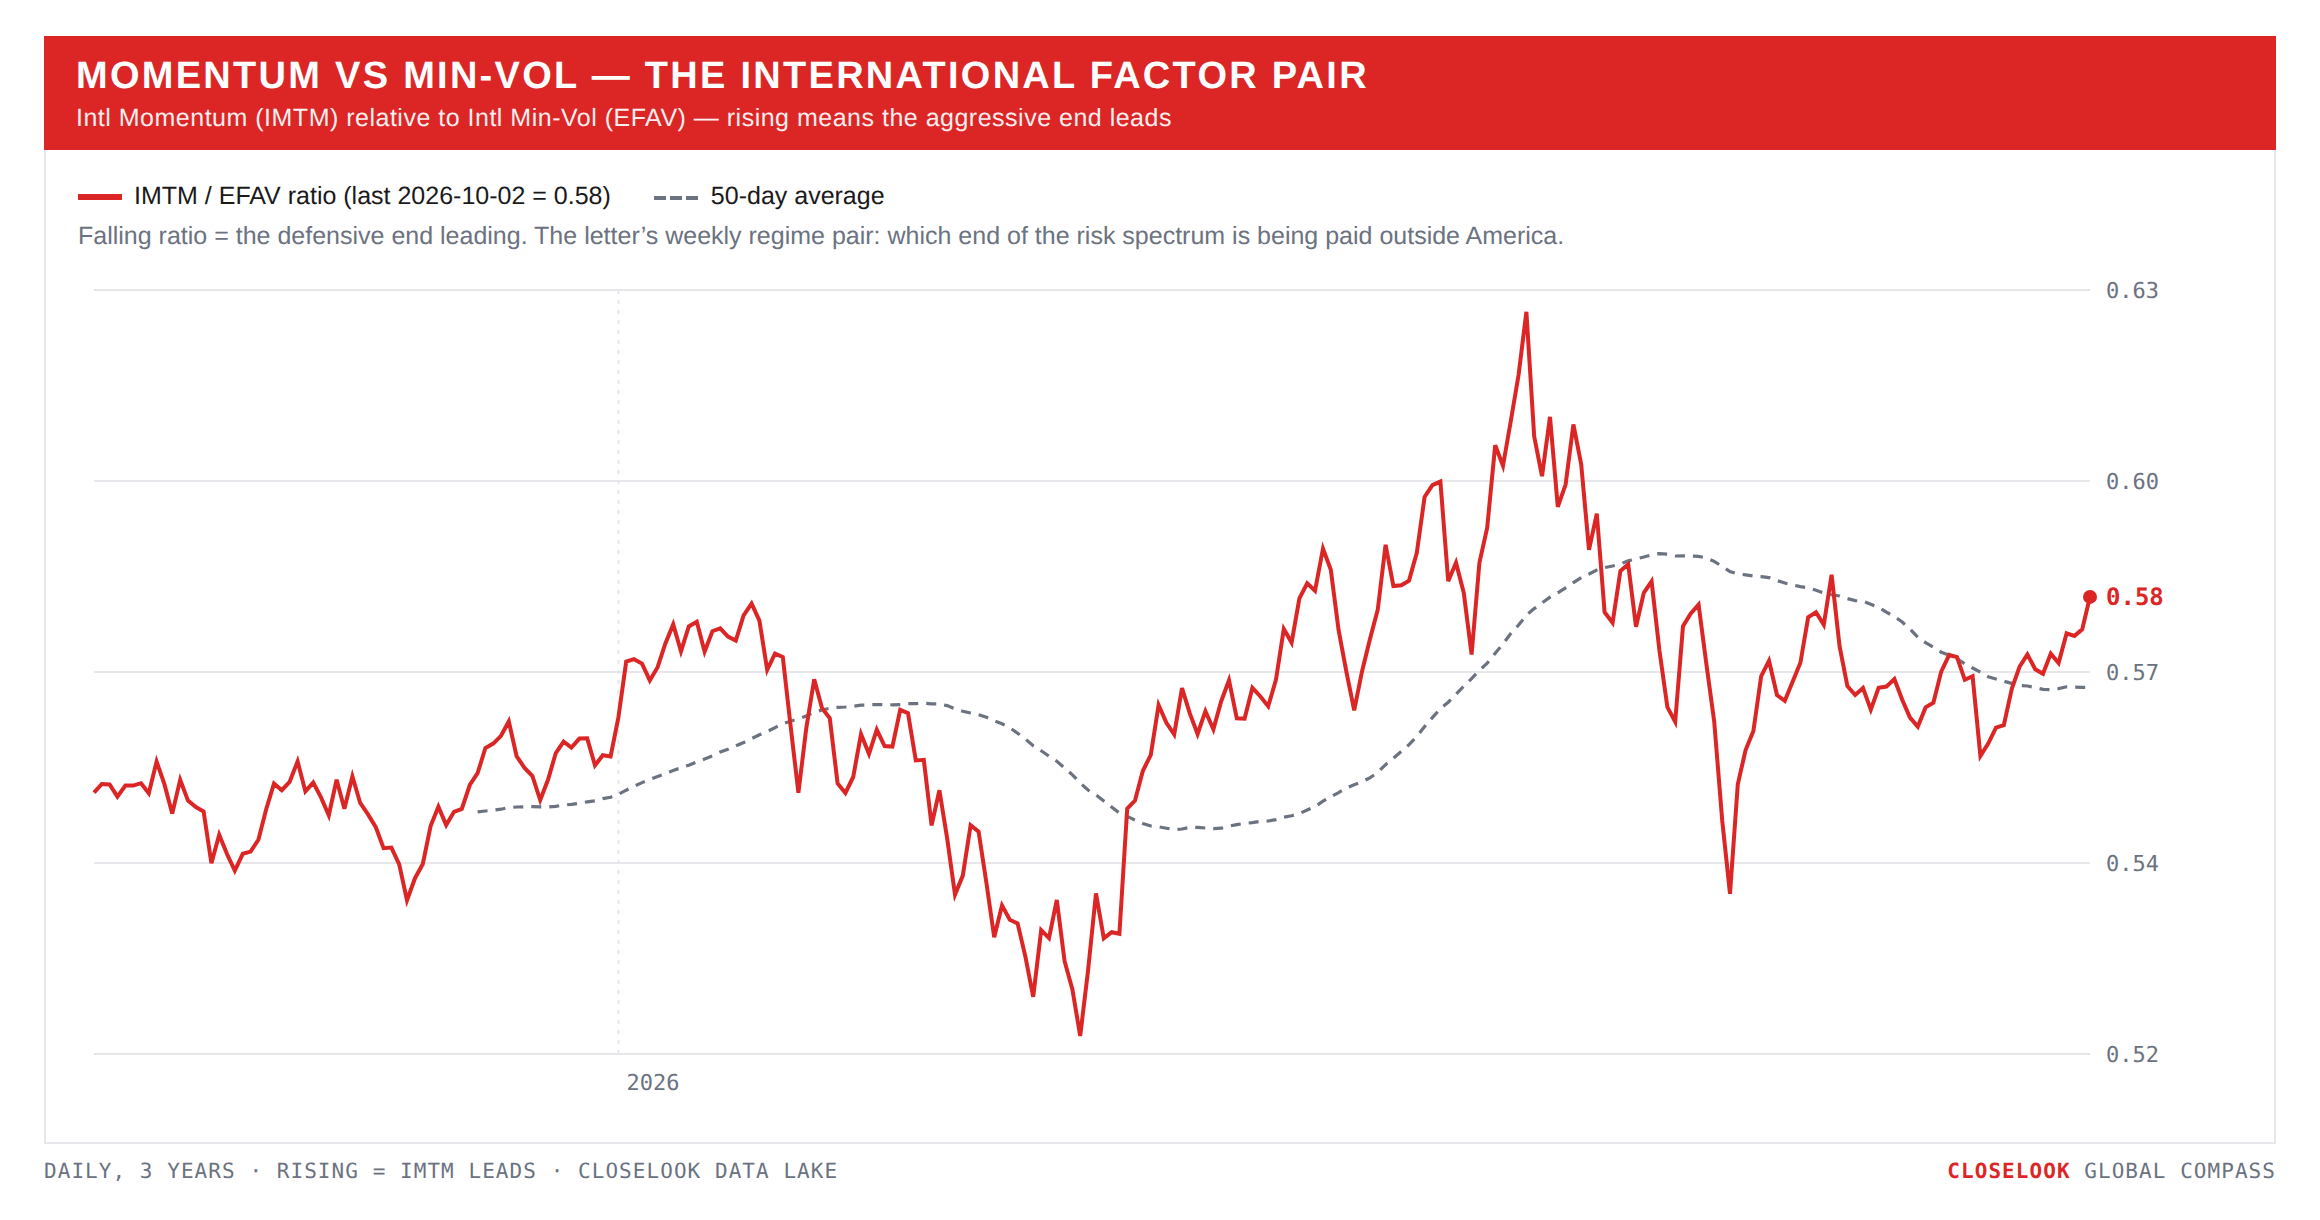
Momentum vs defensive — both down, min-vol more. International momentum fell 0.64% to 53.05; international min-vol 2.02% to 90.96; global min-vol −0.64%. On the year momentum leads +10.6% against +5.5%. The low-volatility funds are full of the utilities, staples and banks that sold off with the long end; that is why the defensive factor was not defensive this week.
One more pair: growth over value, a third week. EAFE growth +0.08% against value −2.94%. On the year value still leads, +9.9% against +6.3%, but the gap has closed from 7.1 points a week ago to 3.6. Value outside America is European banks, energy and materials; this week all three fell.
The Closelook letters — where this one sits. The house thesis, compressed: the stock market is a growing system at the aggregate level in which most constituents slowly fade while a small group massively outperforms — and that group changes dynamically; it never stays static. Own the aggregate, know the current winner group, watch for the rotation. Right now the winner group is the AI stack, and this week the map showed where it lives: in America’s technology and Asia’s chip corridor, not in Europe’s core or in India. This letter reads the map (regions, currencies, rates); Sunday’s US letter reads the tape and its levels; Sunday evening’s Hypergrowth letter reads the names.
2 · The State
The mechanism, named: the AI trade concentrated, and the dollar went with it. Put the week in order. Monday: Seoul reopened after Chuseok 2.3% lower, Samsung and SK Hynix down about 4% two days before Micron; in New York Meta started a business unit to sell its AI stack to companies and hired MongoDB’s chief executive to run it — MongoDB −18% — while Nvidia rose 2.7% in a red market and gold fell 3.8%. Tuesday: the thirty-year yield touched 5.60%, the long-bond fund broke 78; Washington opened the mortgage market to FICO’s rival score, Fair Isaac −29%. Wednesday: core inflation came in soft — 0.2% for August, 3.0% on the year against 3.3% expected — and the long-bond fund still closed lower; oil fell as the strategic reserve was offered; Micron reported a record quarter after the close, and the quarterly reset of our equal-weight indices ran on the last day of the quarter. Thursday: Tokyo +3.3% on Micron, Accenture +18% on record bookings, the euro and the dollar fund at their extremes of the year, India at its low. Friday: 29,000 jobs and 60,000 of revisions, a rally at the open, a ten-year yield higher by the close, the Nasdaq 100 at a record.
Soft inflation and a weak jobs report did not lower the long end. That is the week’s bond fact, and it says the yield is not only about the Fed’s next move. It is about how much the market wants to be paid to lend for thirty years to governments that borrow more every year — America included, but America with the growth to show for it.
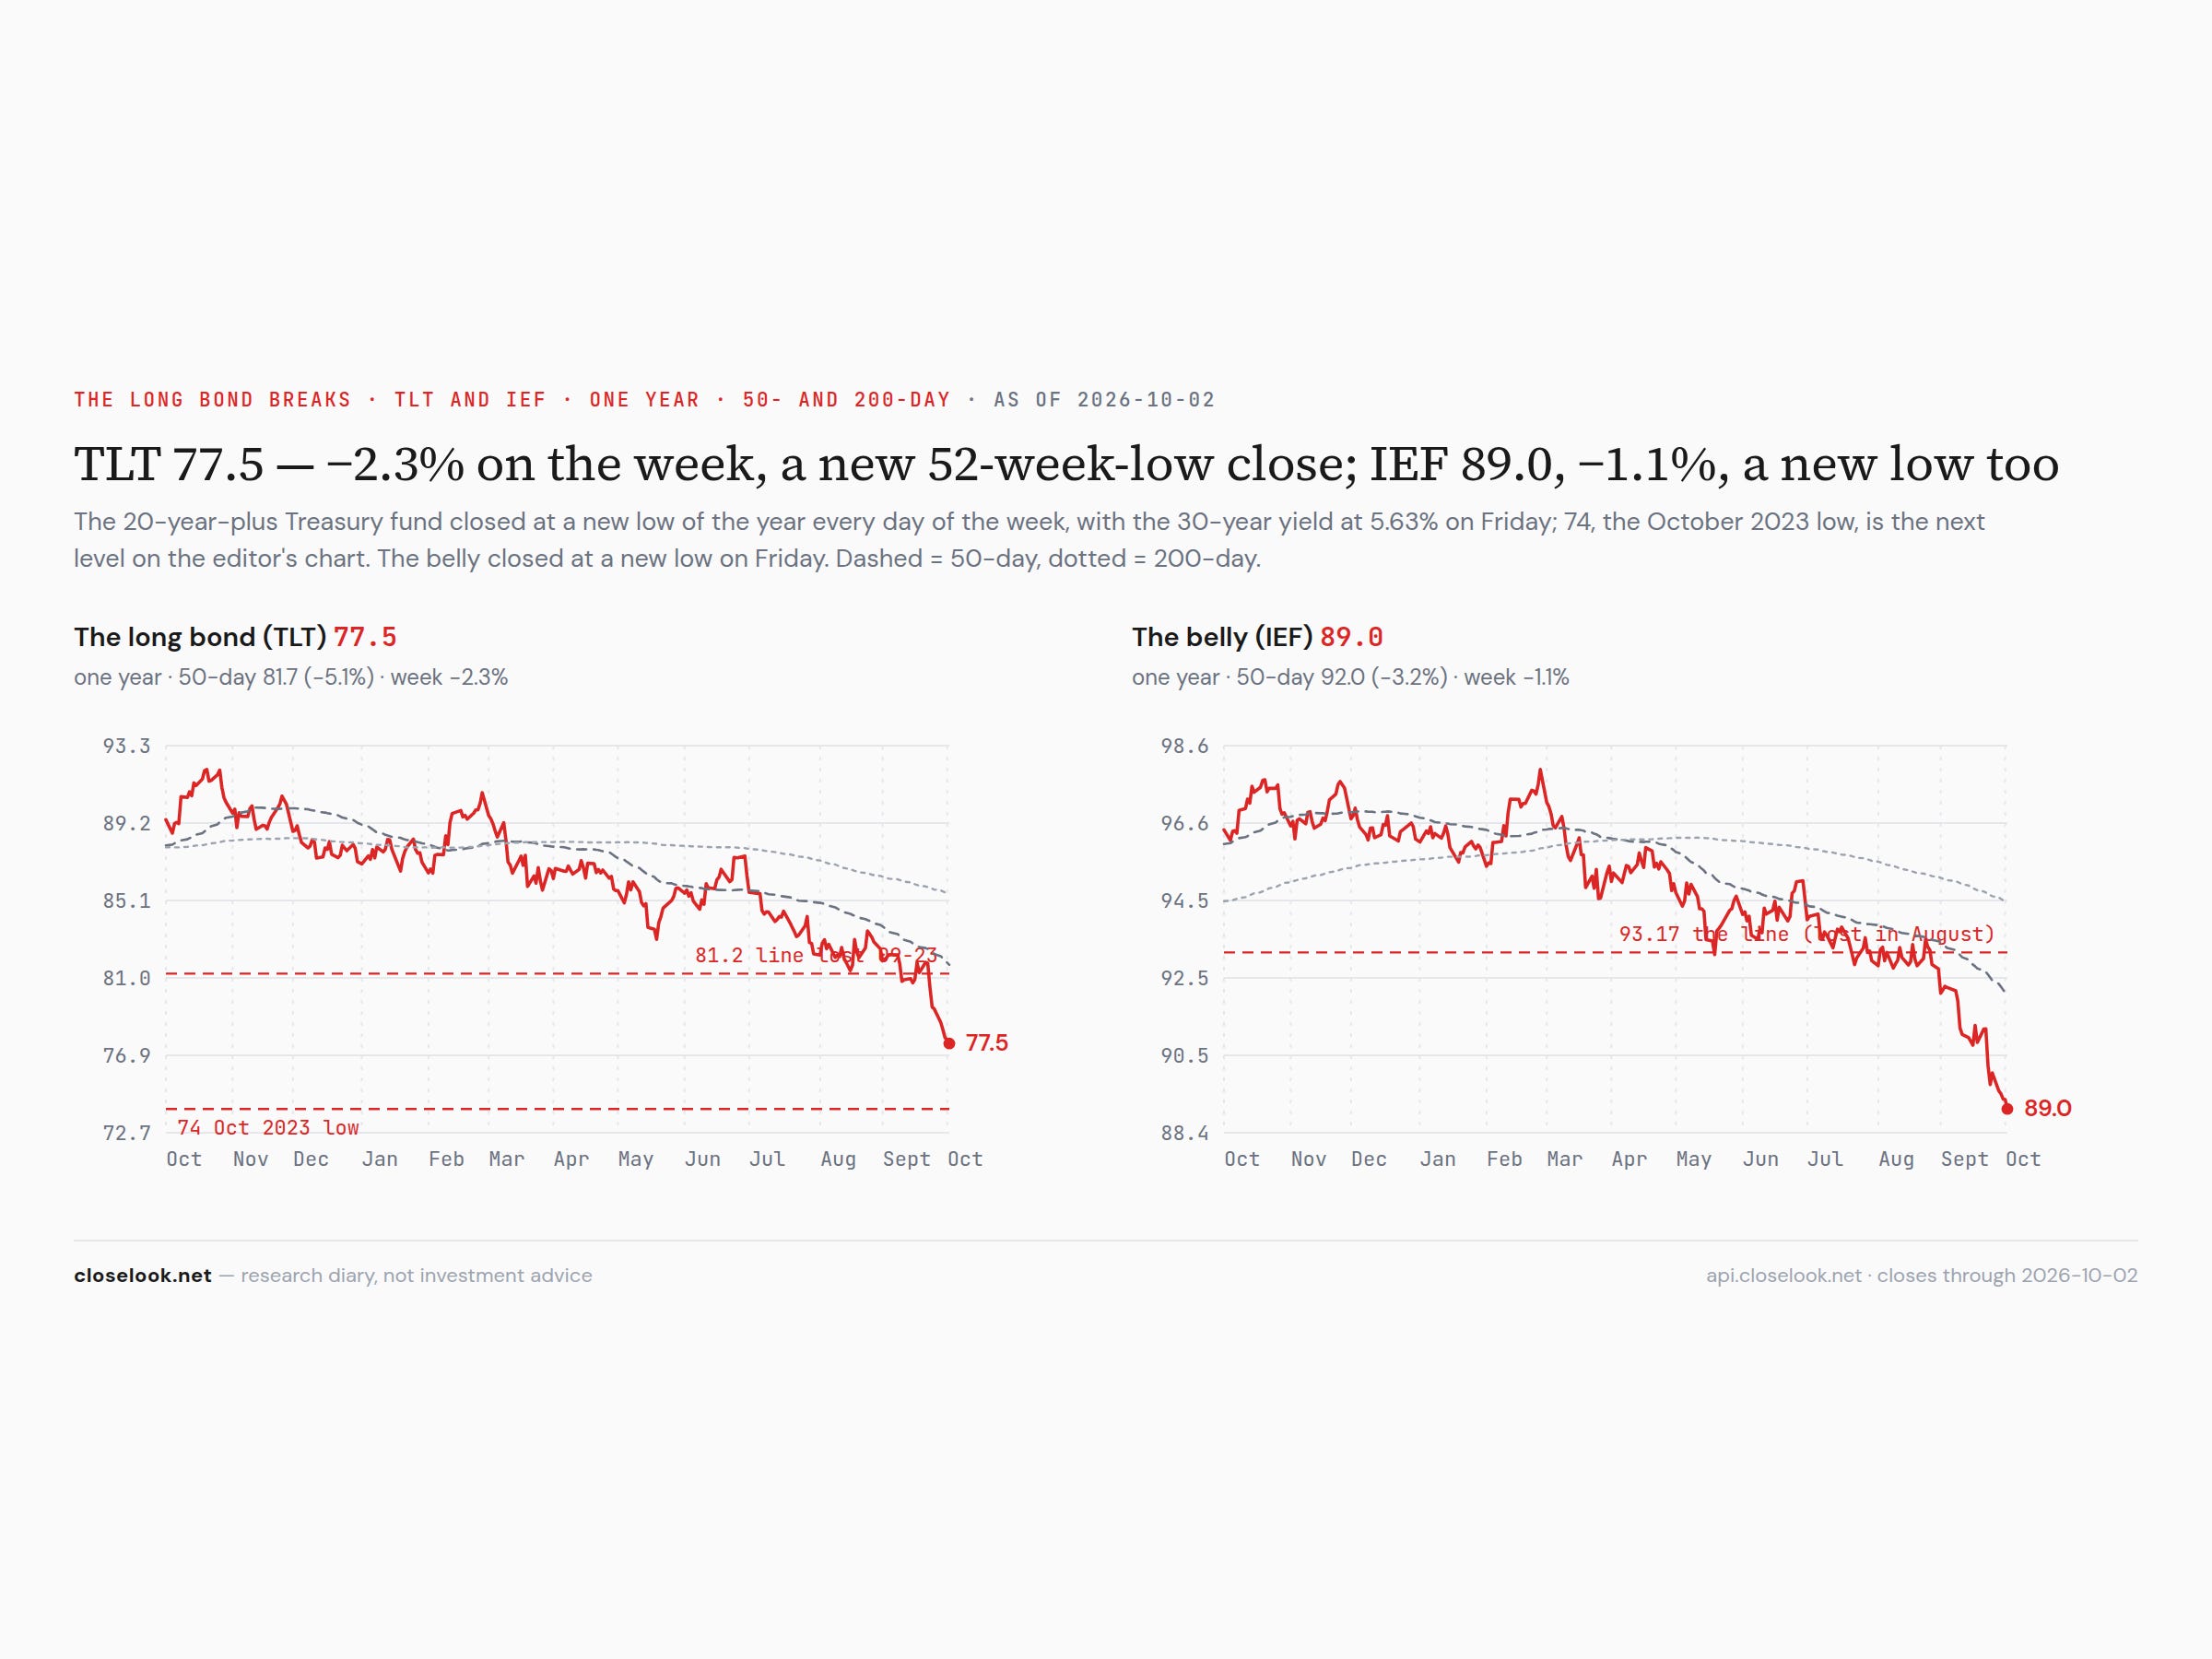
The long bond — a new low every day. TLT: 78.62 Monday, 78.23, 77.78, 77.71, 77.48 — five sessions, five new fifty-two-week-low closes, −2.32% on the week, 4.5% above 74, the October 2023 low the editor’s chart names as the next level. IEF closed at 89.05, a new low on Friday, an eighth week under the 93.17 line. Even the short end gave way: the one-to-three-year Treasury fund closed at its low of the year. The thirty-year yield closed at 5.61% and the ten-year at 5.28%, +50 basis points in twenty-one sessions.
The rate rise is global — one sentence for each reason. Friday’s Pulse laid it out country by country; here the map. The house sovereign pressure index closed at 0.59, from 0.61; the equal-weight ten-year across the board’s sovereigns is 4.38%, +33 basis points in twenty-one sessions. America: 5.28% on the ten-year, the reason growth. Britain: 5.37% and 5.89% on the thirty-year, the reason a budget the market doubts. Japan: 3.11%, the reason a central bank leaving zero. Germany: 3.47%, lower on the week. France: 4.87%, Italy 4.61%, the reason credit. The level is shared; the reason is not.
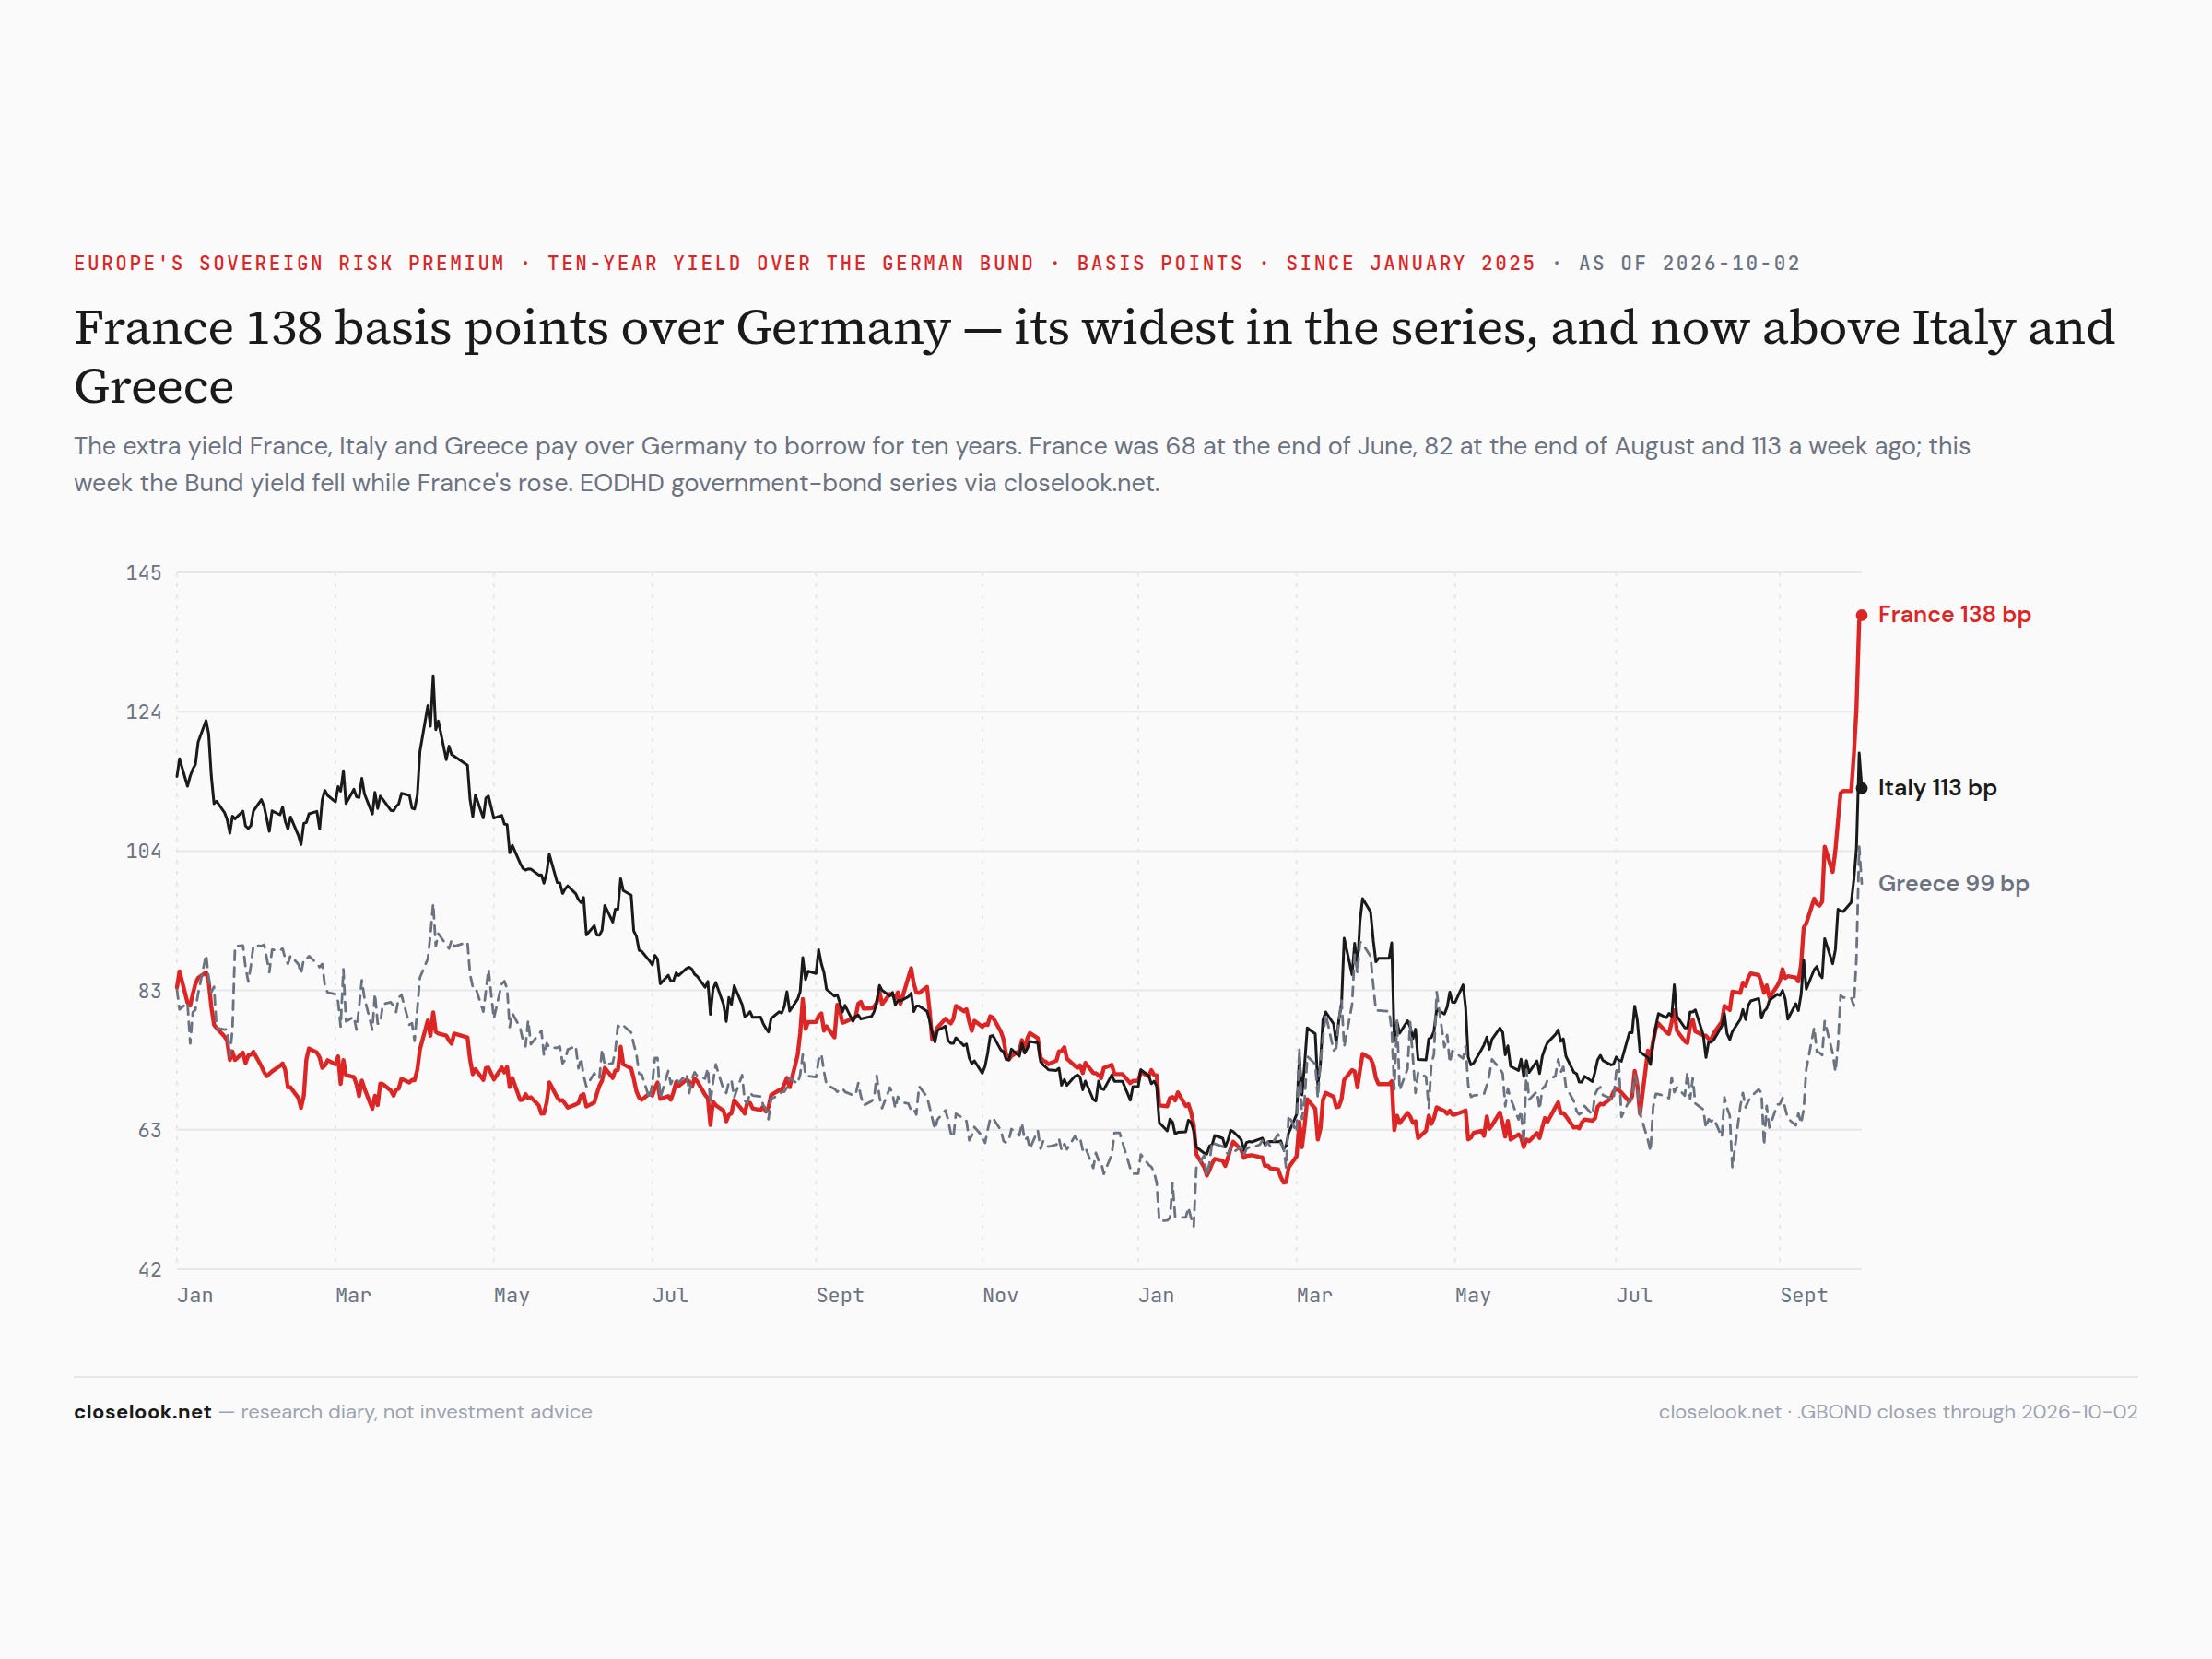
France — the spread jumped again. On the house series the French ten-year now pays 138 basis points over the Bund, from 113 a week ago, 82 at the end of August and 68 at the end of June. This week the Bund yield fell to 3.47% while France’s rose to 4.87%: money moved inside the euro area, from Paris to Frankfurt — the first week of the episode that looks like a flight to quality rather than a general sell-off. France now pays 25 basis points more than Italy to borrow for ten years, and on the chart about 40 more than Greece. The French fund is down 6.1% on the year, the CAC 9.2% under its August high. Last week this letter said the next funding crisis is more likely to start in Europe, and in Paris first. This week’s move is the kind that thesis predicts. (Editor’s note: a 25-point weekly move on the vendor series deserves a second source before it is quoted elsewhere.)
The consequence — avoid Europe, with two exceptions. This letter’s positioning, stated plainly: this diary stays away from mainland Europe’s core, and from France in particular — and this week it adds Switzerland and Britain to the list. Switzerland was the safe haven in last week’s letter; this week its fund fell 2.36% and is −1.2% on the year, a haven that does not hold value in a week like this is not one. Britain’s fund fell 2.41% with a thirty-year gilt at 5.89%. The exceptions are the growth markets: Greece and Poland, +25% and +22% on the year, with their own growth and their own repaired finances — even after a week in which both fell harder than the core. The Global ETFs book still holds a Swiss fund and a Polish one; it traded nothing this week, and the Swiss line is now the one that does not fit the letter’s map (§5). This is a diary’s positioning, not advice.
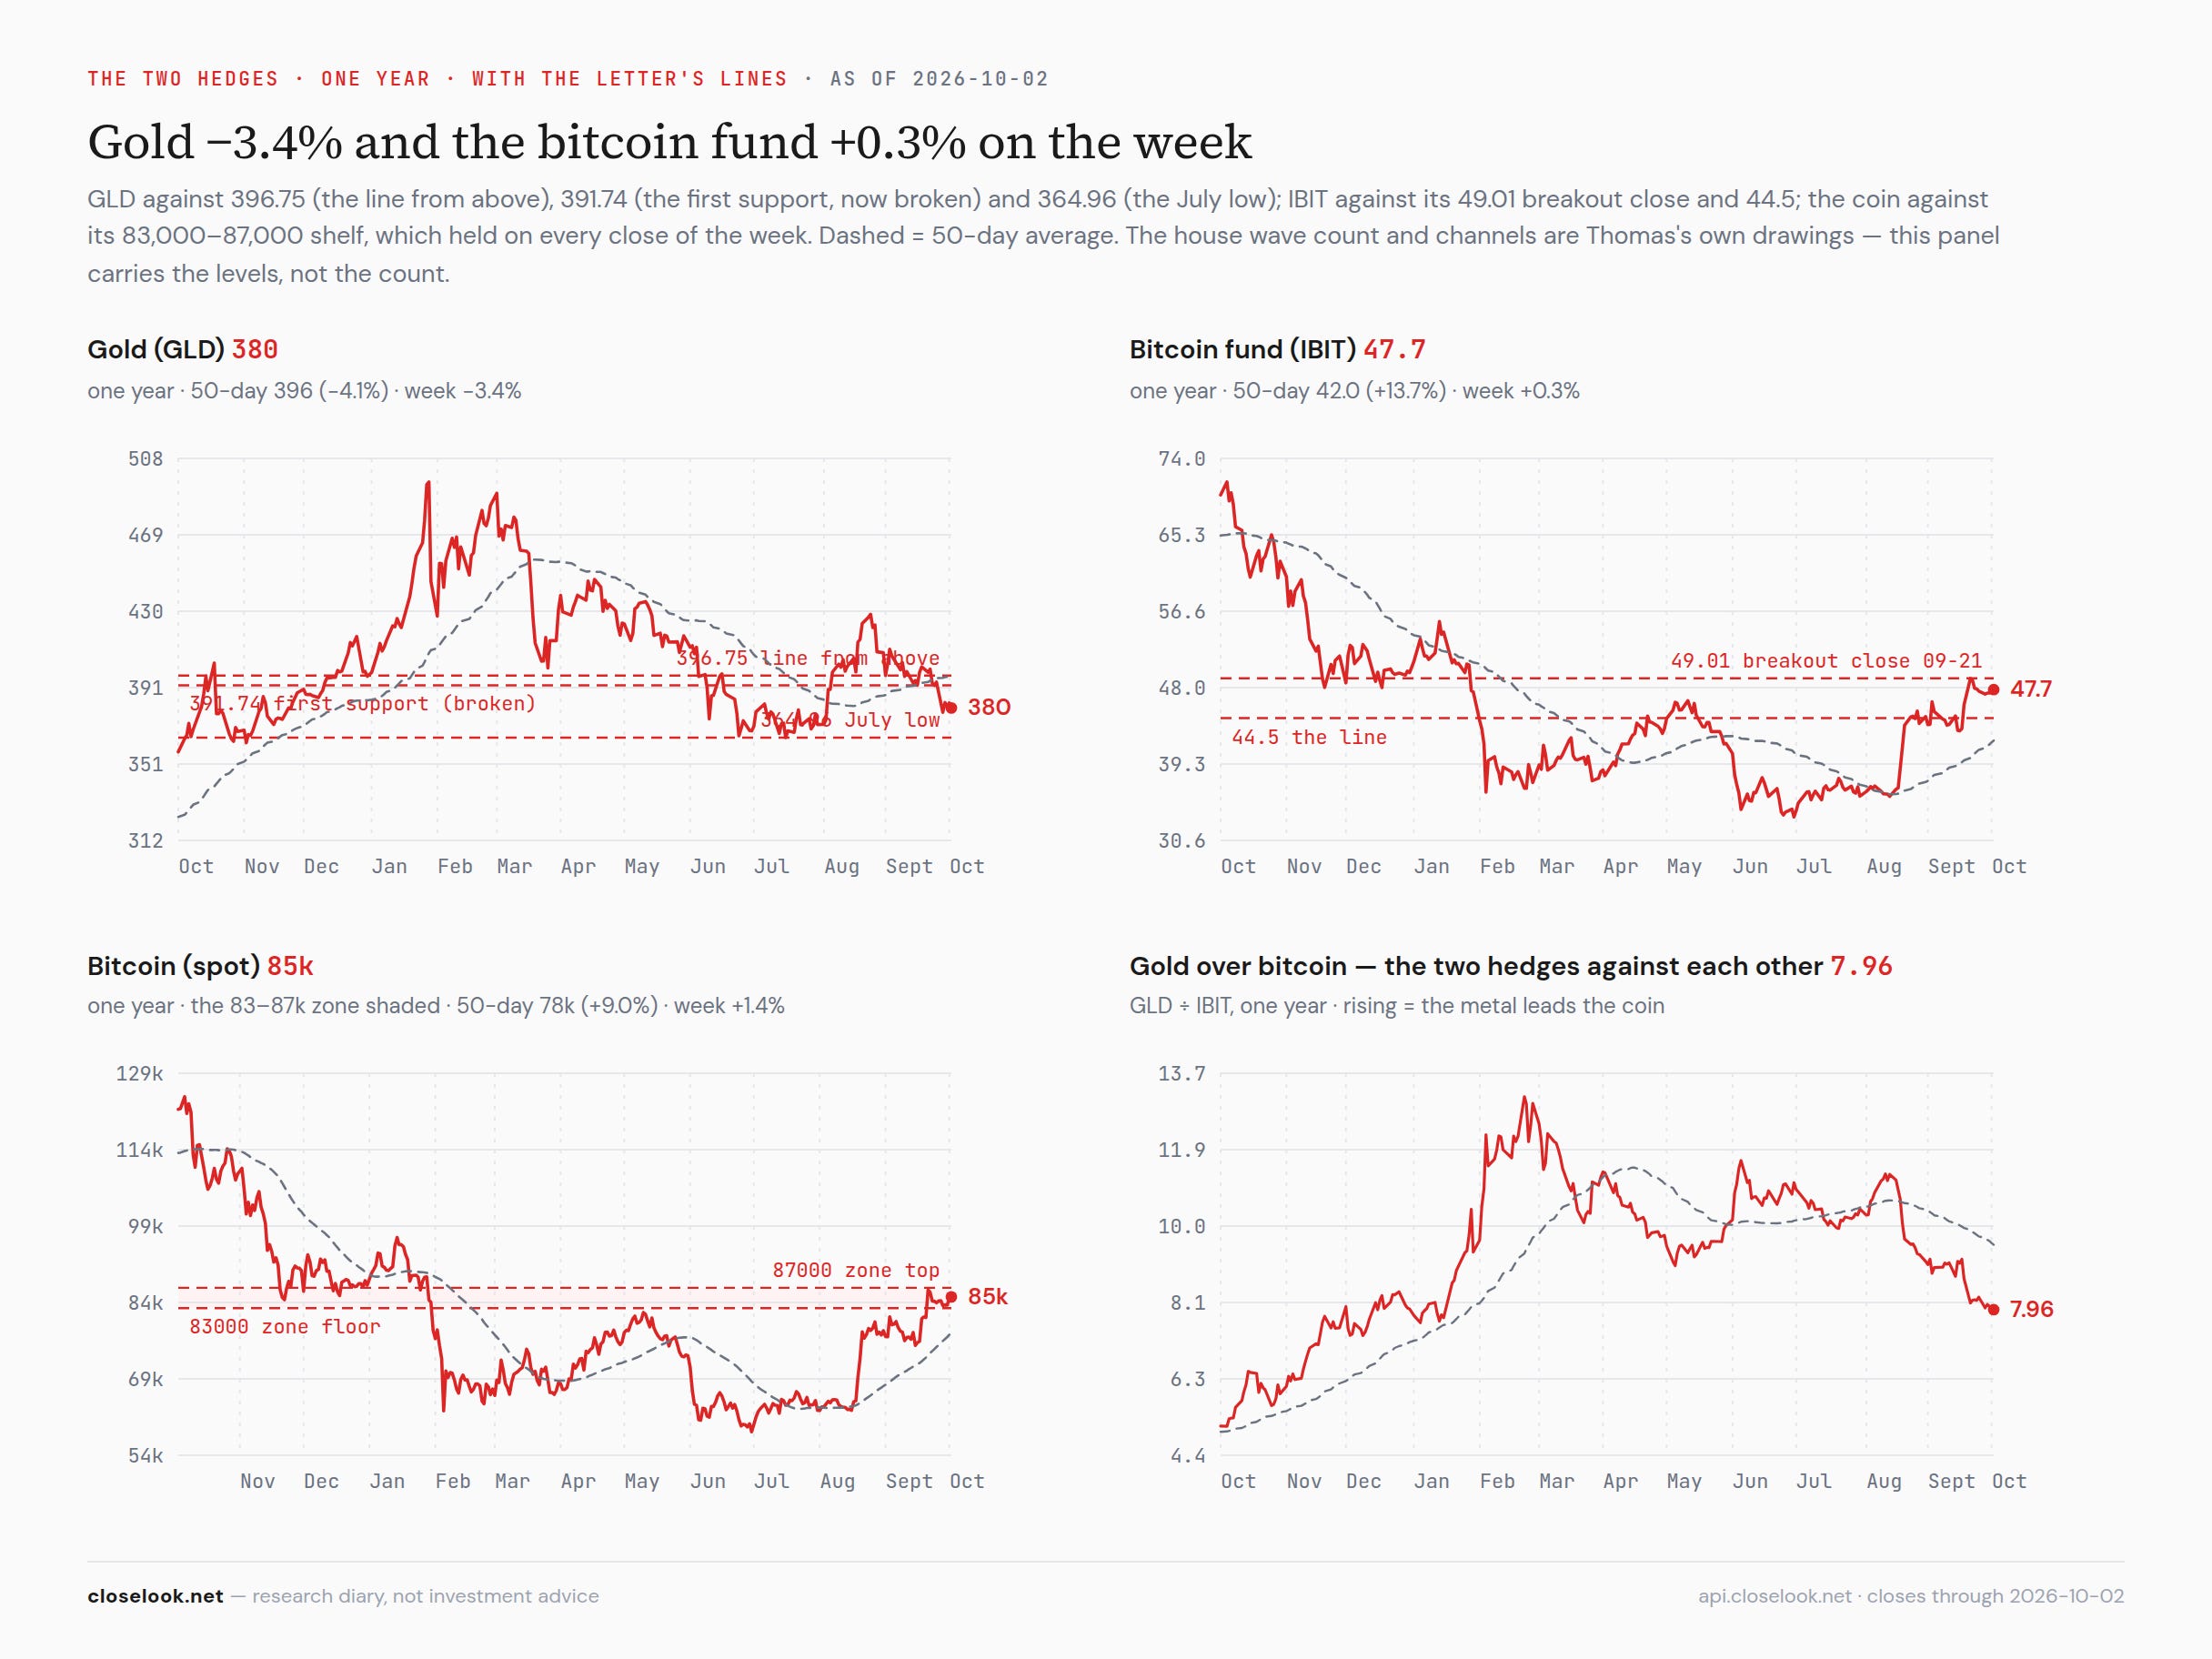
The hard assets — the coin held its shelf, the metal lost its floor. Bitcoin closed Friday at 85,206, +1.39%, with its lowest close of the week at 83,503 on Monday — above the 83,000 floor on every close. The week’s range was 82,571 to 85,600: a consolidation on the old zone’s ceiling, which is what a breakout that is going to hold usually does next. The fund closed 47.73, +0.34%. Gold did the opposite again: GLD −3.37% to 380.14, every close of the week under the 391.74 first support it broke last Thursday — Monday 377.91 after a 3.8% day — and now 4.0% above the July low of 364.96 and 23% under its January record. Silver fell 5.85%. A dollar at the high of the year and real yields at the high of the cycle are the textbook headwinds for both. The coin absorbed them; the metal did not.
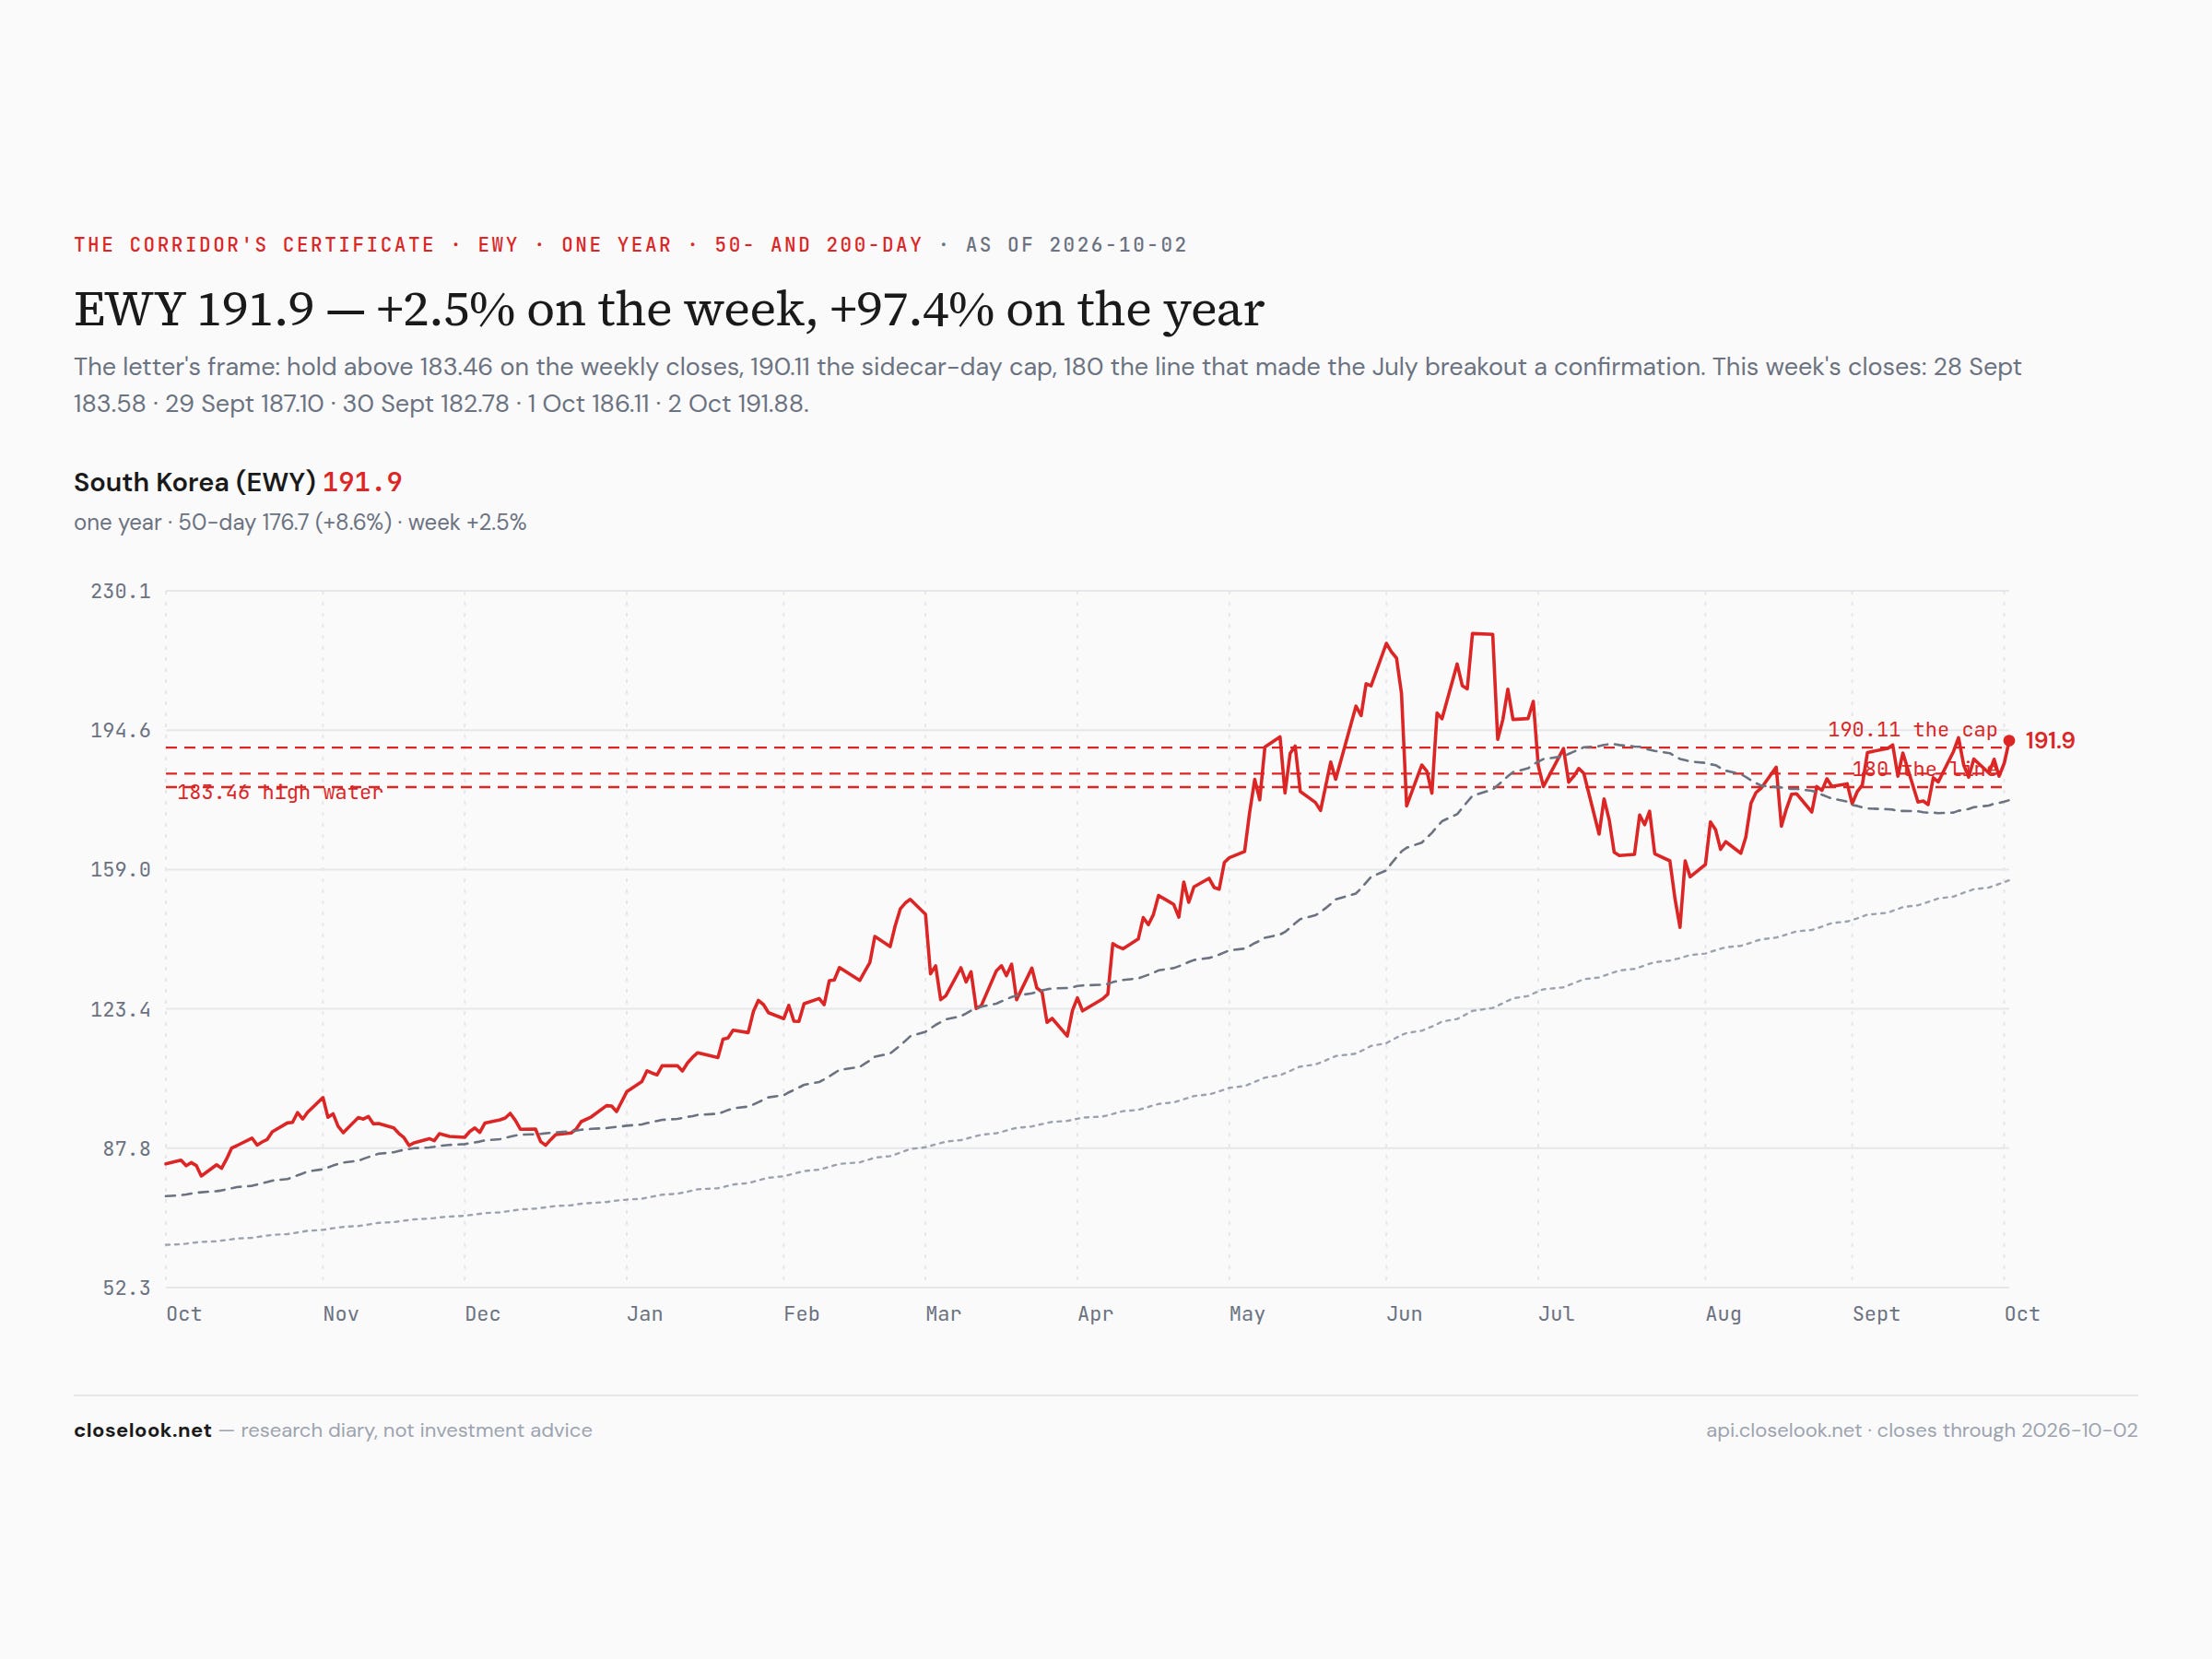
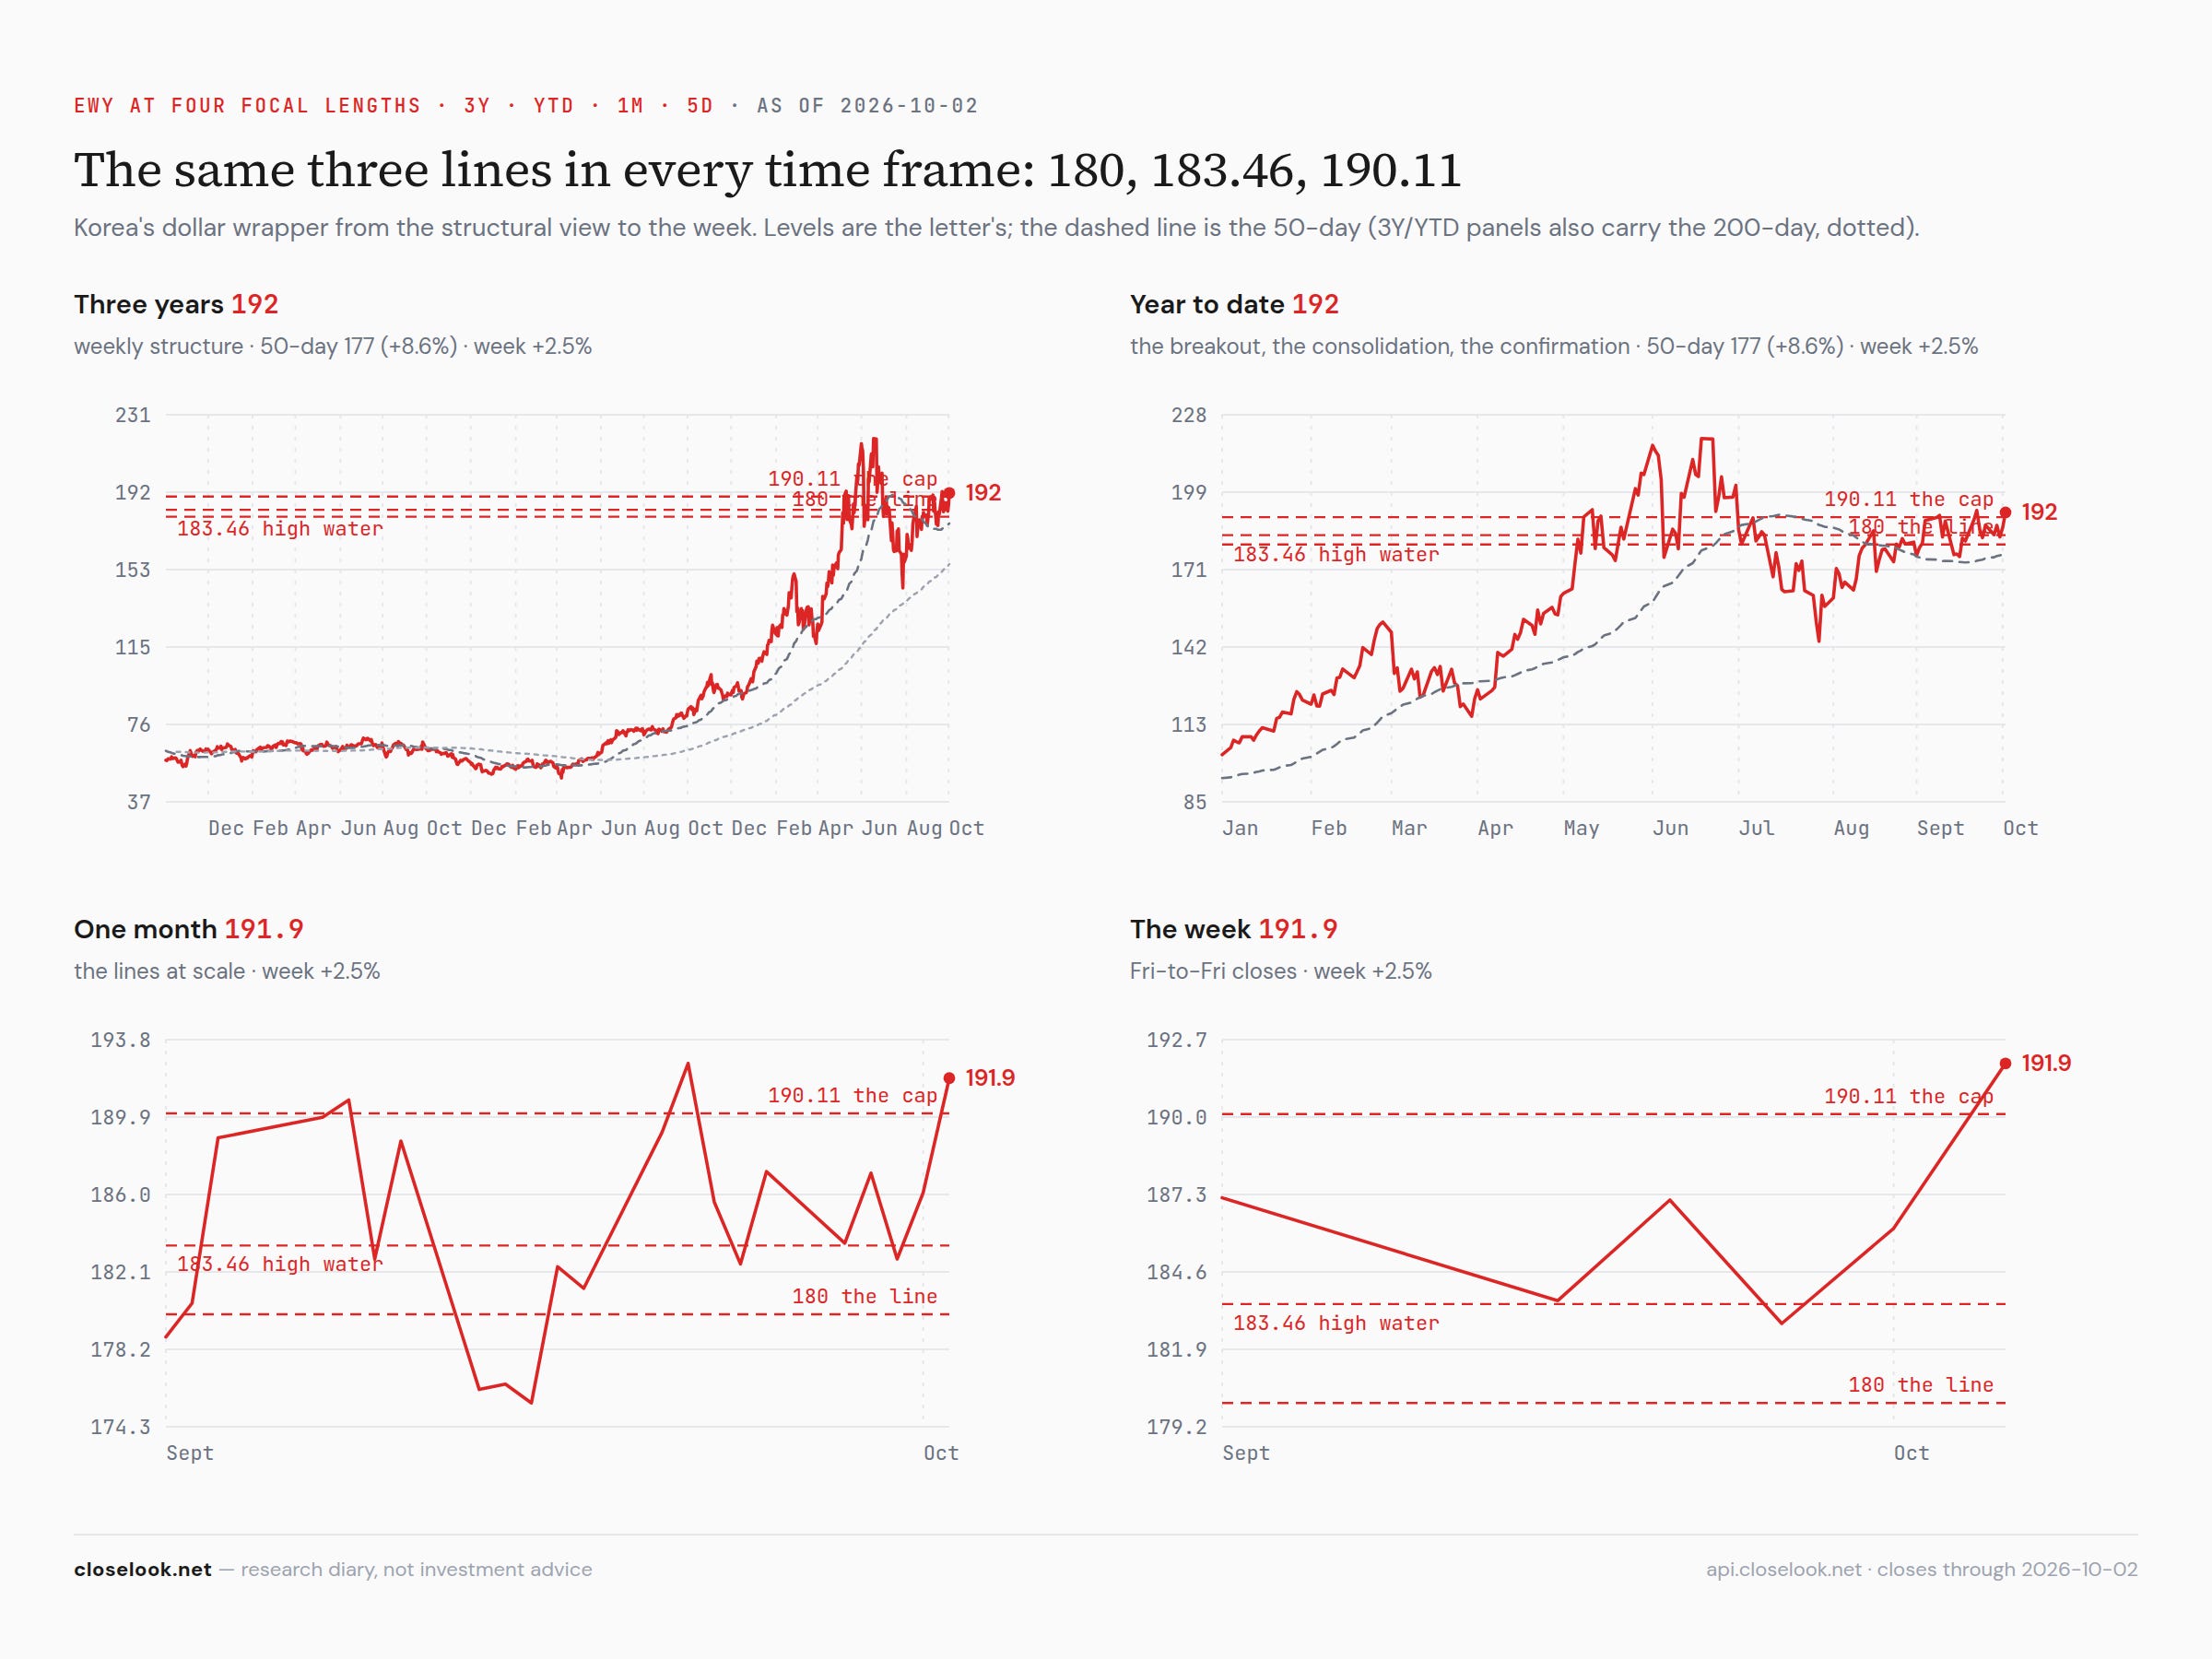
Seoul: through the cap. The fund walked 183.58 → 187.10 → 182.78 → 186.11 → 191.88 — and the weekly close is above the 190.11 cap for the first time. Last week’s frame stated the rule: a weekly close above 190.11 turns the cap into the new floor and brings the June high of 219.20 back into view. That has now happened. EWY is 12.5% under the June high and +97% on the year — the best market on the board in 2026 by a distance.
Taiwan: a record with no ceiling above it. EWT closed 116.33, a record, after 114.17, 114.11, 112.90, 112.78 — two days under 113 before Friday’s +3.1%. The Taiex closed at a record 48,476. Taiwan’s market is now, in effect, a TSMC market, and TSMC reports its September sales next week (§4). The record goes into that number, not out of it.
Europe, the voting machine and the weighing machine — both voted no. Last week Europe’s AI week was the equipment it sells to Asia. This week the equipment still rose — Euro-AI’s semi-equipment layer +9.12% — but the market around it fell, and the euro with it. The voting machine sold the core and the havens; the weighing machine bought the Bund and sold the OAT. Europe has a chip-equipment industry worth owning and a sovereign-credit problem worth avoiding, and this week they moved in opposite directions.
The macro print. Three numbers: core inflation 0.2%, payrolls 29,000, the ten-year 5.28%. The first two argued for lower rates; the third did not follow. That leaves the long end trading on supply and credit, not on the Fed, and it leaves the dollar trading on the ranking of economies, not on the next cut. For the equity map it means one thing: the market is paying for growth it can see — Micron’s record, Accenture’s bookings, the chip exporters — and selling everything that only had the rate to offer.
Hold both halves. The equity map resolved into three speeds — America’s tech and Asia’s chips at records, Europe and India down. The funding tells resolved down again — the long end at a new low every day, the dollar at a high, gold through its floor. Last week the equities rose through the bond market. This week they split along it: the markets with growth rose, the markets that depend on cheap money did not.
The structural read — the wave count, five years up, unchanged. From the October 2022 low the house count on the world ex-US reads waves 1 and 2 complete and wave 3 still progressing. It is falsified by a weekly close under 82.85 and confirmed by a weekly close above 86.41. Thursday’s 82.48 was a daily close under the line; Friday’s 83.45 put the week back above it. The count holds on the rule it was given — by 60 cents.
3 · The Outlook
The three-index read — the builder doubled again, the applications fell again. We read the three together because they are three stages of one spend: capex (Rubin Build-Out, what gets built), opex (Agentic Ecosystem, what it costs to run), applications (Agentic Winners, what gets sold on top).
Capex +5.87% on the week to 2,172.09, thirty-one of thirty-six sub-indices green, +111.3% on the year. Opex +3.25% to a record 1,738.49, +76.2%. Applications −1.06% and −8.1%. The builder rose every day of the week — 2,024.39, 2,055.57, 2,066.04, 2,112.51, 2,172.09 — through the quarterly reset of its weights on Wednesday. The opex index closed the week at its high.
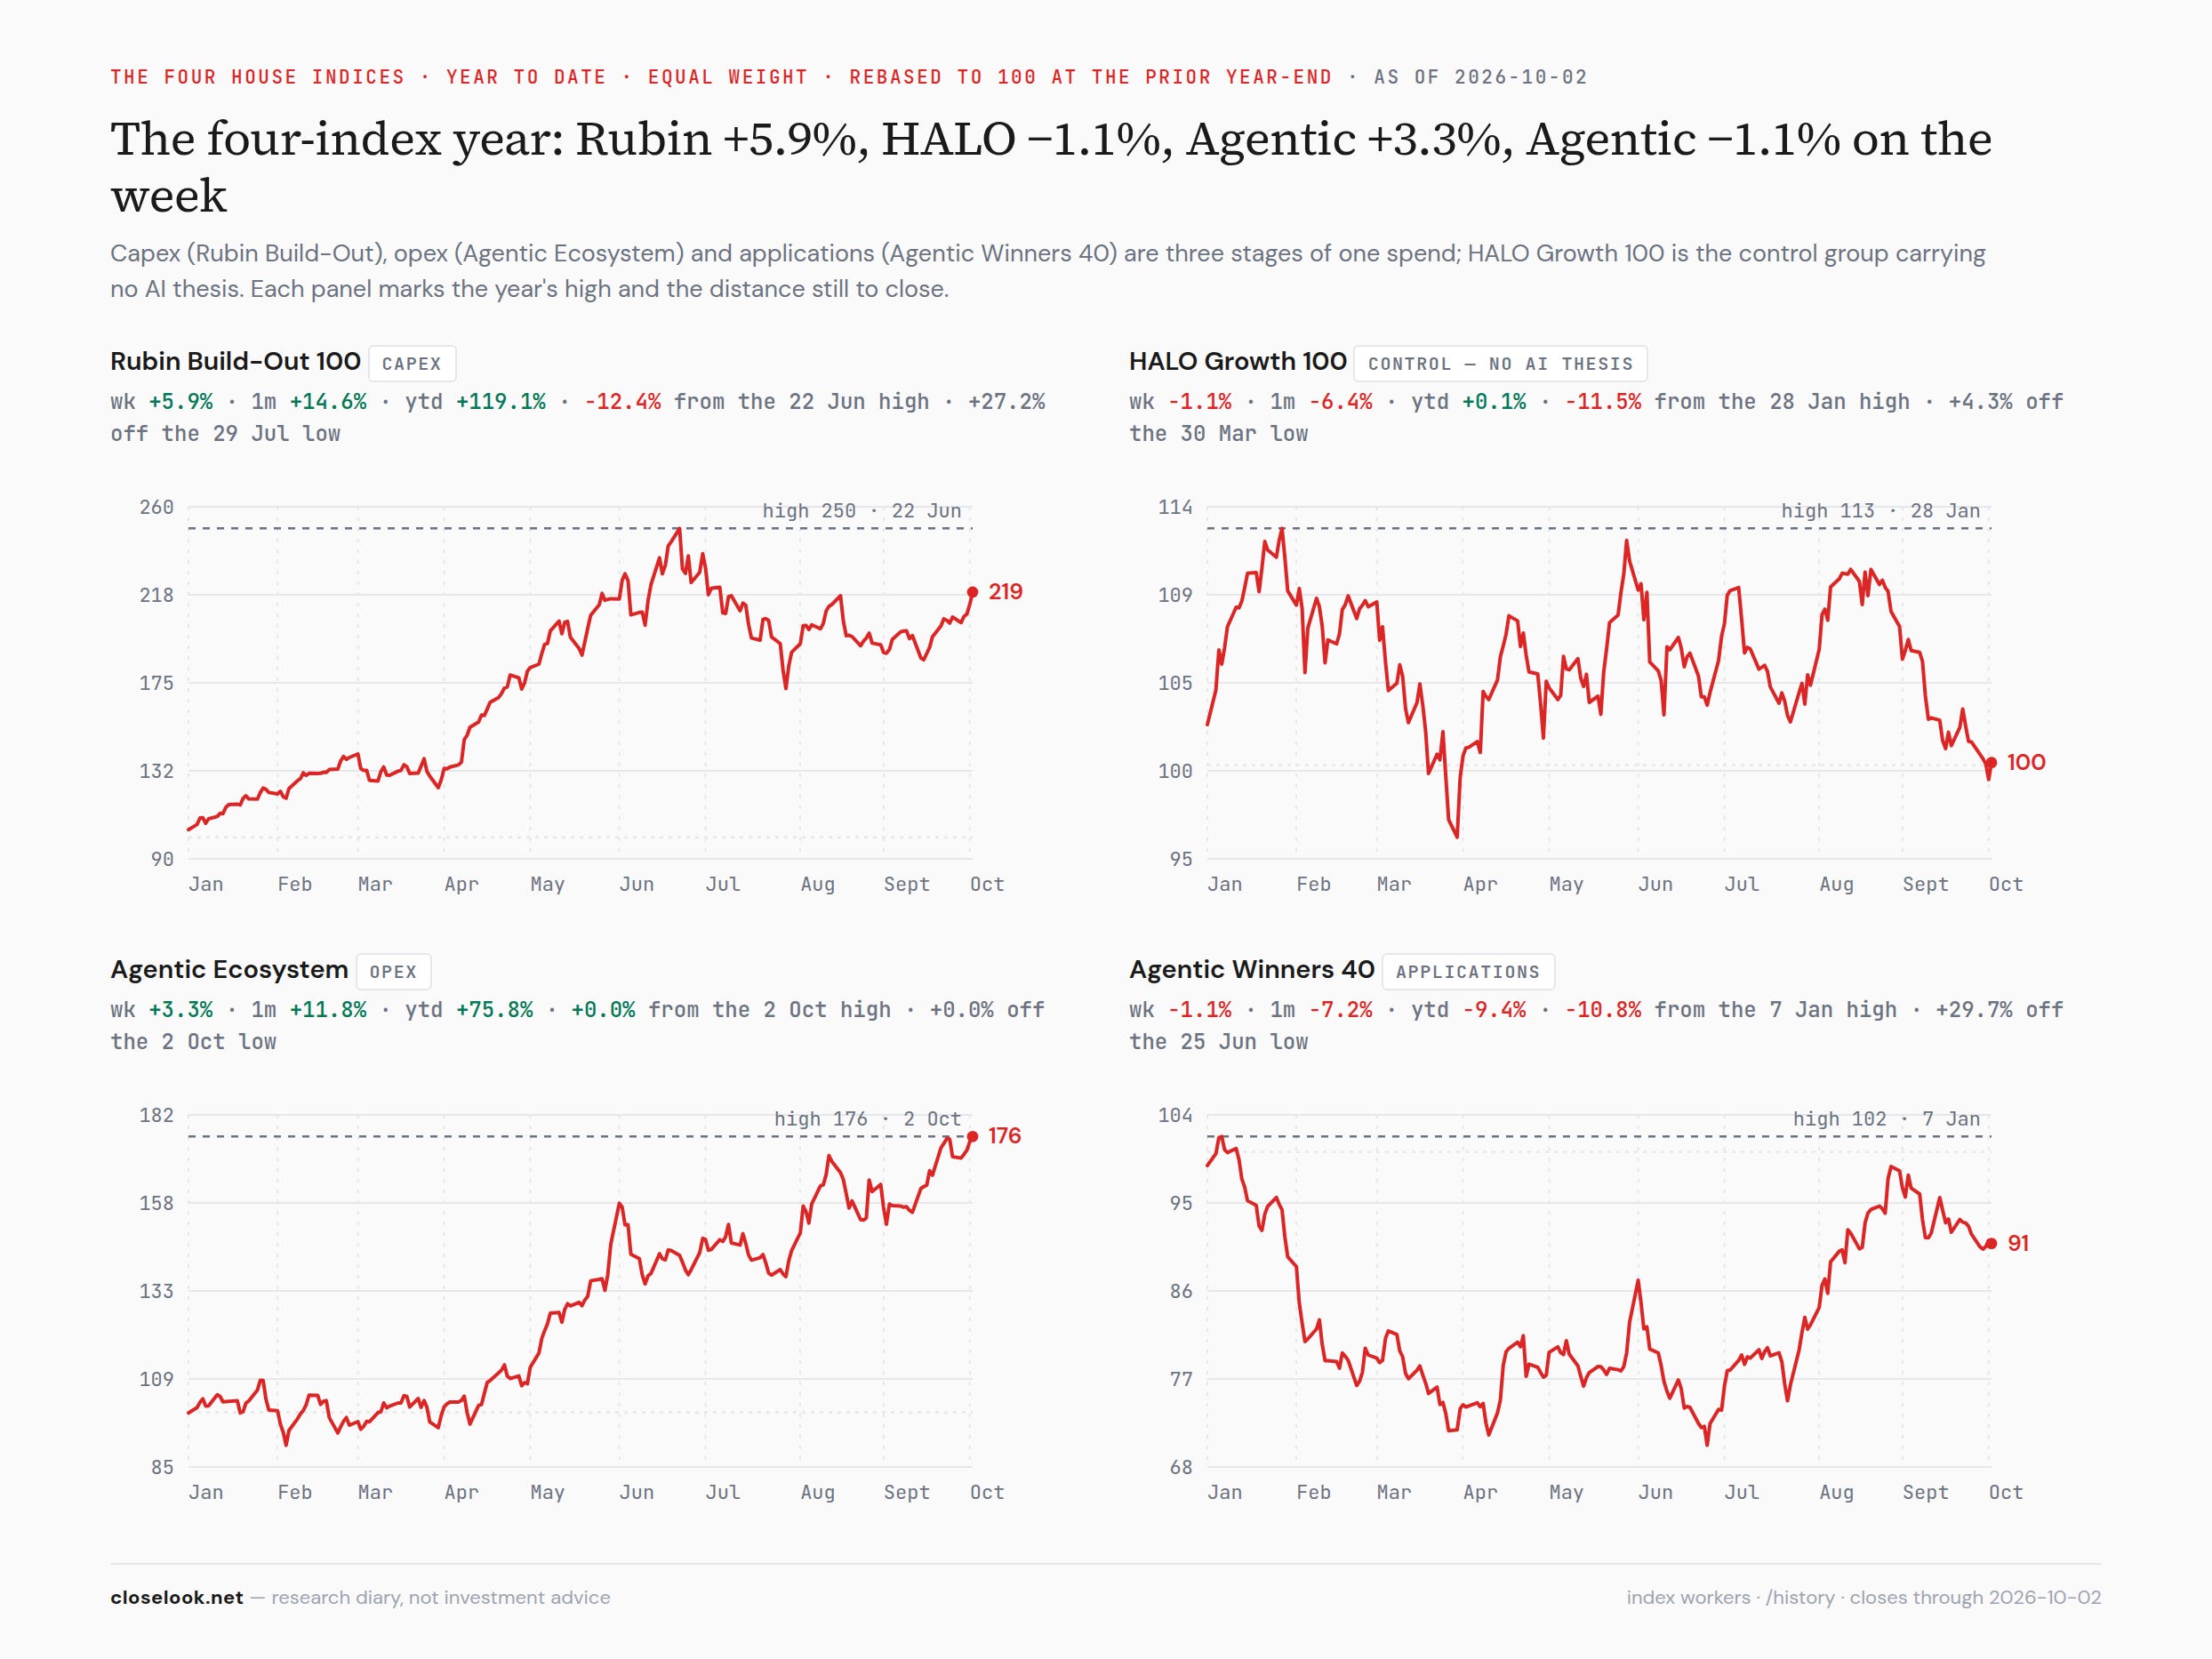
The control group fell while the builder rose six percent. HALO — our growth index carrying no AI thesis — fell 1.13%, −2.1% on the year. Growth without AI went down; growth with AI’s build-out is up 111%. The gap on 2026 is 113 points. That is the same gap, at index altitude, as the one on the map between Taiwan and India.
Read the windows together. On the year capex leads: +111.3% against +76.2% against −8.1%. On the month capex and opex are level: +14.6% against +11.8%, applications −7.2%. Inside applications only one sub-index of nine rose this week — the control plane, +0.61%; the megacap gateway, which carried the platforms’ agent week a fortnight ago, slipped 0.20%. The AI economy is still being paid for at the bottom of the stack and in the middle; at the top it is not yet.
The distances to the highs. Opex at its record. Capex 12.4% under its June 22 high and 27.2% above its July 29 low. Applications 10.8% under its January high. HALO 11.5% under January.
Inside capex: the materials and the testers. The best lines: advanced materials +13.88%, connectivity and materials +10.80%, fab subsystems +10.59%, machine vision +10.26%, testing and metrology +10.04%. The slowest: storage −2.60%, thermal −2.60%, the chip architects −2.50%, HBM memory −0.72%, AI factory systems −0.24%. The memory names rested in Micron’s record week; the people who supply the fabs did the running.
Inside opex: the gateways and the security layer. Nine of fourteen green: runtime and API gateways +6.66%, agentic security +5.20%, execution +4.84%, govern and secure +4.67%, data and memory +4.27%. The red five: foundation models −1.93%, compute operators −1.10%, Europe’s constituents −0.97%, Asia’s −0.74%, substrate flat.
Euro-AI, for the ladder’s sake. The sovereign-Europe index rose 2.72% to 1,320.04, +32.0% on the year, 5.1% under its June high — in a week the Europe fund fell 2.5%. Semi equipment and materials +9.12%, power, grid and cooling +2.02%, chip architecture and cloud +1.87%, enterprise AI +0.49%; medtech −0.33%, defense −0.77%, industrial AI −1.09%. Europe’s AI index rose and Europe fell: the exception that proves this letter’s map.
The regime gauge. The Money Temperature board closed the week at 57, from 62 — read as “mixed / transitional”, the middle of neutral and, by its own construction, not a signal. The instruments: the dollar 75, bitcoin 65, the Nasdaq 100 64, the S&P 60, emerging markets 60, the world ex-US 53, the long bond 40, gold 37. The dollar hottest, gold coldest — the week on one gauge.
